The Complete Overview of the Most Expensive Disasters
The most expensive disasters in recorded history share a disturbing trend: they’re becoming more frequent and costly. Climate change, urbanization, and globalization have amplified the stakes, turning localized events into global financial shocks. The 2011 Tōhoku earthquake and tsunami in Japan, for instance, wasn’t just a regional tragedy—it sent shockwaves through global supply chains, disrupting automotive and electronics production for months. The economic fallout from such events often outlasts the disaster itself, with businesses filing for bankruptcy years later due to interrupted operations or soaring insurance premiums. The financial impact of these catastrophes isn’t uniform. Some disasters, like wars or pandemics, drain resources over extended periods, while others—such as hurricanes or wildfires—inflict concentrated damage in a short span. The 2020 Atlantic hurricane season, for example, set records with 30 named storms, many of which hit densely populated areas. The cumulative cost of these storms, when combined with the economic slowdown caused by COVID-19, pushed the U.S. into one of its worst financial years in decades. The most expensive disasters don’t just hit hard; they linger, reshaping economies and forcing governments to rethink everything from infrastructure spending to disaster response protocols.Historical Background and Evolution
The concept of quantifying disaster costs is relatively modern. Before the 20th century, societies absorbed losses without systematic tracking, relying on communal support or religious institutions to mitigate fallout. The Industrial Revolution changed that, as urbanization and industrialization created concentrated assets—factories, railroads, and later, financial hubs—that became prime targets for disasters. The Great Fire of London in 1666, for example, destroyed 13,200 houses and 87 churches, but its economic impact was absorbed by the city’s insurance markets, which were still in their infancy. Fast-forward to the 20th century, and disasters began to be measured in terms of GDP, with events like the 1929 stock market crash and World War II reshaping financial systems entirely. The post-WWII era marked a turning point. The Marshall Plan, designed to rebuild Europe, demonstrated how governments could channel massive resources into recovery. Yet, it also highlighted the fragility of economies when faced with unplanned shocks. The 1970s oil crisis, triggered by the Yom Kippur War, showed how geopolitical events could send global markets into tailspins, with oil prices quadrupling and triggering recessions. By the 1990s, the rise of insurance markets and risk modeling allowed for more precise estimates of disaster costs, but it also revealed a troubling trend: the most expensive disasters were no longer isolated incidents but interconnected crises. The 1995 Great Hanshin earthquake in Kobe, Japan, cost an estimated $100 billion (adjusted for inflation), but its true impact was felt in the global financial markets, where investor confidence wavered.Core Mechanisms: How It Works
The financial damage from disasters follows a predictable, if devastating, pattern. First comes the immediate destruction: buildings collapse, infrastructure fails, and businesses are wiped out. The cost here is tangible—rebuilding roads, repairing power grids, and compensating victims. But the second phase, often overlooked, is where the real financial hemorrhage occurs. Supply chains break down, insurance companies face unprecedented claims, and governments must step in to prevent economic collapse. The 2011 Fukushima disaster, for example, didn’t just destroy a nuclear plant; it crippled Japan’s energy sector for years, with long-term costs for decommissioning and compensating affected communities still unresolved. The third mechanism is the psychological and systemic impact. Markets react to uncertainty, and disasters create it in spades. The 2008 financial crisis, though not a natural disaster, followed a similar trajectory: a collapse in housing markets led to bank failures, which then triggered a global recession. The most expensive disasters exploit these systemic weaknesses, turning localized events into global financial threats. Take the 2020 COVID-19 pandemic: the initial health crisis was followed by a economic one, with governments worldwide implementing stimulus packages totaling trillions to stave off collapse. The pandemic’s cost wasn’t just in lives lost but in the economic policies it forced upon nations, many of which will take decades to unwind.Key Benefits and Crucial Impact
On the surface, the most expensive disasters seem like pure loss—but they often catalyze change. The 1906 San Francisco earthquake, which destroyed 28,000 buildings, led to modern building codes that saved countless lives in future quakes. Similarly, the 2004 Indian Ocean tsunami spurred global improvements in early warning systems, reducing casualties in subsequent events. The financial pain of these disasters, while immense, frequently leads to innovations in resilience, whether in infrastructure, policy, or technology. The challenge lies in ensuring that these lessons are learned before the next catastrophe strikes. Yet, the benefits are uneven. While some disasters force governments to invest in long-term solutions, others expose deep inequalities. Hurricane Katrina’s devastation in New Orleans laid bare the disparities in disaster response, with wealthier residents evacuating while poorer communities were left stranded. The most expensive disasters don’t just hit hard—they reveal who was prepared and who was left behind. This duality is why these events are so closely studied: they’re not just financial anomalies but mirrors reflecting societal strengths and failures."Disasters don’t create problems—they reveal them." — Dr. Michael Eriksen, disaster economist at the World Bank
Major Advantages
- Policy reforms: The most expensive disasters often accelerate regulatory changes, such as stricter building codes or environmental protections. The 1989 Exxon Valdez oil spill, for example, led to the Oil Pollution Act of 1990, which improved spill response capabilities.
- Technological innovation: Catastrophes drive advancements in early warning systems, disaster-resistant materials, and data analytics for risk assessment. The 2011 Tōhoku earthquake prompted Japan to invest heavily in tsunami-resistant infrastructure.
- Economic stimulus: Large-scale disasters can act as unintended economic boosts for industries like construction, insurance, and emergency services. The post-Katrina rebuilding effort created thousands of jobs in the Gulf Coast region.
- Global cooperation: Some disasters, like the 2004 Indian Ocean tsunami, foster international aid and coordination, leading to stronger humanitarian networks. The UN’s World Conference on Disaster Reduction, held after the tsunami, resulted in the Hyogo Framework for Action.
- Public awareness: High-profile disasters increase societal preparedness, from personal emergency kits to community drills. The 2010 Haiti earthquake spurred global discussions on disaster resilience in developing nations.

Comparative Analysis
| Disaster | Estimated Cost & Key Impact |
|---|---|
| 2011 Tōhoku Earthquake & Tsunami (Japan) | Reportedly over $360 billion. Triggered Fukushima nuclear disaster; disrupted global supply chains, particularly in automotive and electronics sectors. |
| 2008 Financial Crisis (Global) | Estimated at $20 trillion+ in global losses. Led to bank bailouts, austerity measures, and long-term shifts in financial regulation. |
| 2020 COVID-19 Pandemic (Global) | Projected to cost $16 trillion+ in lost global output. Accelerated remote work trends and reshaped healthcare systems worldwide. |
Future Trends and Innovations
The most expensive disasters of the future won’t look like those of the past. Climate change is amplifying extreme weather events, while urbanization is concentrating populations in high-risk zones. The 2021 European floods, which caused an estimated $43 billion in damages, are a harbinger of what’s to come as rising sea levels and heavier rainfall reshape global weather patterns. Meanwhile, cyber disasters—such as ransomware attacks on critical infrastructure—are emerging as a new frontier of financial risk. The 2021 Colonial Pipeline hack, which disrupted U.S. fuel supplies, cost the company $4.4 million in ransom alone, with long-term reputational damage. Innovation in disaster finance is critical. Parametric insurance, which pays out based on predefined triggers (like earthquake magnitude), is gaining traction as a way to distribute risk more efficiently. Similarly, advances in AI and machine learning are improving predictive modeling, allowing governments to anticipate and mitigate risks before they materialize. The challenge will be balancing these technological solutions with ethical considerations—such as who bears the cost when disasters strike marginalized communities. The most expensive disasters of tomorrow won’t just be about recovery; they’ll be about adaptation in an era of unprecedented environmental and technological upheaval.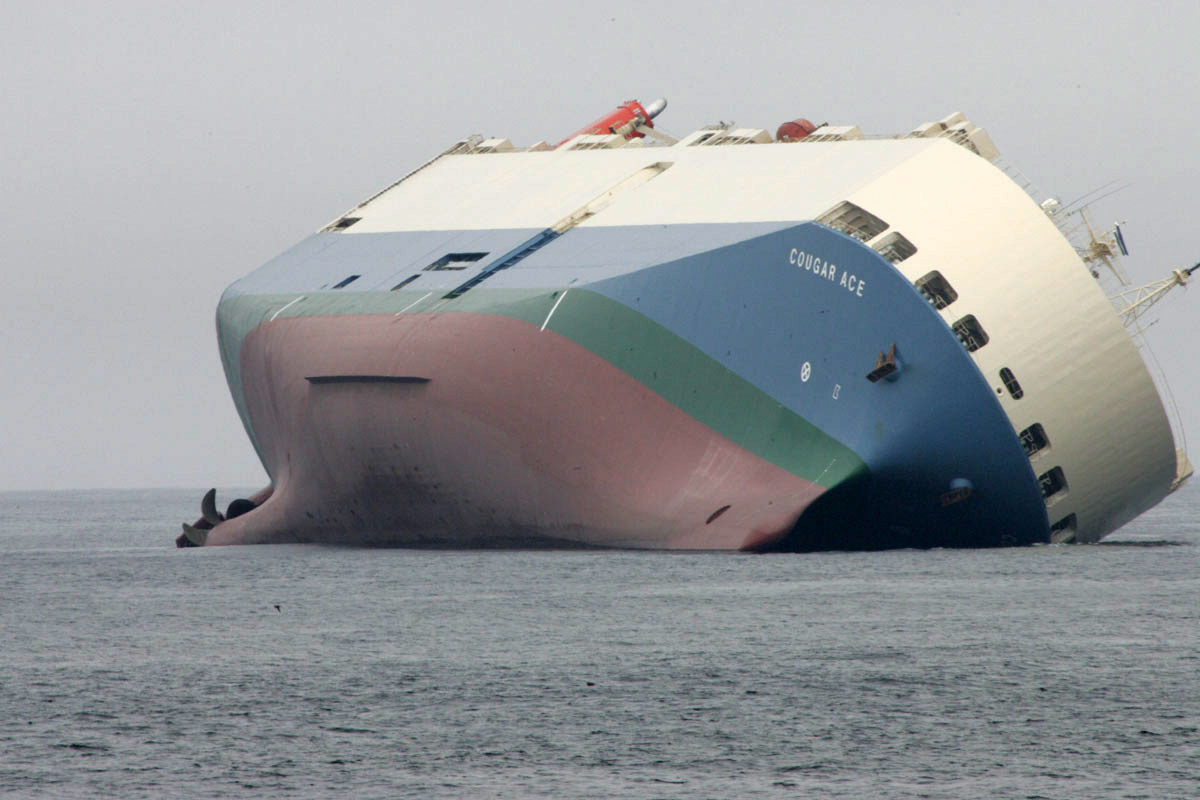
Conclusion
The most expensive disasters are more than financial footnotes—they’re warnings. They expose the limits of human planning, the fragility of global systems, and the often-unseen costs of inaction. Yet, they also offer a roadmap for resilience. The question isn’t whether another catastrophe will dwarf those we’ve seen, but whether societies will learn from history or repeat its mistakes. The answer lies in investment—not just in recovery, but in prevention, innovation, and equity. The financial toll of disasters is inevitable, but their human cost is not. That’s the lesson the most expensive disasters have yet to fully teach us.Comprehensive FAQs
Q: What makes a disaster "expensive" beyond immediate damages?
A: The true cost of a disaster includes long-term economic ripple effects—such as disrupted supply chains, insurance payouts, lost productivity, and government stimulus measures. For example, Hurricane Katrina’s $190 billion price tag (adjusted for inflation) didn’t just cover rebuilding but also included years of economic stagnation in the Gulf Coast region.
Q: Are natural disasters or human-made crises more costly?
A: Both categories have produced some of the most expensive disasters in history. Natural disasters like hurricanes or earthquakes often cause concentrated damage, while human-made crises—such as wars or financial collapses—can drag on for years, draining resources globally. The 2008 financial crisis and the COVID-19 pandemic, for instance, had far-reaching economic impacts that outlasted their immediate triggers.
Q: How do insurance companies factor into disaster costs?
A: Insurance plays a dual role. It provides financial relief to victims but can also strain markets when claims surge after a major disaster. The 2017 Atlantic hurricane season, which included Harvey, Irma, and Maria, led to over $100 billion in U.S. insurance claims, forcing some insurers to raise premiums or withdraw from high-risk areas. This, in turn, shifts the burden to governments or taxpayers.
Q: Can disasters ever be "good" for the economy?
A: While no one benefits from human suffering, some disasters indirectly stimulate economic activity. Rebuilding efforts create jobs, and disasters often lead to policy changes that boost long-term resilience. For example, the 1906 San Francisco earthquake led to modern building codes that reduced future losses. However, these benefits are usually overshadowed by the immediate devastation.
Q: What’s the most underrated expensive disaster?
A: The 2010 Deepwater Horizon oil spill, which cost BP an estimated $65 billion in settlements and cleanup, is often overshadowed by larger events. Yet, its environmental and economic impact—including long-term damage to Gulf Coast fisheries and tourism—has had lasting consequences that are still being felt today.
Q: How do developing nations handle the financial fallout of disasters?
A: Developing nations often lack the resources to recover from disasters, relying heavily on international aid. The 2010 Haiti earthquake, for example, caused an estimated $8 billion in damages (around 120% of Haiti’s GDP), leaving the country dependent on foreign assistance for reconstruction. This highlights the global inequality in disaster resilience, where wealthier nations can absorb shocks more easily.
Q: Are there ways to predict the most expensive disasters before they happen?
A: While it’s impossible to predict disasters with certainty, advances in climate modeling, seismic monitoring, and AI-driven risk assessment are improving early warnings. For instance, the U.S. National Oceanic and Atmospheric Administration (NOAA) uses supercomputers to forecast hurricane paths, allowing for better evacuation planning. However, the most expensive disasters often arise from interconnected risks—like pandemics or financial crises—that are harder to anticipate.
Q: What’s the biggest lesson from past disasters?
A: The most expensive disasters teach that preparation is far cheaper than recovery. Investing in infrastructure, early warning systems, and equitable policies can mitigate losses. The 2004 Indian Ocean tsunami, for example, led to the creation of the Global Facility for Disaster Reduction and Recovery, which has since helped nations build resilience in tsunami-prone regions. The lesson? Proactive measures save lives and money in the long run.
