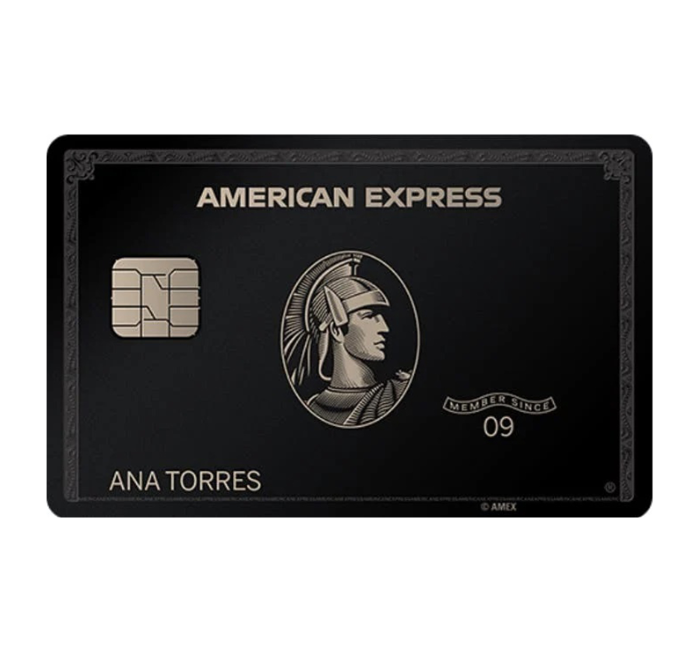
Where It All Began
The Centurion Card wasn’t born from a marketing brainstorm. It emerged in the late 1990s as a solution to a problem: American Express had a growing class of ultra-high-net-worth clients whose spending habits outpaced the rewards of even their most premium cards. These weren’t just wealthy individuals—they were collectors, jet-setters, and business moguls who demanded more than points or cashback. They wanted access. The first iteration was unofficial, a handshake deal between Amex’s private banking division and a select group of clients. There were no mass mailings, no telemarketing scripts. Instead, relationship managers—those who’d spent years cultivating trust—would quietly offer the card to clients who spent $250,000 or more annually on Amex cards. The fee? A modest $750. The perks? A personal assistant, a dedicated concierge, and a sense of belonging to an exclusive club. By the early 2000s, the program had formalized, though Amex never advertised it. The card’s existence was whispered about in private banking circles, passed down like a secret handshake. The criteria tightened. The fee crept upward. And the Amex Black Card became less about spending limits and more about lifestyle alignment.The Early Signs
The first clue that someone might be on the path to qualifying for Amex Black Card wasn’t their income statement—it was their spending patterns. Amex’s algorithms didn’t just track purchases; they analyzed how purchases were made. Were flights booked last-minute? Were hotel stays in boutique properties, not chains? Were dinners at Michelin-starred restaurants, not casual eateries? Relationship managers looked for three red flags: 1. Consistent high spending—not just in one category, but across travel, dining, and entertainment. 2. Loyalty to Amex—clients who paid their bills in full, never chased rewards, and used Amex as their primary card. 3. Social proof—references from existing Centurion members, or connections to industries where the card held value (private equity, luxury real estate, high-end retail). The card wasn’t a reward for wealth; it was a reward for engagement. And engagement, in this case, meant spending in a way that signaled both affluence and discerning taste.The Turning Point
Everything changed in 2009. The financial crisis had gutted Amex’s revenue, and the Centurion program—once a niche offering—became a strategic pivot. The card’s fee doubled, then tripled. The spending requirement rose from $250,000 to $300,000 annually, then higher. But the real shift wasn’t numerical; it was cultural. Amex realized the Centurion Card wasn’t just a credit product—it was a membership. The fee wasn’t just a cost; it was an investment in exclusivity. The more selective the program became, the more desirable it appeared. Word spread not through ads, but through aspirational networks: the young tech CEO who saw the card in the hands of a venture capitalist at a Silicon Valley mixer; the art collector who noticed how Centurion members bypassed waitlists for gallery openings. The turning point wasn’t a policy change—it was a perception shift. The card stopped being a tool for the ultra-rich and became a symbol of elite belonging. And with that shift came a new, unspoken rule: You didn’t just need to qualify for Amex Black Card—you needed to earn it."The Centurion Card isn’t about the money you have. It’s about the doors you open—and the people who open them for you." — Anonymous Amex private banking executive, 2012
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1997–2001 | Unofficial "Platinum Plus" program for clients spending $250K+/year. Fee: $750. Perks: Dedicated concierge, no foreign transaction fees. |
| 2002–2006 | Formalized as the Centurion Card. Spending threshold rises to $300K. Fee jumps to $2,500. First "invitation-only" marketing begins. |
| 2007–2012 | Financial crisis forces Amex to tighten criteria. Fee climbs to $5,000. Referrals from existing members become critical. "Lifestyle spending" (e.g., private jet charters) gains weight in approvals. |
| 2013–Present | Fee stabilizes around $5,000–$15,000 (varies by region). Spending threshold fluctuates between $300K–$500K+ annually. Amex introduces "Centurion Lounge" access as a key perk. Social and professional networks play a larger role than ever. |
Lessons From the Journey
The evolution of the Amex Black Card reveals four key truths about how to qualify for it: - Spending isn’t the only metric. While annual spend is critical, Amex’s algorithms now weigh diversity of spending—travel, fine dining, luxury retail—as heavily as the total. - Relationships matter more than applications. The card is often offered by existing members or private bankers who vouch for a prospect’s lifestyle and potential. - The fee is a test. Amex doesn’t want clients who’ll balk at $5,000—it wants those who’ll see it as a necessary expense, not a cost. - Exclusivity is self-reinforcing. The fewer cards issued, the more desirable they become. Amex’s silence on the program fuels its mystique.Where Things Stand Today
As of 2024, qualifying for Amex Black Card remains an art, not a science. The official requirements—if they exist—are buried in internal Amex documents. What’s public is a mix of industry estimates, leaked details, and the experiences of cardholders who’ve shared their stories (often anonymously). The spending threshold is fluid. While $300,000 annually is often cited, some reports suggest it’s closer to $500,000+ for new applicants, especially in high-cost markets like New York or London. The fee, meanwhile, has stabilized in the $5,000–$15,000 range, depending on the applicant’s profile and Amex’s appetite for their business. But the real gatekeepers aren’t numbers—they’re people. Amex’s private bankers, who act as gatekeepers, look for clients who: - Have multiple Amex cards (e.g., Platinum, Platinum Select) and use them consistently. - Spend on high-end, non-rewardable purchases (e.g., private jet flights, art auctions, yacht charters). - Are connected to industries where the card holds value (e.g., private equity, luxury real estate, high-end hospitality). The process is still invitation-only. There’s no public application, no online portal. If you’re not on Amex’s radar—or if you don’t have a relationship manager pushing your case—your chances are slim.
Conclusion
The Amex Black Card isn’t just a credit card; it’s a membership in a parallel economy. It’s for those who understand that wealth isn’t measured in bank balances alone, but in access, connections, and unspoken privileges. The path to securing it isn’t a checklist—it’s a journey, one that requires patience, strategic spending, and the right kind of influence. For most, the answer to how to qualify for Amex Black Card starts with a simple question: Who do you know? But for those willing to play the long game—spending wisely, building relationships, and proving they belong—it’s not just a card. It’s a key.Comprehensive FAQs
Q: Is there a public way to apply for the Amex Black Card?
A: No. The Centurion Card has no public application process. Approval comes through private invitations from Amex’s private banking division or referrals from existing members. Attempting to apply directly will get you nowhere—only a relationship manager can submit your name for consideration.
Q: What’s the minimum income required to qualify?
A: There’s no official minimum income requirement, but industry estimates suggest $500,000+ in annual earnings is a common baseline. However, income alone isn’t enough—spending habits, credit history, and relationships weigh just as heavily. Some high-net-worth individuals with lower incomes have qualified if their spending aligns with Amex’s criteria.
Q: Can I get the Amex Black Card with a credit score below 800?
A: While an exceptional credit score (typically 800+) is nearly mandatory, Amex has approved applicants with slightly lower scores if their financial profile is otherwise strong. However, a score below 750 would be a significant hurdle. The focus is on payment history, credit utilization, and overall financial health—not just the number.
Q: How do I increase my chances of getting invited?
A: The best strategy is a multi-pronged approach: 1. Maximize Amex spending—focus on high-value, non-rewardable purchases (e.g., private jet travel, luxury real estate closings). 2. Build a relationship with an Amex private banker (often through referrals from existing Centurion members). 3. Leverage social proof—if you move in circles where Centurion members operate, they may vouch for you. 4. Avoid reward-chasing—Amex prefers clients who use the card for lifestyle spending, not points or cashback optimization.
Q: What happens if I’m denied?
A: Denials are rare, but they happen—often due to incomplete financial profiles or lack of relationship capital. If denied, Amex may offer an alternative (e.g., a Platinum Card upgrade) or suggest steps to improve your standing. Some applicants later qualify after increasing their Amex spend or strengthening their banker relationship. There’s no formal appeals process, but persistence pays off.
Q: Are there rumors about a "blacklist" for people who’ve been rejected?
A: There’s no official "blacklist," but Amex’s systems do track declined applicants. If you’re rejected once, it becomes harder to qualify in the future unless you significantly improve your profile (e.g., higher spend, better credit, or a stronger referral). The key is to avoid aggressive reapplication—subtle, strategic progress is more effective.
Q: Can I get the Amex Black Card if I live outside the U.S.?
A: Yes, but the criteria vary by region. In Europe, Asia, and the Middle East, the card is more accessible in some markets (e.g., Dubai, Singapore) due to higher concentrations of ultra-high-net-worth individuals. In others (e.g., Latin America, emerging markets), the threshold may be higher due to currency fluctuations and local economic factors. Amex’s private banking teams in these regions set their own rules.
Q: What’s the biggest mistake people make when trying to qualify?
A: Assuming they can "game" the system. Many applicants focus solely on increasing their income or credit score, but Amex cares more about lifestyle alignment. Others make the mistake of applying directly or asking their banker outright—both red flags. The best approach is to let Amex come to you by spending in ways that signal you’re already part of their world.
