The Short Answers
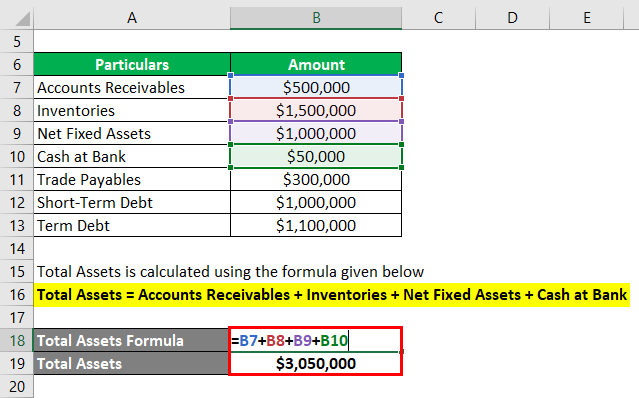
- Use `=SUM(Assets) - SUM(Liabilities)` as a starting point, but layer in valuation methods (e.g., DCF for businesses, cost basis for collectibles).
- For dynamic tracking, combine `VLOOKUP` for asset classes with `XLOOKUP` for liability schedules—update monthly to reflect market or debt changes.
- Inflation erodes net worth over time; apply a CPI-adjusted growth rate (e.g., `=FV(0.02, years, 0, -initial_net_worth)`) to compare apples-to-apples.
- Tax liabilities aren’t liabilities—they’re deferred obligations. Use `=IF(tax_deferred > 0, net_worth - tax_deferred, net_worth)` to separate them.
Deep Dive: The Full Picture
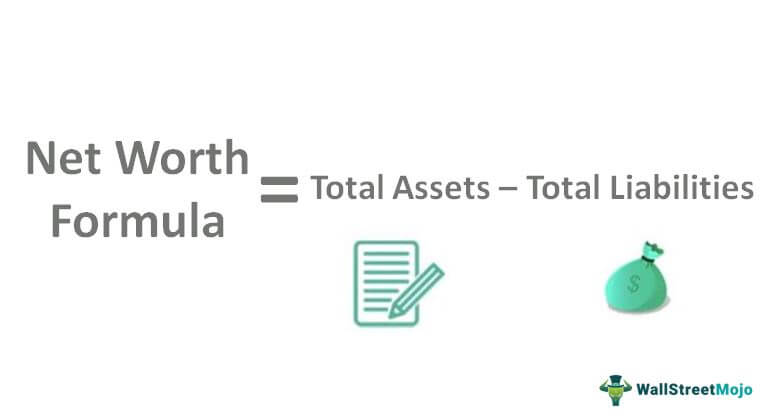
The excel formula for net worth isn’t a single cell but a system. At its core, it’s a balance sheet: assets on one side, liabilities on the other. But the devil lies in the definitions. A 401(k) balance isn’t an asset—it’s a future liability if you withdraw early. A vintage car’s value isn’t its purchase price but its auction record, adjusted for condition. These distinctions require either manual overrides or nested formulas that pull from external data (e.g., `WEBSERVICE` for stock prices, `IMPORTXML` for real estate comps). The second layer is timing. Net worth isn’t static. A stock portfolio’s value swings daily; a business’s worth changes with earnings reports. The excel formula for net worth must therefore either: 1. Refresh dynamically (via `INDIRECT` or `OFFSET` to pull live data), or 2. Snapshot periodically (e.g., `=IF(MONTH(TODAY())=1, SUM(Assets), previous_snapshot)`). Static spreadsheets fail here. Dynamic ones require either VBA automation or cloud-linked cells (e.g., Google Sheets’ `IMPORTRANGE`).The Context You Need
Financial planners often treat net worth as a vanity metric. It’s not. It’s a leading indicator of financial health—if calculated correctly. The excel formula for net worth must account for: - Illiquidity discounts: Private company shares or real estate may trade at 30–50% below public equivalents. - Opportunity costs: The time spent managing assets (e.g., a rental property) has a dollar value. - Behavioral biases: People overvalue assets they own (the endowment effect). A spreadsheet can’t fix this, but it can force objective valuation. The alternative—using a generic template—leads to errors. For example, treating a Roth IRA’s balance as liquid ignores the 5-year holding requirement for withdrawals. The excel formula for net worth must therefore include conditional logic for asset classes with restrictions.The Mechanics
Start with two columns: Assets and Liabilities. But don’t stop there. 1. Asset Valuation: - Liquid assets (cash, stocks): Use `=SUM(Account_Balances)` with `VLOOKUP` to pull from a master list. - Illiquid assets (real estate, businesses): Assign a valuation method (e.g., `=NOI / Cap_Rate` for properties) and update annually. - Intangible assets (patents, goodwill): Use `=Cost_Basis * (1 - Amortization_Rate)` if applicable. 2. Liability Adjustments: - Debt: Calculate present value with `=PV(rate, years, -monthly_payment)`. For example, a $300K mortgage at 4% over 30 years has a PV of ~$223K. - Deferred taxes: Subtract `=Tax_Liability * (1 - Discount_Rate^years)` to reflect time value. - Contingent liabilities (e.g., guarantees): Estimate a probability-weighted value (e.g., `=Liability_Amount * 0.3` if 30% likely). Combine these with: ```excel =SUM(Assets_Column) - SUM(Liabilities_Column) - SUM(Deferred_Taxes) ``` But add a third layer: Net Worth Growth Rate. Use: ```excel =(Ending_Net_Worth - Beginning_Net_Worth) / Beginning_Net_Worth ``` Track this monthly to spot trends before they become crises.Details That Change the Picture
Most spreadsheets treat net worth as a single number. Reality demands segmentation. Break it into: - Core net worth (liquid assets minus high-interest debt). - Investment net worth (stocks, bonds, retirement accounts). - Human capital (future earning potential, estimated via `=Years_Left_Working Annual_Salary 0.7` for a rough proxy). The excel formula for net worth should let you toggle between these views. For example: ```excel =IF(Segment="Core", Core_Assets - High_Interest_Debt, IF(Segment="Investment", Investment_Assets - Liabilities, Human_Capital_Proxy)) ``` Another critical adjustment: Inflation. A net worth of $1M in 2010 is worth ~$1.3M in 2023. Use: ```excel =Net_Worth * (1 + CPI_Growth_Rate)^Years ``` to compare across time."Net worth is a snapshot, but wealth is a movie. The best spreadsheets don’t just show the frame—they reveal the editing." — A financial analyst at a top-tier private bank (anonymized)
| Asset/Liability Type | Excel Formula Adjustment |
|---|---|
| Publicly Traded Stocks | `=SUM(Portfolio) * (1 - 0.002)` (accounts for trading costs) |
| Private Business Equity | `=Last_Round_Valuation * (1 - Illiquidity_Discount_0.4)` |
| Mortgage Debt | `=PV(0.04/12, 360, -1500, -300000)` (present value of remaining balance) |
| Cryptocurrency | `=COALESCE(Wallet_Balance, 0) * Exchange_Rate` (with error handling for zero values) |
| Deferred Taxes | `=Tax_Liability * (1 - (1 + Discount_Rate)^-Years)` |
Conclusion
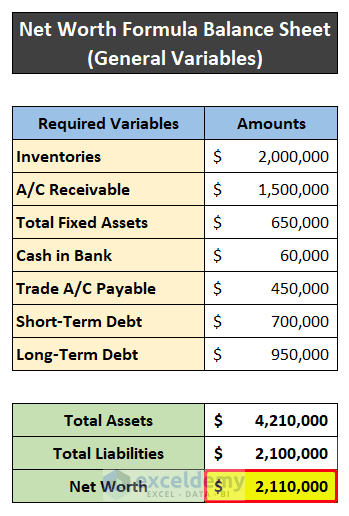
The excel formula for net worth isn’t about plugging numbers into a template. It’s about building a system that reflects your unique financial ecosystem. The formulas above are starting points—customize them for your asset classes, risk tolerance, and goals. The key is dynamic updates: net worth isn’t a static number but a living metric that evolves with market conditions, personal decisions, and economic shifts. For most people, the spreadsheet is the tool—not the solution. The real work lies in the discipline to maintain it, the honesty to adjust valuations, and the foresight to ask: What does this number actually tell me about my future? A well-built excel formula for net worth answers that question with precision.Comprehensive FAQs
Q: Can I use the same formula for a business net worth as for personal net worth?
A: No. Personal net worth focuses on liquidity and personal liabilities, while business net worth requires adjustments for goodwill, intangible assets, and enterprise value (e.g., `=Revenue * EBITDA_Multiple`). Use separate spreadsheets or clearly segmented columns.
Q: How often should I update my net worth spreadsheet?
A: Monthly for liquid assets (stocks, cash), quarterly for illiquid ones (real estate, private equity). Automate pulls where possible (e.g., `GOOGLEFINANCE` for stocks) but manually verify illiquid valuations.
Q: What’s the best way to handle assets with fluctuating values (e.g., crypto, art)?
A: Use a moving average for volatility-prone assets. For example, store the last 12 monthly values and calculate `=AVERAGE(Last_12_Values)`. For art, pull auction data via `IMPORTXML` and apply a 10–20% illiquidity discount.
Q: Should I include my home’s value in net worth if I’re not planning to sell?
A: Yes, but with caveats. If the home is your primary residence, its value contributes to net worth—but only if you’re willing to liquidate it. For tracking purposes, use a cost basis (purchase price + improvements) unless you have a recent appraisal.
Q: How do I account for assets I’ve inherited but haven’t yet sold or transferred?
A: List them at fair market value on the date of inheritance, then track their growth/loss separately. Use `=IF(Inherited_Date > Last_Update, FMV, Previous_Value)` to ensure accuracy. Consult a tax professional to handle stepped-up basis implications.
Q: Can I build this in Google Sheets instead of Excel?
A: Absolutely. Replace `VLOOKUP` with `XLOOKUP`, use `GOOGLEFINANCE` for stock data, and leverage `IMPORTRANGE` for cross-sheet collaboration. The core excel formula for net worth logic translates directly, though some advanced functions (e.g., `WEBSERVICE`) require Excel’s Power Query.
