Where It All Began
The idea that wealth requires professional stewardship didn’t emerge from Wall Street’s boardrooms. It came from the ledgers of 19th-century European aristocrats who, despite their titles, found themselves bankrupt because no single mind could track the interest on their debt, the yield on their vineyards, and the political risks of their foreign investments. The first financial advisors weren’t selling stocks—they were selling attention. By the early 20th century, American robber barons faced the same problem: their fortunes grew too quickly for even the most meticulous spreadsheets to capture. J.P. Morgan’s private bankers didn’t exist to manage $10 million portfolios; they existed because Morgan himself couldn’t sleep at night wondering if his railroads were overvalued. The turning point came in the 1970s, when the U.S. tax code became a labyrinth of deductions, capital gains tiers, and inflation-adjusted brackets. The IRS’s complexity outpaced the average accountant’s ability to advise clients in real time. That’s when the first "wealth managers" appeared—not as salespeople, but as translators. Their value wasn’t in beating the market; it was in ensuring clients didn’t lose it to paperwork. The threshold wasn’t a net worth figure. It was the moment a client’s financial life became too entangled with legal, tax, and investment systems to navigate alone.The Early Signs
The first red flag isn’t a balance sheet. It’s a feeling: the growing sense that your financial decisions are being made for you, not by you. This happens long before you hit the "millionaire" label. A software engineer in Austin might realize they’re paying $2,000 annually in bank fees because their high-yield accounts are fragmented across five institutions—each one offering a "special" rate that’s only available if you call customer service at 3 AM. A real estate investor in Miami could discover their LLC’s liability shield is paper-thin because they never updated their operating agreement after a divorce. These aren’t high-net-worth problems. They’re attention deficit problems. The second sign is the audit. Not the IRS kind—though that’s often the wake-up call—but the internal one. You start Googling terms you don’t understand ("what’s a 1031 exchange?"), or you notice your "diversified" portfolio is 60% concentrated in a single sector because you never got around to selling. The advisor’s role here isn’t to fix the damage. It’s to ask: Why didn’t you see this sooner? The answer usually boils down to one thing: your brain can only handle so many moving parts before it starts making up stories to fill the gaps.The Turning Point
The shift from DIY finance to professional guidance isn’t about crossing a dollar threshold. It’s about crossing a cognitive one. Studies in behavioral economics show that the average person’s ability to track more than three major financial variables at once collapses under pressure. Add in estate planning, tax-loss harvesting, and currency hedging, and what you’re left with is a system designed to exploit your limitations. The advisor’s job isn’t to replace your judgment. It’s to externalize the variables you can’t hold in your head. This is why the most successful advisors don’t target clients with $5 million portfolios. They target clients who’ve just hit the point where their portfolio’s complexity exceeds their ability to monitor it. That’s often around $500,000 in liquid assets—but it can be as low as $150,000 if those assets are tied to illiquid investments like private equity or real estate. The key isn’t the number. It’s the friction: the moment you spend more time managing your finances than you do living your life."People don’t need an advisor at $1 million. They need one at $100,000—when the difference between a good decision and a bad one isn’t a few percentage points, but whether they’ll have to sell their house to cover a tax bill." — Sarah Chen, Partner at Horizon Wealth Management (interview, 2023)
The Build-Up, Year by Year
| Period | What Changed |
|---|---|
| 1980s–1990s | Advisors shifted from managing assets to managing clients—introducing psychological profiling to assess risk tolerance. The threshold for hiring one rose as DIY tools (like Vanguard’s mutual funds) made basic investing accessible. However, the real tipping point was the 1996 Taxpayer Relief Act, which created new capital gains brackets, forcing even middle-class investors to seek specialized advice. |
| 2000s | The dot-com crash and 2008 financial crisis exposed the limits of generic advice. Advisors began offering "bucket strategies" (short-term, mid-term, long-term allocations) to clients with as little as $250,000, recognizing that liquidity needs varied wildly. The rise of robo-advisors (2010s) temporarily lowered the bar for basic portfolio management, but the demand for human oversight surged for clients with complex tax situations or non-traditional assets. |
| 2020s | Crypto, SPACs, and AI-driven investments created new asset classes that even seasoned advisors struggled to integrate. The threshold for hiring an advisor dropped for tech-savvy clients but rose for those with legacy wealth, as estate planning became intertwined with digital asset inheritance. The pandemic also accelerated the shift to "concierge" financial services, where advisors handle everything from college funding to vacation home mortgages. |
Lessons From the Journey
- The $1M rule is a myth. The real threshold is when your financial life requires more than one person’s full-time attention. For some, that’s $100,000; for others, it’s $10 million.
- Taxes are the first warning sign. If you’re spending more than 10 hours a year on tax filings, you’ve already crossed the line.
- Liquidity matters more than net worth. A $2M portfolio tied to illiquid assets (real estate, private equity) needs an advisor sooner than a $1M portfolio in cash and stocks.
- The advisor’s value isn’t in picking stocks. It’s in ensuring you don’t accidentally pick the wrong structure for those stocks (e.g., holding crypto in a traditional IRA).
- Psychological readiness is the final hurdle. You can have $5M, but if you’re not willing to delegate control, the advisor’s role becomes advisory in name only.
- The best time to hire one is before you need them. The clients who wait until a crisis (divorce, audit, market crash) are the ones who pay the highest fees—and often the highest penalties.
Where Things Stand Today
The modern financial advisor isn’t a gatekeeper of wealth. They’re a firewall against cognitive overload. Today’s high-net-worth individuals don’t just need someone to manage their money—they need someone to manage the information around their money. This includes tracking regulatory changes (e.g., SEC rules on private funds), optimizing cross-border tax strategies, and even advising on non-financial risks like cybersecurity for digital assets. The threshold for hiring one has fragmented: a young professional with $300,000 in student loans and a side hustle might need an advisor just as much as a retiree with $3M in IRAs. What hasn’t changed is the core question: At what point does your financial life become too complex for you to navigate alone? The answer isn’t a number. It’s the moment you realize you’re no longer in control—you’re just along for the ride.
Conclusion
The myth of the "self-made millionaire" obscures the reality: wealth without guidance isn’t freedom. It’s exposure. The clients who resist hiring an advisor until they’re forced to often find themselves in one of two positions: either they’ve lost a significant portion of their net worth to preventable mistakes, or they’ve become so risk-averse that their portfolio stagnates. Neither outcome is inevitable. The difference lies in recognizing the threshold—not when you can afford an advisor, but when you can’t afford not to have one. The number doesn’t matter. What matters is the moment you look at your financial life and see a system, not a spreadsheet. That’s when the question shifts from "At what net worth should you get a financial advisor?" to "Why did I wait this long?"Comprehensive FAQs
Q: Is there a universal net worth threshold for hiring a financial advisor?
No. The threshold varies based on asset type, tax complexity, and personal bandwidth. A $500,000 portfolio in liquid assets might not need an advisor, but the same amount tied to real estate, private equity, or international holdings likely does. The real question is: Are you spending more than 5–10 hours a month managing finances? If yes, you’ve crossed the line.
Q: Can a financial advisor help if I’m already over $1M but haven’t hired one yet?
Absolutely—but the damage control will cost more. Advisors often help clients "clean up" past mistakes (e.g., restructuring a concentrated stock position, fixing estate planning oversights). However, the earlier you bring them in, the more they can act as a strategist rather than a damage controller. The first three years with an advisor are typically the most cost-effective.
Q: Do I need an advisor if I’m young but have a high income (e.g., $200K/year)?
Possibly. High earners often face unique challenges: maximizing 401(k) contributions, navigating stock options, or planning for irregular income (e.g., freelancers, commission-based roles). If your tax situation is complex or you’re saving aggressively, an advisor can help optimize cash flow and tax-efficient strategies—even if your net worth is still growing.
Q: What’s the difference between a financial advisor and a wealth manager?
The terms are often used interchangeably, but wealth managers typically handle all aspects of a client’s financial life—estate planning, tax strategy, insurance, and even lifestyle logistics (e.g., concierge services for high-net-worth clients). Financial advisors may focus narrowly on investments or retirement planning. The distinction matters at higher net worth levels ($2M+), where coordination across disciplines becomes critical.
Q: How do I know if I’m being taken advantage of by an advisor?
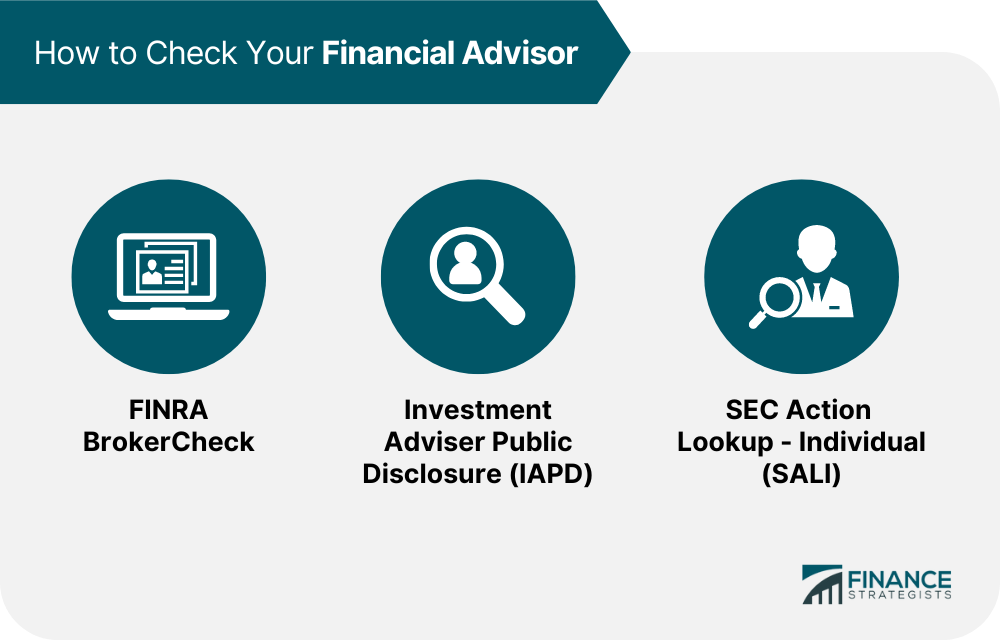
Watch for these red flags: high fees without clear value (e.g., 2%+ AUM for basic portfolio management), frequent trades that generate commissions, or advice that aligns with their interests (e.g., pushing proprietary products). A good advisor should explain their fee structure upfront, provide a written plan, and avoid conflicts of interest. If you’re unsure, ask for a second opinion—or switch to a fiduciary advisor who’s legally obligated to act in your best interest.
Q: What’s the most common mistake people make when hiring an advisor?
Assuming the advisor’s success is tied to your portfolio’s growth. The best advisors don’t promise returns—they promise risk mitigation. Clients who focus solely on performance often end up with advisors who take unnecessary risks or overconcentrate assets. Instead, look for advisors who ask: "What keeps you up at night?"—not "How much do you want to make?"
