
The Complete Overview of How Much Net Worth You Need to Join the Top 1%
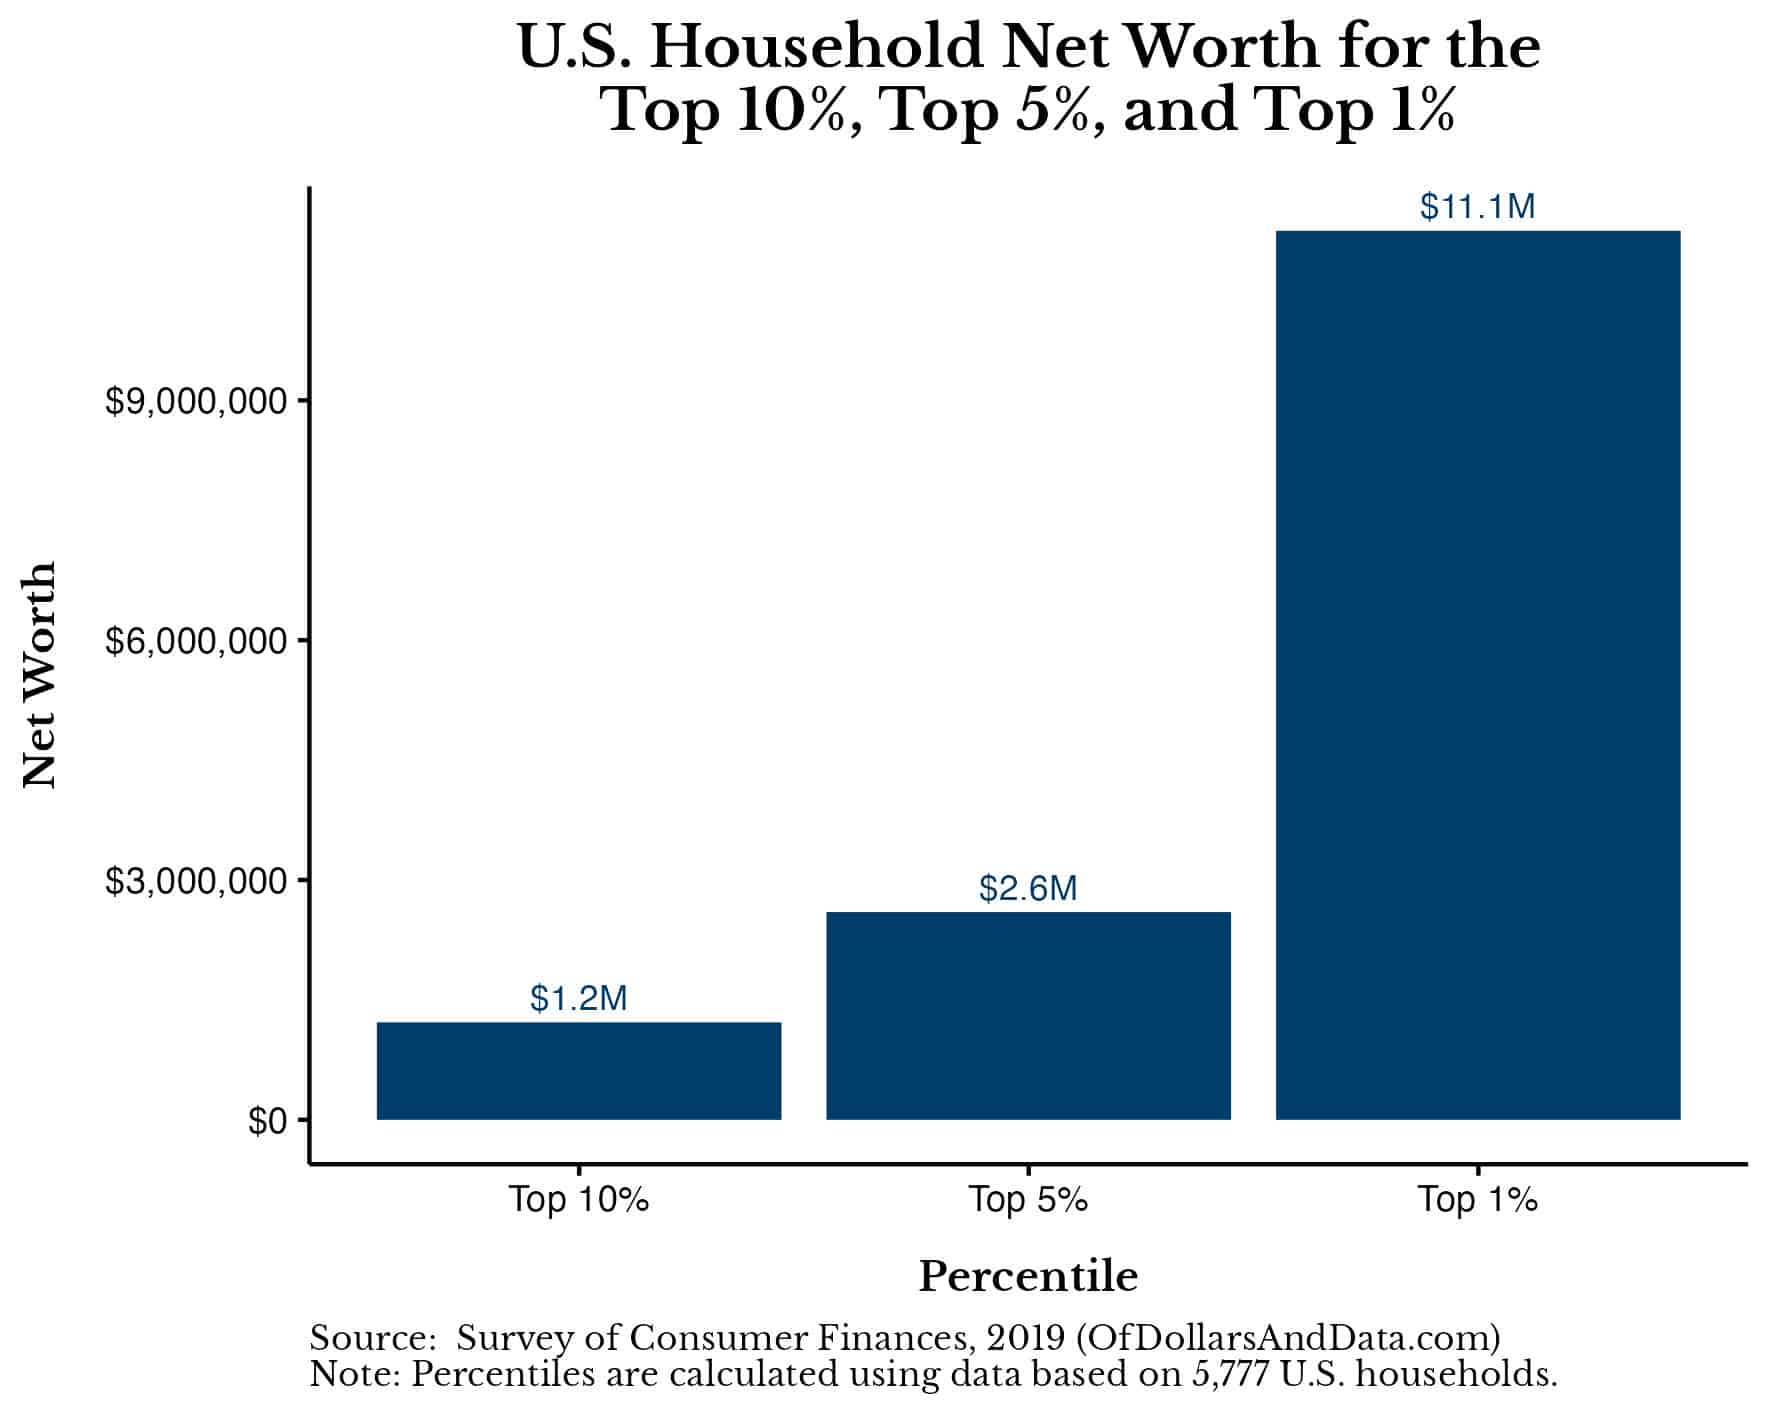
The global conversation around "how much net worth do I need to be in the top 1%" has intensified as wealth inequality becomes a political and social flashpoint. In 2022, Oxfam estimated that the world’s billionaires collectively held $4.3 trillion—enough to lift global poverty rates by 99% if redistributed. Yet the top 1% isn’t just the billionaire class; it’s a broader cohort where median net worth in the U.S. sits at $10.1 million, according to Federal Reserve data. This isn’t about luxury yachts or private jets—it’s about the structural advantages that come with asset ownership, tax deferral strategies, and access to exclusive investment vehicles. The threshold varies sharply by country. In China, the top 1% net worth starts at ¥10 million (~$1.4 million), reflecting a younger, tech-driven economy where wealth is concentrated in urban property and equity stakes. Meanwhile, in Sweden, the bar is $2.1 million, partly due to progressive taxation that discourages extreme wealth hoarding. Even within the U.S., the figure fluctuates by state: California’s top 1% begins at $15 million, while in Mississippi, it’s closer to $3.2 million. The key takeaway? How much net worth do I need to be in the top 1% isn’t a universal constant—it’s a moving target shaped by local economics and policy.Historical Background and Evolution
The modern obsession with "how much net worth do I need to be in the top 1%" traces back to the 1980s, when economists like Thomas Piketty began quantifying wealth concentration. His research revealed that pre-World War II, the top 1% in Western nations held 50–60% of all wealth—a figure that plunged after progressive taxation but began creeping back up in the 1980s Reagan-Thatcher era. The 1990s tech boom accelerated the trend, as stock options and IPO windfalls created a new class of self-made millionaires. By 2000, the U.S. top 1% net worth threshold had ballooned to $8 million, adjusted for inflation. The 2008 financial crisis temporarily stalled this growth, but the recovery—fueled by quantitative easing and asset price inflation—pushed the bar higher. Today, how much net worth do I need to be in the top 1% is not just about income but about asset accumulation. The richest 1% now derive 20% of their wealth from labor income and 80% from capital gains, real estate, and business ownership. This shift explains why a $500,000 salary might not get you there—unless you’re also investing aggressively in private equity, crypto, or commercial real estate.Core Mechanisms: How It Works
The answer to "how much net worth do I need to be in the top 1%" isn’t just about hitting a number—it’s about how that wealth is structured. Take tax-efficient vehicles: A U.S. taxpayer with $10 million in cash faces $2.5 million in capital gains taxes if sold, but if that wealth is held in a family limited partnership or LLC, taxes can be deferred indefinitely. Similarly, real estate plays—like 1031 exchanges—allow top earners to shelter millions in appreciated value from taxation. Another critical factor is liquidity. The top 1% don’t just have $10 million—they have $10 million in assets that can be deployed instantly. This includes private equity stakes, hedge funds, or illiquid venture capital. A $10 million cash balance might not qualify you for the top 0.1%, but $10 million in a mix of stocks, real estate, and business equity often does. The system is designed so that how much net worth do I need to be in the top 1% isn’t just about the total—it’s about how it’s packaged for growth and tax avoidance.Key Benefits and Crucial Impact
The privileges tied to "how much net worth do I need to be in the top 1%" extend beyond financial freedom. Access to elite education—like sending kids to Andover or Eton—creates a feedback loop of opportunity. A 2021 Brookings study found that children of top 1% parents earn 30% more by age 30, even with identical qualifications. Political influence is another lever: The top 0.1% donate 75% of all political campaign funds in the U.S., shaping policy that benefits asset holders. The psychological impact is equally stark. Top 1% individuals report lower stress levels despite higher public scrutiny—a paradox explained by control over their financial narrative. They can self-insure against market crashes by diversifying into gold, art, or farmland, while the middle class remains vulnerable to single-income shocks. > "Wealth isn’t just money—it’s the ability to say 'no' to things that don’t align with your vision. That’s the real power of the top 1%." — James Altucher, entrepreneur and investorMajor Advantages
- Tax optimization: Access to offshore accounts, trust structures, and charitable deductions that slash effective tax rates below 15%.
- Asset protection: Ability to shield wealth from lawsuits, creditors, or divorce settlements via LLCs and irrevocable trusts.
- Exclusive investment access: Private equity funds, angel networks, and sovereign wealth partnerships closed to retail investors.
- Generational transfer: Dynasty trusts and gifting strategies allow wealth to skip estate taxes entirely.
- Lifestyle immunity: Private healthcare, concierge doctors, and risk management that insulates against systemic failures.
- Network leverage: Board seats, high-net-worth clubs, and VIP event access that accelerate business and social capital.
Comparative Analysis
| Metric | U.S. (Top 1%) | Germany (Top 1%) |
|---|---|---|
| Net Worth Threshold | $10–$12 million | €2.5–€3 million (~$2.7M) |
| Primary Wealth Sources | Tech stocks, real estate, private equity | Industrial holdings, family businesses, DAX stocks |
| Tax Rate on Capital Gains | 20% (long-term) | 25% (plus solidarity surcharge) |
Future Trends and Innovations
The next decade will redefine "how much net worth do I need to be in the top 1%" through AI-driven asset management and tokenized ownership. Platforms like Coinbase Prime and Securitize are already allowing fractional ownership of $100M+ assets—meaning a $500,000 investment could get you a stake in a private jet or vineyard. Simultaneously, central bank digital currencies (CBDCs) could erode cash-based wealth, forcing top earners to adopt crypto or alternative reserves. Another wildcard: automation and AI. If 30% of jobs are replaced by AI by 2030, the top 1% will own the robots—while the middle class struggles. This could raise the threshold further, as how much net worth do I need to be in the top 1% becomes tied to ownership of intellectual property and automation infrastructure.
Conclusion
The question "how much net worth do I need to be in the top 1%" isn’t just mathematical—it’s a cultural and systemic puzzle. The numbers shift with inflation, policy, and technological disruption, but the real barrier isn’t the dollar amount—it’s the playbook. Most people never learn how to structure wealth for growth, protect it from erosion, or leverage it for influence. That’s why 90% of millionaires never join the top 1%—not because they lack money, but because they lack the strategic mindset. The good news? The rules are knowable. Study tax-efficient real estate, private equity syndications, and dynasty trust structures—and you’ll find that how much net worth do I need to be in the top 1% is less about luck and more about mastering the hidden levers of wealth preservation.Comprehensive FAQs
Q: Is the top 1% net worth threshold higher for singles or couples?
The threshold is per household, not per individual. A married couple in the U.S. needs $10–$12 million combined, while a single person might need $15–$20 million to account for lower asset diversification and higher tax brackets. In some countries like Sweden, the threshold is lower for couples due to marital wealth pooling laws.
Q: Can I reach the top 1% with a high salary but no investments?
Unlikely. A $500,000 salary might get you to $5–$10 million in 20–30 years if saved aggressively, but how much net worth do I need to be in the top 1% requires asset appreciation. Without investments in stocks, real estate, or a business, you’ll max out at top 5% territory—where wealth is still liquid and taxable. The top 1% own assets that grow faster than inflation.
Q: Does inheriting wealth count toward the top 1% threshold?
Yes, but how it’s structured matters. A $10 million inheritance in cash may not qualify you if it’s taxed heavily, but if it’s held in a family trust or LLC, it can preserve and grow toward top 1% status. 60% of U.S. top 1% wealth comes from inheritance or gifting, per the Federal Reserve’s SCF data. The key is avoiding probate and capital gains taxes through legal entity structuring.
Q: Are there countries where the top 1% threshold is lower than $1 million?
Yes, but they’re exceptions. In Brazil, the top 1% starts at ~$800,000, while in South Africa, it’s ~$500,000—but these economies have high inflation and weak currency, distorting real purchasing power. In stable economies like Japan or Switzerland, the bar remains above $2 million. If you’re asking "how much net worth do I need to be in the top 1%" in a high-cost city like London or San Francisco, expect $5–$10 million due to real estate and living expenses.
Q: What’s the fastest way to cross into the top 1%?
Acquire illiquid, high-appreciation assets. The top strategies:
- Found or join a high-growth startup (e.g., acquired for $100M+).
- Invest in private equity or venture capital (returns of 20–30% annually).
- Buy undervalued commercial real estate in sunrise markets (e.g., Austin, Dallas).
- Leverage real estate syndications (pool capital with others for $5M+ deals).
- Monetize intellectual property (patents, royalties, or digital assets like NFTs).
