
5 Things Worth Knowing About the Estimated Median
The estimated median isn’t just a statistical footnote; it’s the backbone of fair comparisons. Here’s why it consistently outperforms other measures—and where it still falls short.1. It Resists Skewed Data Better Than the Mean
The mean is vulnerable to outliers. In a neighborhood where four homes are worth £500,000 and one is worth £5 million, the average price inflates to £1.25 million—useless for most buyers. The estimated median, however, would likely land around £500,000, reflecting the actual cost of entry for the majority. This resistance to distortion is why real estate listings increasingly pair mean prices with median figures, acknowledging that the latter tells a truer story about market accessibility. Financial planners use a similar logic when advising clients. A portfolio’s average annual return might be 12% if one year delivered a 50% gain, but the estimated median return—what most years actually deliver—could be closer to 7%. The difference isn’t trivial; it’s the gap between a client who plans for stability and one who gambles on volatility.2. It’s the Gold Standard for Income Inequality Metrics
When discussing wage stagnation, the estimated median is non-negotiable. The mean household income in the UK rose by 3.1% in 2022, but the median grew by just 1.8%. The discrepancy? A handful of top earners—CEOs, tech founders, or hedge fund managers—pulled the average upward while middle-class wages inched forward. Median figures, by contrast, show that the typical worker’s paycheck hasn’t kept pace with inflation for over a decade. This matters in political debates. Proponents of progressive taxation argue that median incomes have flatlined, justifying higher rates on the ultra-wealthy. Critics counter that mean income growth proves the economy is thriving. The estimated median forces a reckoning: if the middle isn’t rising, no amount of top-line growth changes that fact.3. It’s Often Misused in Political and Corporate Narratives
Corporations and policymakers exploit the ambiguity between mean and median. A company might boast that its "average" employee salary is £60,000, when the estimated median is £42,000—hiding the fact that most workers earn far less. Similarly, governments have been accused of cherry-picking mean figures to suggest economic recovery, while median metrics paint a grimmer picture of recovery lagging for the majority."The mean is a monster that devours its own children—it consumes the truth with every outlier it includes." — Nassim Nicholas Taleb, AntifragileThis tactic isn’t limited to bad actors. Even well-intentioned reports can mislead. A 2021 OECD study on post-pandemic recovery used mean GDP growth rates, obscuring regional disparities where median household incomes in depressed areas had barely moved. The lesson? Always ask whether a statistic is based on the mean or the estimated median before drawing conclusions.
4. It’s Critical for Risk Assessment in Finance
Investors and insurers rely on the estimated median to model risk. Actuaries calculating life insurance premiums don’t use the mean life expectancy—they use the median, because extreme outliers (like someone living to 120) would skew the average dangerously. Similarly, banks assessing mortgage applications look at median debt-to-income ratios in a region, not the mean, to avoid overleveraging. The estimated median also explains why some financial products seem unaffordable to most people. A "typical" credit score might be reported as 720 (mean), but the estimated median could be 680—meaning half the population faces higher interest rates. This gap is why subprime lending crises often catch regulators off guard: they’re monitoring averages, not medians.5. It’s Underrated in Healthcare and Education Metrics
Healthcare spending is another domain where the estimated median reveals harsh truths. The mean cost of a hospital stay in the US is often cited as $15,000, but the median is closer to $8,000—because a small number of ultra-expensive cases (e.g., rare surgeries or long-term care) drag the average upward. Patients and insurers operate in the median world, not the mean. Education statistics suffer the same issue. The mean student loan debt might be $35,000, but the estimated median is often $20,000—meaning half of borrowers owe less, while the other half are crushed by higher balances. This distinction is why loan forgiveness debates focus on median debt levels: it’s the figure that determines whether policies actually help the majority.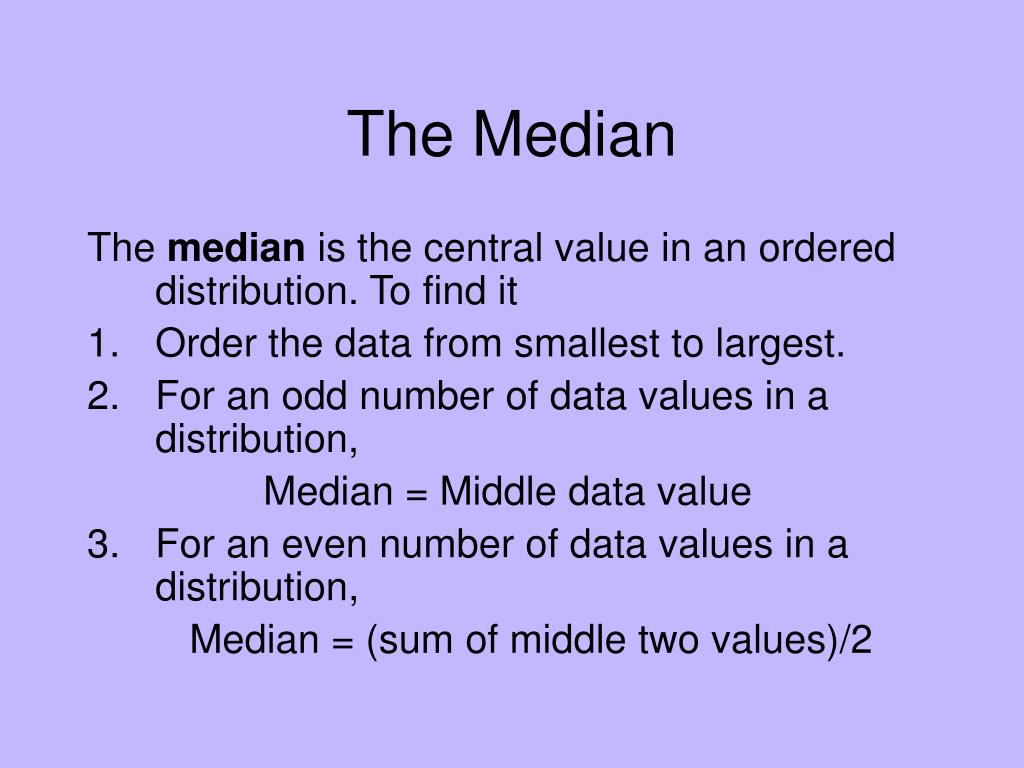
How These Facts Connect
The estimated median isn’t just a statistical curiosity; it’s a lens that reframes how we see fairness, risk, and progress. Whether in wages, housing, or finance, it exposes the hidden assumptions behind "average" claims. The mean tells us about extremes; the median tells us about the experience of the majority. This isn’t just semantics—it’s the difference between policies that lift all boats and those that only float the few at the top. The table below contrasts how mean and median figures interact across key domains:| Domain | Mean Distorts Because... | Median Reveals... |
|---|---|---|
| Income | Top 1% earnings inflate averages | Stagnant middle-class wages |
| Housing | Luxury sales skew price data | Actual affordability thresholds |
| Education | Extreme debt cases pull up averages | Typical borrower burden |
| Healthcare | Outlier treatments inflate costs | Real patient out-of-pocket expenses |
| Risk Modeling | Extreme events skew probabilities | Likely outcomes for most cases |
Conclusion
The estimated median is the unsung hero of data analysis—a measure that grounds abstract numbers in reality. It’s why housing markets are priced for the masses, not the elite; why wage growth debates hinge on what’s typical, not exceptional; and why financial products are designed for the median consumer, not the mean outlier. Ignoring this distinction isn’t just a statistical error; it’s a failure to account for how most people actually live. The next time you see a headline about "average" earnings, home prices, or economic growth, ask: Is this the mean, or the estimated median? The answer could change how you see opportunity—or the lack of it.Comprehensive FAQs
Q: Why do people confuse mean and median so often?
The terms sound similar, and both are called "averages" in casual conversation. Media outlets often use "average" without specifying which measure they’re citing, reinforcing the confusion. Additionally, the mean is more intuitive for small, symmetric datasets, while the median’s utility becomes apparent only when outliers dominate.
Q: Can the estimated median be manipulated?
Yes, but differently than the mean. Instead of adding extreme values, manipulators can exclude data points, use non-representative samples, or cherry-pick time periods. For example, a report might calculate median wages over a decade of high growth, ignoring the preceding stagnant years. Always check the methodology behind median figures.
Q: Is the estimated median always better than the mean?
Not necessarily. In symmetric distributions (like bell curves), the mean and median are nearly identical. The median also struggles with bimodal data—where two distinct groups exist (e.g., part-time vs. full-time workers). Context matters: use the mean for symmetric data, the median for skewed data, and consider both for a full picture.
Q: How do I know if a statistic is using the mean or median?
Look for qualifiers like "average" (often mean), "middle value" (median), or "50th percentile" (another term for median). Reputable sources will specify. If unsure, ask: Does this number make sense given what most people experience? If not, it’s likely the mean.
Q: Why do governments prefer mean figures in economic reports?
Mean figures can make growth appear stronger by including high earners or outliers. For instance, a country with a few billionaires will have a higher mean GDP per capita than one without, even if median incomes are similar. Governments aren’t always malicious—sometimes it’s inertia or a misunderstanding of which metric serves the public best.
Q: Can the estimated median be used for predictive modeling?
Yes, but with caveats. Medians are excellent for forecasting likely outcomes in skewed distributions (e.g., home prices, insurance claims). However, they’re less useful for modeling extremes or tail risks. Hybrid approaches—combining median trends with mean-based outlier analysis—often yield the most robust predictions.
Q: How does the estimated median apply to non-numeric data?
The concept extends beyond numbers. In surveys, the "median response" (the middle answer in ordered data) can reveal consensus where the mean might be misleading. For example, if most people rate a product as "good" but a few rate it as "excellent," the median captures the typical sentiment better than the mean score.
Q: What’s the most common mistake when interpreting the estimated median?
Assuming it represents the "typical" experience without accounting for distribution shape. A median income of £30,000 could mean half earn less—but if the other half earn £35,000, the gap is smaller than if half earn £10,000 and the other half £50,000. Always pair the median with a sense of spread (e.g., interquartile range).
