
The Short Answers
- The average Black family net worth during Jim Crow was estimated at less than $1,000 (adjusted for inflation, roughly $12,000 today), compared to white families’ $10,000+.
- Wealth destruction stemmed from land theft, convict leasing, and exclusion from New Deal programs, not individual failure.
- Black-owned businesses and farms were targeted for destruction—lynchings, arson, and legal harassment wiped out entire economic ecosystems.
- Even in urban areas, redlining and discriminatory lending prevented Black families from building home equity, a primary wealth vehicle for whites.
- The generational trauma of Jim Crow explains why, by 1990, the median white family had 10 times the wealth of the median Black family.

Deep Dive: The Full Picture
The average Black family net worth during Jim Crow wasn’t just a reflection of economic conditions—it was a direct result of state-sanctioned theft. After Reconstruction, Black families in the South had begun rebuilding through land ownership, entrepreneurship, and savings. The Freedmen’s Bureau and early Black institutions like Hampton Institute provided education and capital, but these gains were systematically undone. By the 1890s, Black farmers—who had owned nearly 16 million acres post-Civil War—lost 90% of that land to fraud, violence, and legal loopholes like the Homestead Act’s exclusion of Black tenants. The average Black family net worth during Jim Crow collapsed as land became the primary vehicle for wealth transfer, and Black families were locked out.
Northern Black families fared slightly better but still faced de facto segregation in housing, employment, and banking. In cities like Chicago and New York, Black neighborhoods were redlined, meaning banks refused mortgages there, forcing families into rental traps. Meanwhile, white families accessed FHA loans at 4% interest to buy homes, while Black families were charged double or triple—if they could get a loan at all. The average Black family net worth during Jim Crow in urban areas was often tied to informal economies (barber shops, laundries, music) because formal financial systems excluded them. Even then, lynchings and bombings (like the 1921 Tulsa Race Massacre, where Black Greenwood District businesses were burned) wiped out entire business districts overnight.
The Context You Need
Jim Crow wasn’t just about separate water fountains—it was a financial apartheid. The 13th Amendment’s loophole (allowing "punishment for crime" as slavery) led to convict leasing, where Black men were arrested on trumped-up charges, sold to plantations, and worked to death. Families lost breadwinners, and the average Black family net worth during Jim Crow was further gutted by debt peonage. Meanwhile, the New Deal’s Agricultural Adjustment Act paid white farmers to destroy crops, while Black tenant farmers—who owned no land—were left starving. The Social Security Act of 1935 excluded 60% of Black workers (domestic and agricultural laborers), ensuring they had no safety net.
Black institutions like Black churches and fraternal orders (e.g., Masons, Odd Fellows) became the only stable financial anchors, offering life insurance, credit unions, and burial societies. But these were no match for systemic erosion. When the Great Migration began in the 1940s, Black families moved north hoping for better wages—but discriminatory housing covenants and employment barriers meant they still couldn’t accumulate wealth. The average Black family net worth during Jim Crow remained stagnant because the rules of the game were stacked against them at every turn.
The Mechanics
The mechanics of wealth destruction were threefold: exclusion, extraction, and exploitation. First, exclusion—Black families were barred from FHA loans, VA mortgages, and union jobs, the primary wealth-building tools for whites. Second, extraction—poll taxes, literacy tests, and property taxes (often inflated) made it impossible to save. Third, exploitation—sharecropping contracts kept families in cycles of debt, while predatory lenders charged usurious rates for basic necessities.
Consider Black-owned farms in the South. In 1910, Black farmers owned 14 million acres; by 1960, that number had plummeted to 3 million. The average Black family net worth during Jim Crow in rural areas was often negative—debts outweighed assets. Urban Black families fared slightly better but still faced rent gouging in segregated neighborhoods. Even Black entrepreneurs—like Madam C.J. Walker or Booker T. Washington’s Tuskegee Institute—operated in an economy where capital was hoarded by whites. The average Black family net worth during Jim Crow was a fraction of white families’ because the system was designed to prevent accumulation.
Details That Change the Picture
The average Black family net worth during Jim Crow wasn’t just low—it was actively sabotaged. Take Tuskegee, Alabama, where Booker T. Washington built an economic empire. By 1915, Tuskegee’s Black-owned businesses employed hundreds, and the average Black family net worth there was higher than the Southern average. But when white supremacists burned down the Black business district in 1906, they didn’t just destroy property—they erased a generation of wealth. Similar patterns played out in Black Wall Street (Tulsa), Bronxville (NY), and Beale Street (Memphis). Each time, white mobs or legal harassment ensured the average Black family net worth couldn’t recover.
Another critical factor was inheritance. White families passed down land, stocks, and businesses for generations, compounding wealth. Black families, however, were disproportionately barred from inheritance due to will challenges, forced sales, and violence. Even when Black families did inherit, discriminatory property taxes or racist appraisers undervalued their assets. The average Black family net worth during Jim Crow was stunted not by laziness, but by a legal system that ensured they could never catch up.
"The Negro’s economic progress has been retarded by the deliberate policy of keeping him in a state of economic dependence." — W.E.B. Du Bois, Black Reconstruction in America (1935)
| Wealth Vehicle | Impact on Black Families |
|---|---|
| Land Ownership | Lost 90% of post-Civil War acres due to fraud, violence, and legal loopholes. |
| Homeownership | Denied FHA/VA loans; forced into rental traps in redlined neighborhoods. |
| Business Ownership | Lynchings, bombings, and legal harassment destroyed entire commercial districts. |
| Inheritance | Will challenges, forced sales, and violence blocked wealth transfer. |
Conclusion
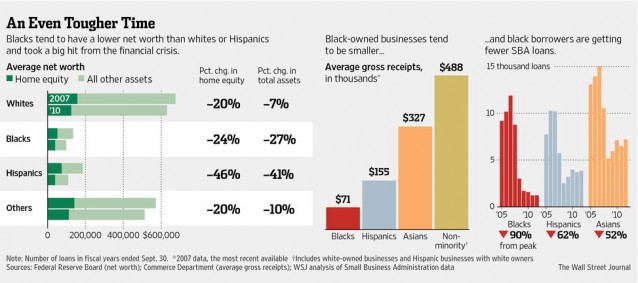
The average Black family net worth during Jim Crow wasn’t a natural outcome—it was the result of a 90-year campaign to keep Black families poor. The policies that shaped it—convict leasing, redlining, land theft—weren’t anomalies; they were the rules. Even today, the racial wealth gap (where the median white family has 10 times the wealth of the median Black family) is a direct legacy of these eras. Understanding this history isn’t about assigning blame; it’s about recognizing the structural forces that have shaped economic inequality.
The average Black family net worth during Jim Crow tells us that wealth isn’t just about hard work—it’s about access. When that access is denied for generations, the effects linger. The fight for reparations, equitable lending, and wealth-building policies isn’t just about the past—it’s about correcting a system that never let Black families play by the same rules.
Comprehensive FAQs
#### Q: How did convict leasing destroy Black wealth?
Convict leasing (1865–1928) trapped Black men in debt peonage—arrested on false charges, "leased" to plantations, and worked to death. Families lost breadwinners, and wages (if any) went to "employers," not homes or savings. This cyclical poverty ensured the average Black family net worth during Jim Crow stayed near zero.
####Q: Were there any Black families who built wealth under Jim Crow?
Yes, but they were exceptions in a rigged system. Figures like Madam C.J. Walker (cosmetics), A. Philip Randolph (labor organizing), and the Green family (Tuskegee Institute) accumulated wealth—but their success was fragile. Lynchings, economic boycotts, and legal harassment (e.g., NAACP bombings) ensured most couldn’t replicate their achievements.
####Q: How did redlining affect Black homeownership?
Redlining (1930s–1960s) denied Black families mortgages in white neighborhoods, forcing them into high-rent, high-crime areas. White families used FHA loans (4% interest) to buy homes; Black families paid 10–20% interest for substandard housing. This prevented home equity—the #1 wealth-builder for white families—from ever accumulating in Black households.
####Q: Did Black churches or fraternal orders help preserve wealth?
Yes, but only as a stopgap. Organizations like Black Masons, Odd Fellows, and churches offered life insurance, credit unions, and burial societies—critical in a system that excluded them from banks. However, lynchings, arson, and legal harassment (e.g., tax audits targeting Black institutions) limited their impact. The average Black family net worth during Jim Crow still relied on informal networks, not systemic change.
####Q: How does this history explain today’s wealth gap?
The $10-to-$1 ratio in median white vs. Black wealth today traces back to Jim Crow’s wealth destruction. White families inherited land, stocks, and businesses; Black families were locked out of those vehicles. Even New Deal programs (Social Security, FHA loans) excluded Black workers, ensuring the gap widened further. Without reparations or policy fixes, the average Black family net worth remains centuries behind.
####Q: Are there any modern policies addressing this?
Some efforts exist but are insufficient. The 2021 House reparations study acknowledged the average Black family net worth during Jim Crow as a direct result of theft, but no federal reparations have passed. Baby bonds (proposed in 2021) would give Black children $50K at birth to invest—modeled after white families’ inherited wealth. However, lobbying and political resistance have stalled progress.
