
Common Myths About Nikola Tesla’s Wealth
The most enduring myth about what was Nikola Tesla’s net worth is that he died broke, a forgotten genius in a cheap hotel room. This narrative, popularized in biographies and films, paints Tesla as a tragic figure whose ideas were stolen by corporate interests—most notably, Thomas Edison and George Westinghouse. The reality is more nuanced. While Tesla’s later years were marked by financial struggles, his death in 1943 was not the result of absolute poverty. His estate, however, was a legal mess, and the U.S. government’s seizure of his papers and inventions during World War II only deepened the confusion. The myth persists because it aligns with the romanticized image of the lone inventor fighting against the machine—a story that sells far better than the messy truth of unpaid bills and disputed royalties. Another persistent claim is that Tesla’s patents were worth a fortune, and that his death left behind a hidden treasure trove of wealth. This idea gains traction whenever a new documentary or article speculates about how much Tesla was worth at his peak. In truth, while Tesla held hundreds of patents—over 300 by some counts—many were either sold, licensed, or tied up in legal disputes. His most lucrative deal, the agreement with Westinghouse Electric in 1895, reportedly earned him $2.5 million (equivalent to tens of millions today), but the terms were complex, and he later accused Westinghouse of reneging on payments. By the time of his death, his patents had long since expired or been diluted by corporate takeovers. The notion that his intellectual property was a goldmine ignores the fact that innovation in the early 20th century was a collaborative, often contentious process—one where individual inventors rarely retained full control. A third myth suggests that Tesla’s personal wealth was squandered on extravagant projects, like his ill-fated Wardenclyffe Tower, which was meant to transmit wireless energy globally. While it’s true that Tesla poured time and resources into Wardenclyffe, the project was never a personal indulgence but rather a visionary (and ultimately unfeasible) attempt to democratize energy. By the time he began construction in 1901, his financial backers had already withdrawn support, leaving him to fund the endeavor through loans and personal savings. The tower’s failure didn’t stem from reckless spending but from a combination of technological limitations and the lack of a viable business model. This myth overlooks the fact that Tesla’s financial decisions were often strategic gambles—ones that reflected his long-term thinking rather than frivolity.Myth 1: Tesla died penniless in a New York hotel room
The image of Tesla as a destitute recluse in the Chelsea Hotel is one of the most persistent in popular culture. It’s a powerful narrative: the genius, unappreciated in his lifetime, reduced to subsisting on three meals a day at the hotel’s restaurant. While it’s true that Tesla spent his final years in the hotel—arriving in 1923 and remaining until his death in 1943—his financial situation was not as dire as often portrayed. Court records and biographical accounts indicate that Tesla maintained a modest but stable income from royalties, consulting work, and occasional lectures. His monthly expenses were covered by a combination of personal savings, advances from publishers, and occasional payments from former associates. What the myth obscures is the legal and financial complexity of Tesla’s later years. His estate, when settled in 1943, was valued at around $75,000 (equivalent to roughly $1.3 million today), but this figure included debts, unpaid taxes, and assets that were either seized or disputed. The U.S. government, fearing that Tesla’s research could aid enemy powers, confiscated his papers and inventions under the Alien Property Custodian Act. This seizure left his estate in limbo, with many of his personal belongings and financial records lost or destroyed. The idea that he died with nothing ignores the fact that his intellectual property—though no longer generating significant revenue—still held residual value. His death certificate listed his estate as worth $150,000, but this was a snapshot of a frozen, contested asset base.Myth 2: His patents made him a multimillionaire
The assumption that Tesla’s patents alone would have made him one of the richest men of his era is a common oversimplification. While Tesla held over 300 patents by the time of his death, the majority were either sold, licensed, or rendered obsolete by the time they could be monetized. His most significant financial windfall came from his work with Westinghouse Electric, where he designed the alternating current (AC) induction motor—a breakthrough that won him the 1895 contract. However, the terms of his agreement were not as lucrative as often claimed. Tesla reportedly received $2.5 million upfront (a staggering sum at the time), but the payments were structured as a mix of salary, royalties, and stock options, many of which were never fully realized. By the early 1900s, Tesla’s financial situation had deteriorated. His royalties from Westinghouse dried up after a dispute over unpaid bonuses, and his attempts to commercialize new inventions—such as the Tesla coil and wireless transmission technology—failed to generate sustained income. The myth that his patents were a goldmine ignores the reality of patent law in the late 19th and early 20th centuries. Most inventors of the era did not retain full ownership of their patents; instead, they licensed them to corporations in exchange for lump sums or ongoing royalties. Tesla’s case was no exception. His later patents, such as those related to radio technology, were challenged in court, and he lost the landmark Tesla vs. Marconi case in 1943—a decision that further eroded his financial standing. The truth is that while his patents had immense theoretical value, their commercial potential was often limited by the business models of the time.Myth 3: His wealth was stolen by Edison or Westinghouse
The narrative that Tesla’s wealth was systematically stolen by corporate titans like Thomas Edison or George Westinghouse is a cornerstone of the "Tesla as victim" mythos. While it’s true that Tesla had bitter rivalries with both men—particularly Edison, who famously offered him a $50,000 bonus for improving DC generators only to renege—Tesla’s financial struggles were not solely the result of corporate theft. Edison’s betrayal was undeniable, but Westinghouse’s relationship with Tesla was far more complex. The two men had a genuine partnership, and while Tesla later accused Westinghouse of reneging on payments, the evidence suggests that the breakdown was mutual. Westinghouse had invested heavily in Tesla’s AC technology, but as the market shifted, the company prioritized other ventures, leaving Tesla with unpaid royalties. What the myth overlooks is that Tesla’s financial mismanagement played a role in his downfall. He was notoriously poor at negotiating contracts, often accepting lump-sum payments in exchange for long-term royalties that never materialized. His refusal to secure legal protections for his inventions—such as proper patent assignments—left him vulnerable to legal challenges and corporate takeovers. By the time of his death, many of his most valuable patents had expired or been absorbed into corporate portfolios. The idea that his wealth was stolen ignores the fact that Tesla’s financial decisions were often driven by his visionary (and sometimes impractical) ideas about technology and its societal impact. He prioritized innovation over profit, a choice that left him financially exposed but intellectually uncompromised.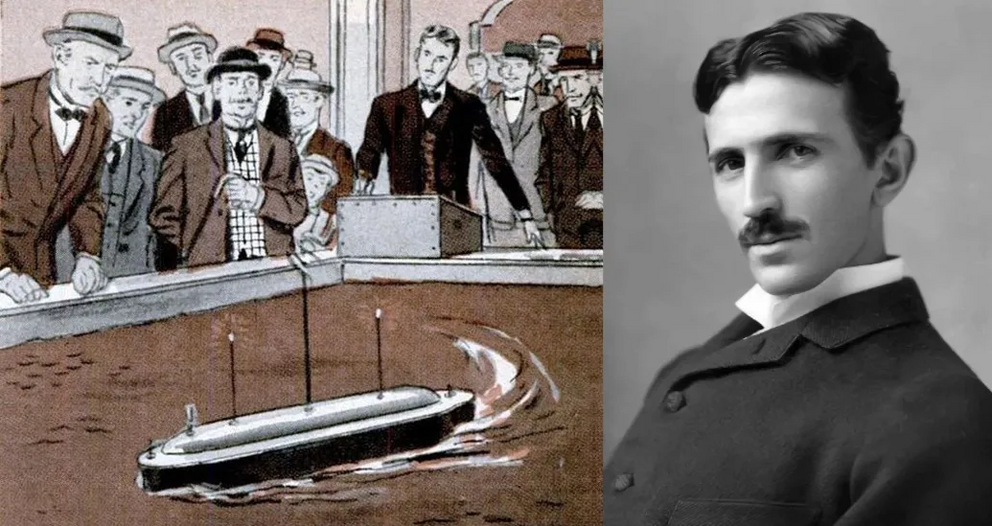
What Holds Up to Scrutiny
At the core of the debate over what was Nikola Tesla’s net worth are a few verifiable facts. First, Tesla was never destitute in the strictest sense. His estate, though modest by modern standards, included assets beyond his personal belongings. Second, his financial struggles were not the result of a single betrayal but a combination of market forces, legal battles, and his own unconventional approach to business. Third, the most accurate estimate of his net worth at death—between $75,000 and $150,000—reflects a man who was neither a billionaire nor a pauper, but rather a figure whose value was tied to his ideas rather than his bank account. The key to understanding Tesla’s financial legacy lies in his relationship with patents and corporations. Unlike inventors who sought to monetize their work through direct sales or licensing, Tesla often sold his patents outright, believing that his ideas would benefit humanity regardless of who controlled them. This philosophy left him with little residual income from his inventions. His later years were marked by a series of failed attempts to revive his financial fortunes, including a 1937 offer to the U.S. government to build a "death ray" weapon—an offer that went unfulfilled. The government’s subsequent seizure of his papers and inventions in 1943 further complicated his estate, leaving his financial records fragmented and open to interpretation."Money is not the measure of success. The number of friends you have, the number of people who like you, the number of people you’ve helped—that’s the measure of success." —Nikola Tesla, as quoted in Man Out of Time by Marc J. SeiferThe table below compares common beliefs about Tesla’s wealth with what the historical evidence suggests:
| Common Belief | What the Evidence Says |
|---|---|
| Tesla died penniless. | His estate was valued at $75,000–$150,000, but debts and legal disputes reduced liquid assets. |
| His patents made him a multimillionaire. | Most patents were sold or licensed; royalties were inconsistent and often unpaid. |
| Edison and Westinghouse stole his wealth. | Financial struggles stemmed from market forces, legal battles, and Tesla’s own business decisions. |
| Wardenclyffe Tower was a financial drain. | Funding came from loans and personal savings; the project was abandoned due to lack of backers, not overspending. |
| His later years were marked by extreme poverty. | He maintained a stable but modest income from royalties and consulting until his death. |
Why the Confusion Persists
The enduring confusion over what was Nikola Tesla’s net worth stems from a combination of historical obfuscation and modern mythmaking. During Tesla’s lifetime, financial records were not as transparent as they are today. Patents were often traded as assets rather than licensed for revenue, and corporate dealings were conducted in private. When Tesla died, his estate was immediately embroiled in legal disputes, with the U.S. government seizing his papers and inventions. Many of his personal financial documents were lost or destroyed, leaving gaps that later biographers and historians have struggled to fill. The result is a financial legacy that is as much about what was not recorded as what was. The rise of Tesla’s cult-like status in the late 20th and early 21st centuries has further muddied the waters. Pop culture has romanticized Tesla as a misunderstood genius, a narrative that aligns with the "inventor as victim" trope. Documentaries, books, and even Hollywood films have amplified the myth of the penniless eccentric, while financial speculators have occasionally revived claims of hidden wealth tied to his patents. The truth is that Tesla’s financial story is not one of a single, clear narrative but of a series of interconnected factors: his revolutionary ideas, his unconventional business practices, and the shifting tides of corporate power. The confusion persists because the story of Tesla’s wealth is not just about money—it’s about the intersection of innovation, capitalism, and the way history remembers its most brilliant but flawed figures.
Conclusion
The question of what was Nikola Tesla’s net worth cannot be answered with a single number. Tesla’s financial life was as dynamic as his inventions, marked by periods of prosperity, legal battles, and quiet desperation. He was neither the penniless recluse of legend nor the corporate tycoon that some speculative claims suggest. Instead, he was a man whose genius outpaced his ability to monetize it—a reality that reflects the challenges faced by many inventors of his era. His estate’s value at death, while modest by today’s standards, was not insignificant, but it was also a fraction of what his ideas were worth in theory. What Tesla’s financial story ultimately reveals is the fragility of individual wealth in the face of corporate power and market forces. His patents, once revolutionary, became commodities in a system that valued control over innovation. His personal finances were a reflection of his priorities: he invested in ideas, not in the mechanisms of capitalism. In the end, the true measure of Tesla’s legacy lies not in his bank account but in the way his work continues to shape the world—from wireless technology to renewable energy. The myth of the penniless genius may be compelling, but the reality is far more interesting: a man who redefined what it meant to be an inventor, even if the ledgers never fully reflected his brilliance.Comprehensive FAQs
Q: Did Nikola Tesla die broke?
A: No. While Tesla’s later years were marked by financial struggles, he did not die in absolute poverty. His estate was valued at around $75,000–$150,000 at the time of his death (equivalent to roughly $1.3–$2.5 million today), though debts and legal disputes reduced his liquid assets. The myth of his destitution stems from his reclusive lifestyle and the loss of many financial records during the settlement of his estate.
Q: How much money did Tesla make from his patents?
A: Tesla’s patents generated income, but the amounts were inconsistent and often tied to lump-sum payments rather than ongoing royalties. His most significant financial windfall came from his work with Westinghouse Electric in the 1890s, where he reportedly received $2.5 million (equivalent to tens of millions today) for his AC induction motor. However, many of his later patents were either sold outright or tied up in legal disputes, limiting their financial return.
Q: Was Tesla’s wealth stolen by Edison or Westinghouse?
A: While Tesla had bitter rivalries with both Edison and Westinghouse, his financial struggles were not solely the result of corporate theft. Edison did reneged on a promised bonus, but Westinghouse’s relationship with Tesla was more complex. Tesla’s financial difficulties were also due to his own business decisions, such as accepting lump-sum payments in exchange for long-term royalties that were never fully realized.
Q: What happened to Tesla’s financial records after his death?
A: After Tesla’s death in 1943, his estate was immediately embroiled in legal disputes. The U.S. government seized his papers and inventions under the Alien Property Custodian Act, and many of his personal financial documents were lost or destroyed. This has left gaps in the historical record, contributing to the confusion surrounding what was Nikola Tesla’s net worth at the time of his death.
Q: Did Tesla leave behind any hidden wealth?
A: There is no verifiable evidence that Tesla left behind a hidden fortune. While his patents had immense theoretical value, most were either sold, licensed, or rendered obsolete by the time of his death. Speculative claims about hidden wealth often stem from the romanticized image of Tesla as a misunderstood genius, but the historical evidence does not support the idea of a secret stash of money.
Q: How did Tesla’s financial situation compare to other inventors of his time?
A: Tesla’s financial trajectory was not unusual for inventors of his era. Many pioneers in electricity and technology struggled to monetize their work, as corporate interests often absorbed their patents. Unlike figures like Thomas Edison, who built business empires around his inventions, Tesla prioritized innovation over profit, which left him financially vulnerable. His story reflects the broader challenges faced by independent inventors in the late 19th and early 20th centuries.
Q: What can we learn from Tesla’s financial struggles?
A: Tesla’s financial story offers insights into the intersection of innovation, capitalism, and individual ambition. His struggles highlight the challenges of monetizing groundbreaking ideas in a system that often favors corporate control over individual inventors. It also underscores the importance of financial planning and legal protections for intellectual property—a lesson that remains relevant for entrepreneurs and innovators today.
