
Common Myths About J. P. Morgan’s Net Worth
The narrative around J. P. Morgan’s net worth has been shaped as much by legend as by fact. One persistent myth frames him as a lone genius who amassed his fortune through sheer brilliance, untouched by the economic crises of his time. Another claims his wealth was so vast it could single-handedly stabilize the U.S. economy—a notion that overlooks the collective efforts of his syndicate partners. These stories, while compelling, obscure the reality: Morgan’s wealth was a product of collaboration, crisis, and the unique financial tools of his era. His net worth was not static but a dynamic force, shaped by the ebb and flow of markets, government interventions, and the very industries he dominated. Equally misleading is the idea that Morgan’s fortune was purely personal. His wealth was often held in trust for heirs, distributed through partnerships, or reinvested in ventures that blurred the line between his assets and those of his associates. The confusion deepens when modern analysts attempt to translate his 19th-century holdings into today’s currency, a process fraught with assumptions about inflation, asset valuation, and the role of leverage. Without precise records, even educated guesses can stray into fantasy.Myth 1: J. P. Morgan’s Net Worth Was Over $100 Billion in Today’s Money
This figure—often cited in popular accounts—emerges from back-of-the-envelope calculations that inflate his peak holdings using contemporary GDP multipliers. While Morgan’s influence was undeniable, the $100 billion claim rests on shaky ground. His wealth was concentrated in illiquid assets: railroads, banks, and industrial trusts whose values fluctuated wildly. A more grounded estimate, based on probate records and contemporaneous appraisals, places his liquid and tangible net worth at his death in 1913 around the $60–80 million range—a staggering sum for the time, but one that pales in comparison to modern hyperinflated projections. Adjusting for inflation, even this figure would translate to roughly $2–3 billion today, a far cry from the oft-repeated $100 billion. The myth persists because it aligns with the romanticized image of the robber baron—a figure whose power seemed limitless. Yet Morgan’s fortune was not untouchable. The Panic of 1907, for instance, forced him to deploy his capital to rescue the financial system, a move that temporarily depleted his personal reserves. His wealth was less a hoard and more a tool, one that was constantly being deployed, reinvested, or leveraged for greater ends.Myth 2: He Left the Majority of His Fortune to a Single Heir
Morgan’s estate plan was a masterclass in dispersal, designed to avoid the concentration of power that had characterized earlier dynasties. Upon his death, his assets were divided among his children, grandchildren, and various trusts, with no single beneficiary receiving a controlling share. His son, J. P. Morgan Jr., inherited the family’s banking interests, but even these were structured to ensure that no one individual could unilaterally dictate the Morgan legacy. The myth of a single heir stems from the public’s fascination with the "self-made" tycoon, but in reality, Morgan’s financial empire was engineered to outlast him—fragmented yet interconnected, like the networks he had spent his career building. This strategy had practical implications. By spreading his wealth, Morgan ensured that his influence would persist across generations, embedded in institutions rather than individuals. It also made it harder for historians to trace the flow of his capital, as assets were absorbed into corporate structures or passed down through trusts with complex terms. The result? A net worth that is impossible to attribute solely to one person, even at the height of his power.Myth 3: His Wealth Was Entirely Self-Made
Morgan’s rise was undeniably his own, but it was also the product of a financial ecosystem that favored insiders. His early career benefited from connections to European banking houses, particularly the Rothschilds, who provided him with capital and credibility. Domestically, his partnerships with figures like George Perkins and the Vanderbilt family gave him access to resources he could not have acquired alone. Even his most celebrated ventures—such as the reorganization of railroads or the formation of U.S. Steel—relied on the collective capital of his syndicate, where his role was often that of the orchestrator rather than the sole investor. The self-made myth ignores the fact that Morgan’s wealth was amplified by the very institutions he helped create. His banks, for example, were not personal slush funds but vehicles for pooling risk across multiple investors. His net worth, therefore, was not just his own but a reflection of the trust others placed in his judgment. This interdependence makes it nearly impossible to isolate his personal holdings from the broader financial machinery he controlled.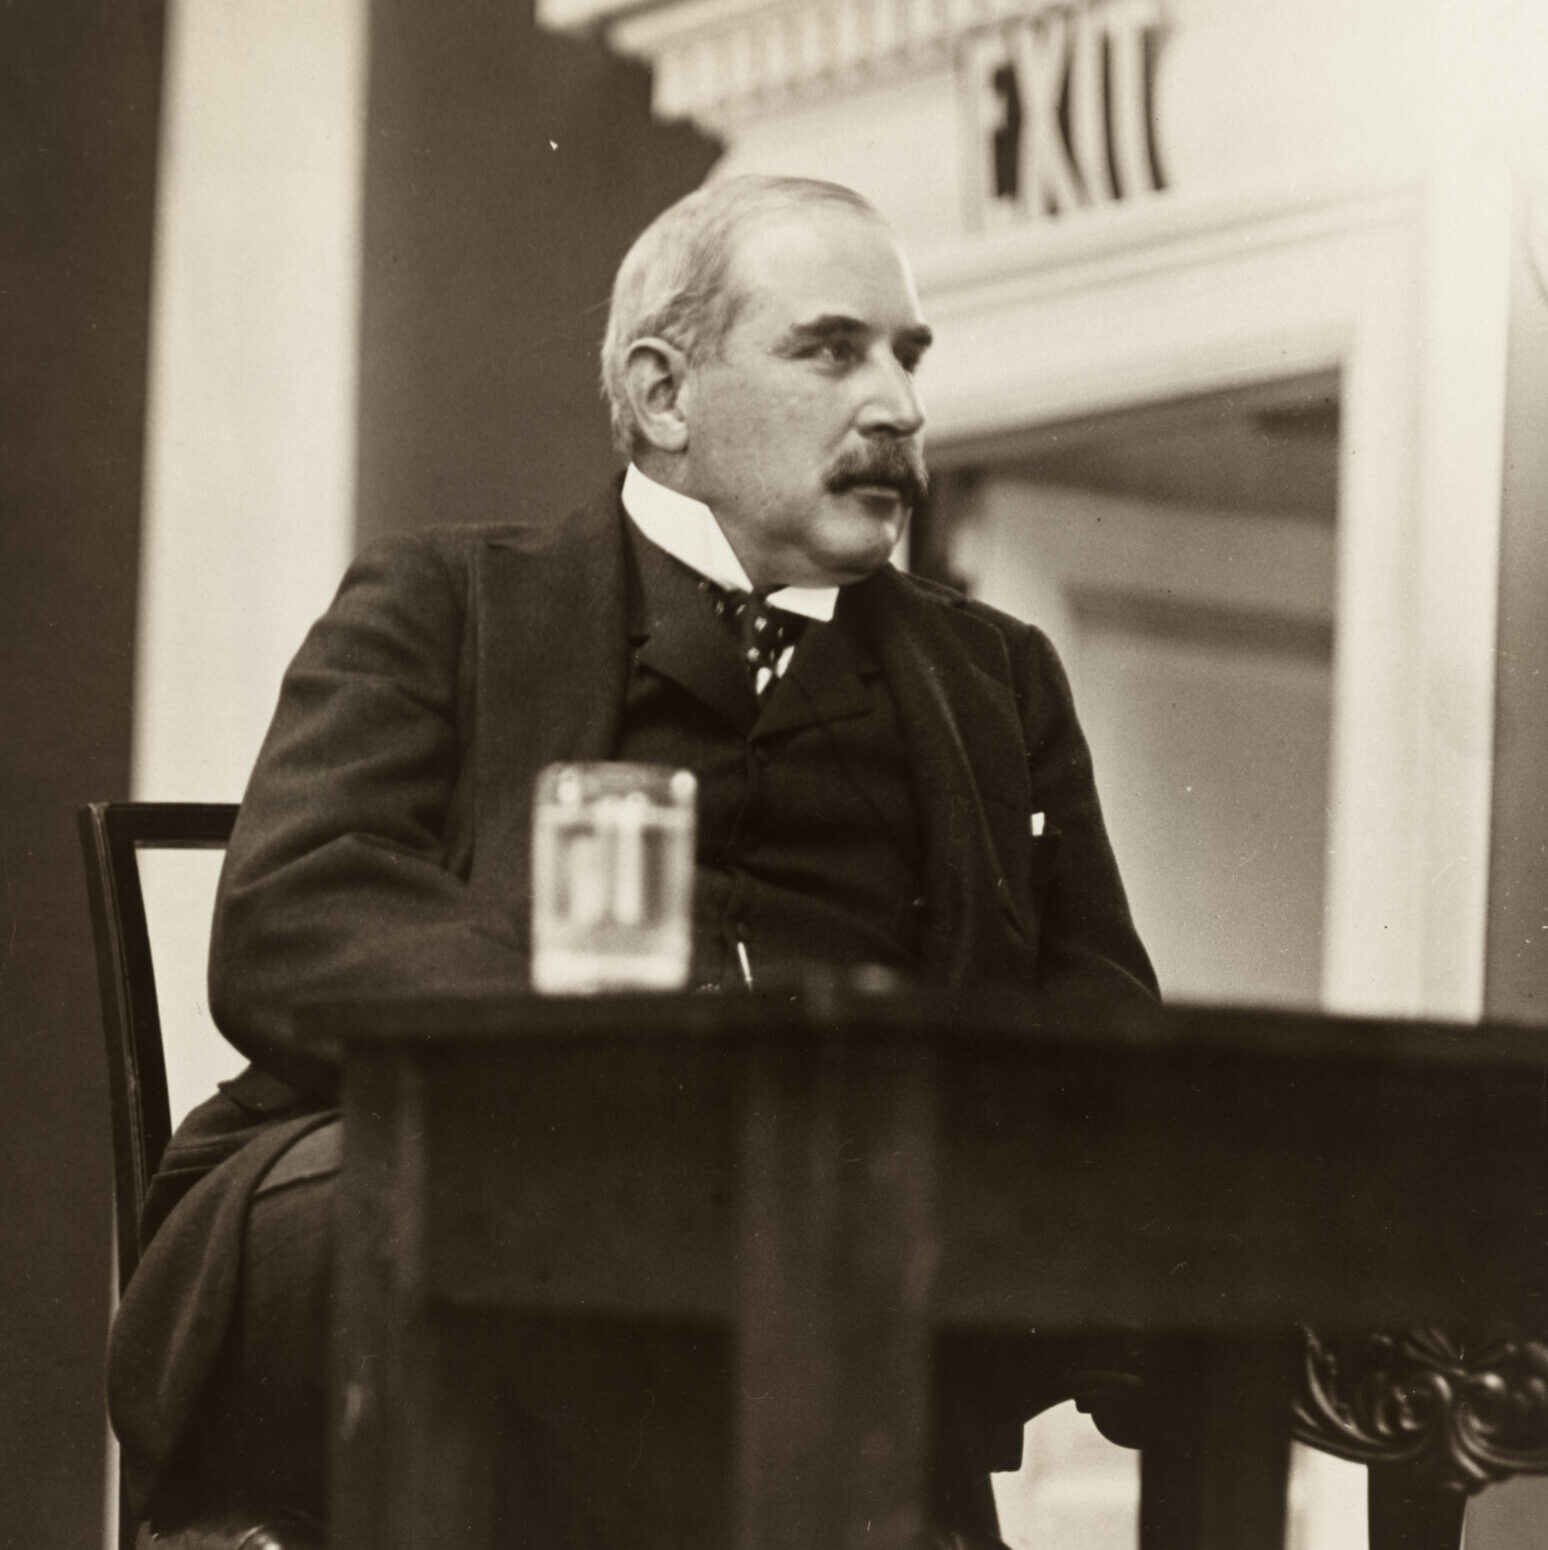
What Holds Up to Scrutiny
At its core, J. P. Morgan’s net worth was not a fixed sum but a constellation of assets, liabilities, and influence. What can be verified are the tangible remnants of his financial empire: the probate records from his 1913 estate, which listed assets including real estate, securities, and cash holdings; the contemporaneous estimates from financial journals like The Bankers Magazine; and the scattered references in his business correspondence. These sources suggest that his peak net worth—adjusted for the economic conditions of his time—likely fell between $60 million and $100 million in the early 1900s, a figure that would equate to roughly $2–3 billion today when accounting for inflation and asset appreciation. The challenge lies in translating these figures into meaningful context. Morgan’s wealth was not liquid in the modern sense; much of it was tied up in railroads, banks, and industrial trusts whose values were volatile. His personal fortune was also intertwined with that of his partners, making it difficult to distinguish between his holdings and those of his associates. For example, his stake in U.S. Steel—often cited as a cornerstone of his wealth—was held through corporate structures that obscured his direct ownership. Similarly, his real estate holdings, including the famous Morgan Library & Museum, were managed by trusts that further diluted his personal control.Blockquote: On the Nature of Morgan’s Wealth
"Morgan’s fortune was not the accumulation of a miser but the capital of a system. He did not hoard; he invested in the machinery of power—railroads, banks, and the credit markets that made modern industry possible. To measure his net worth is to measure the infrastructure of an era." — Niall Ferguson, "The House of Rothschild" (adapted)
Table: Common Beliefs vs. Verifiable Evidence
| Common Belief | What the Evidence Says |
|---|---|
| J. P. Morgan’s net worth exceeded $100 billion in today’s money. | Probate records and inflation-adjusted estimates place his peak liquid net worth closer to $2–3 billion. |
| His wealth was concentrated in personal holdings (gold, cash, land). | Most of his assets were tied to corporate structures, trusts, and partnerships, making direct ownership difficult to quantify. |
| He left the majority of his fortune to one heir. | His estate was divided among multiple trusts and heirs, with no single beneficiary receiving a controlling share. |
| His net worth was purely personal and untouched by financial crises. | Events like the Panic of 1907 required him to deploy capital to stabilize markets, temporarily depleting his reserves. |
| His wealth was entirely self-made, with no reliance on partners or institutions. | His early career and major ventures depended on European banking networks (e.g., Rothschilds) and domestic syndicates. |
Why the Confusion Persists
The enduring mystery around J. P. Morgan’s net worth is less about a lack of data and more about the nature of his financial empire. Morgan operated in an era where wealth was often held in opaque structures—limited partnerships, holding companies, and private trusts—that resisted straightforward valuation. Even his personal assets were managed by teams of lawyers and accountants who ensured that no single record provided a complete picture. This deliberate obscurity was not just a matter of privacy but a strategic move to protect his interests in an age where financial transparency was nonexistent. Modern attempts to quantify his wealth also face the problem of comparability. Inflation adjustments, while useful, can distort the true scale of his holdings when applied to assets like railroads or industrial trusts, whose values were tied to economic conditions of the time. Additionally, the cultural narrative of the "robber baron" has exaggerated Morgan’s personal role in his empire, obscuring the fact that much of his wealth was the product of collective capital. Without a clear line between his personal fortune and the assets of his partners, any attempt to assign a single figure to his net worth is inherently speculative.
Conclusion
The story of J. P. Morgan’s net worth is not just about numbers but about the nature of power in the Gilded Age. His wealth was not a static sum to be hoarded but a dynamic force that reshaped industries, governments, and financial systems. The difficulty in pinning down his exact fortune reflects the complexity of his empire—one that was as much about control as it was about accumulation. While historians may never agree on a precise figure, the exercise of reconstructing his net worth reveals more about the mechanisms of 19th-century finance than it does about the man himself. What remains undeniable is Morgan’s legacy as a financial architect. His net worth was less important than the systems he built, the crises he navigated, and the institutions he left behind. In an age where wealth is often measured in public disclosures and real-time valuations, Morgan’s fortune serves as a reminder of how power operates in the shadows—where influence is currency, and the true measure of success is not what one owns, but what one controls.Comprehensive FAQs
Q: How did J. P. Morgan’s net worth compare to other tycoons of his era?
A: Morgan’s wealth was among the largest of his time, rivaling figures like John D. Rockefeller and Andrew Carnegie. While Rockefeller’s Standard Oil empire generated more in annual revenue, Morgan’s financial networks gave him broader influence over the economy. His net worth was also more diversified, spanning banking, railroads, and industrial trusts, whereas Rockefeller’s fortune was concentrated in oil. Contemporary estimates suggest Morgan’s peak net worth was comparable to Rockefeller’s, though exact comparisons are difficult due to the different structures of their wealth.
Q: Were there any public disclosures of J. P. Morgan’s net worth during his lifetime?
A: No. Unlike modern executives, Morgan did not disclose his personal or corporate finances to the public. Financial journals occasionally speculated about his wealth, but these were educated guesses based on his known investments and business dealings. The closest approximation comes from his 1913 probate records, which provided a snapshot of his estate at the time of his death.
Q: How much of J. P. Morgan’s wealth was tied up in U.S. Steel?
A: U.S. Steel was one of Morgan’s most significant ventures, but his direct stake was held through corporate structures. As a founding investor, he contributed capital to the syndicate that formed the company, but his personal ownership was diluted by the time of its public offering. Estimates suggest his stake in U.S. Steel at its peak was worth tens of millions in today’s money, but this was a fraction of his total net worth.
Q: Did J. P. Morgan’s net worth decline during the Panic of 1907?
A: Yes. The Panic of 1907 required Morgan to deploy a significant portion of his capital to rescue the financial system, including bailing out the New York Stock Exchange and stabilizing the banking sector. While he emerged stronger from the crisis, his personal reserves were temporarily reduced as he funneled funds into stabilizing the economy. This episode underscores how his wealth was not just personal but a public resource.
Q: How was J. P. Morgan’s estate divided after his death?
A: Morgan’s estate was distributed among his children, grandchildren, and various trusts. His son, J. P. Morgan Jr., inherited the family’s banking interests, but the estate was structured to prevent any single heir from gaining total control. Real estate, securities, and other assets were allocated to ensure the Morgan legacy persisted across generations. The exact distribution remains partially private, as some trusts were managed internally by the family.
Q: Can we adjust J. P. Morgan’s net worth for inflation accurately?
A: Adjusting for inflation is possible, but it requires assumptions about the value of his assets. Cash holdings can be adjusted using standard inflation calculators, but illiquid assets like railroads or industrial trusts defy simple conversion. Historians often use a range—such as $2–3 billion in today’s money—for his peak net worth—but this is an estimate, not a precise figure.
Q: Did J. P. Morgan leave any written records detailing his personal finances?
A: Limited records exist. Morgan’s business correspondence and legal documents provide some insight into his financial dealings, but he was not known for keeping personal ledgers. Most of what we know comes from probate records, contemporary newspaper accounts, and the memoirs of his associates. His financial strategies were often communicated verbally or through private agreements, leaving few paper trails.
Q: Why is it so difficult to determine J. P. Morgan’s exact net worth?
A: The opacity stems from three factors: (1) the era’s lack of financial transparency, (2) the use of corporate structures to obscure personal holdings, and (3) the interdependence of his wealth with that of his partners. Unlike modern billionaires, whose net worth is tracked in real time, Morgan’s fortune was embedded in a financial ecosystem that made precise valuation nearly impossible. Even his probate records only capture a snapshot of his estate at death, not his peak wealth.
