
The Complete Overview of the 1 Percent Net Worth Individual in America
The financial landscape of the ultra-wealthy in the U.S. has undergone a seismic shift over the past two decades. Where once fortunes were built on industrial dominance or legacy banking empires, today’s 1 percent net worth individuals thrive in an era of digital capitalism, where intangible assets—intellectual property, data, and algorithmic control—often outvalue physical holdings. The transition from blue-chip stocks to private markets has been particularly pronounced: according to Federal Reserve data, the share of wealth held by the top 1 percent has risen from roughly 25 percent in the 1980s to nearly 40 percent today. This isn’t just growth; it’s a structural realignment of economic power. What’s less discussed is how this wealth is deployed. High-net-worth individuals no longer rely solely on public markets for liquidity. Instead, they’re increasingly turning to alternative investments—private credit, hedge funds with 2-and-20 fee structures, or even direct stakes in startups before they hit the IPO market. The result? A parallel financial system where deals are struck in boardrooms and over private dinners, far from the gaze of regulators or the public eye. For the 1 percent net worth individual, access to these opportunities isn’t just a privilege—it’s a prerequisite for maintaining their status.Historical Background and Evolution
The modern era of the 1 percent net worth individual in America traces back to the late 1970s, when deregulation under Reagan and subsequent administrations began dismantling barriers to financial speculation. The repeal of Glass-Steagall in 1999 and the rise of the dot-com bubble in the late 1990s accelerated the trend, as tech founders and early investors amassed fortunes that dwarfed traditional corporate wealth. By the 2000s, the ascent of private equity—with its leveraged buyouts and activist strategies—further concentrated capital in the hands of a select few. The Great Recession of 2008 didn’t slow this momentum; if anything, it accelerated it, as central bank policies like quantitative easing inflated asset prices and created a new aristocracy of wealth. Today, the composition of this group has diversified. While titans of industry still dominate, a new breed of ultra-wealthy individuals has emerged: the self-made digital billionaires, whose fortunes are tied to platforms, AI, or cryptocurrency. Their rise reflects a broader shift—wealth is no longer just about owning factories or land, but about controlling the infrastructure of the digital economy. This evolution has also democratized certain forms of wealth creation (e.g., angel investing in startups) while simultaneously creating new barriers (the cost of entry into private markets now often exceeds $1 million). The result is a financial ecosystem where the ultra-rich are both the architects and the beneficiaries of the rules.Core Mechanisms: How It Works
The accumulation of net worth at this level isn’t accidental—it’s the result of systematic financial engineering. Take tax optimization, for example. High-net-worth individuals employ strategies like grantor retained annuity trusts (GRATs) or installment sales to grantor trusts (INTs) to transfer wealth to heirs while minimizing estate taxes. These techniques, once the domain of dynastic families, are now accessible to newer wealth creators through specialized advisory firms. The effect? A generation of heirs who inherit not just money, but institutional knowledge about how to preserve and grow it. Then there’s the matter of asset diversification. The ultra-wealthy don’t put their eggs in one basket—they own baskets within baskets. A single individual might hold a stake in a biotech firm, a vineyard in Bordeaux, a commercial real estate portfolio in Miami, and a private jet leased through a shell company in the Cayman Islands. This isn’t just risk management; it’s a strategic play to hedge against inflation, regulatory changes, or market downturns. The result is a portfolio that’s not just large, but resilient in ways that traditional investments can’t match.Key Benefits and Crucial Impact
The advantages of being a 1 percent net worth individual in America extend far beyond personal financial security. These individuals wield influence in ways that shape entire industries. Their philanthropy, for instance, doesn’t just fund charities—it redefines priorities. A single donation from a tech billionaire can launch a university research lab, influence a presidential campaign, or even alter public policy. Meanwhile, their consumer habits set trends: from NFTs to private space travel, the ultra-wealthy don’t just participate in emerging markets—they create them. The psychological dimension is equally significant. For the 1 percent net worth individual, money operates as a form of social capital. Access to exclusive networks—whether in Silicon Valley, Swiss private banking circles, or the art world—isn’t just a perk; it’s a competitive advantage. These connections open doors to deals, opportunities, and information that others can’t access. The result is a self-reinforcing cycle where wealth begets more wealth, not just through investment returns, but through social and intellectual capital."Money is just a tool. What matters is the networks you build around it—and the people who trust you enough to let you into theirs." — A former senior advisor to a Fortune 500 private equity firm
Major Advantages
- Tax Optimization: Access to legal structures like dynasty trusts, offshore entities, and charitable remainder trusts that reduce taxable income by generations.
- Alternative Investments: Participation in private equity, venture capital, and hedge funds that offer returns unachievable in public markets.
- Political Leverage: Direct and indirect influence over policy through lobbying, campaign donations, and think tanks that shape regulatory environments.
- Global Mobility: The ability to relocate capital and residency across jurisdictions to minimize liabilities and maximize opportunities.
- Exclusive Networks: Access to elite circles in finance, technology, and governance that facilitate deals and partnerships unavailable to others.
- Legacy Planning: Strategies to ensure wealth persists across generations, often through family offices or private foundations.
Comparative Analysis
| Metric | 1 Percent Net Worth Individual | Mass Affluent (e.g., $1M–$10M) |
|---|---|---|
| Primary Wealth Sources | Private equity, venture capital, inherited wealth, digital assets | Public stocks, real estate, retirement accounts |
| Tax Strategies | Dynasty trusts, offshore entities, GRATs | Roth IRAs, tax-loss harvesting |
| Liquidity Access | Private credit lines, family offices, direct deals | Brokerage accounts, home equity loans |
Future Trends and Innovations
The next decade will likely see the rise of algorithmically managed wealth for the ultra-wealthy. As AI and machine learning refine predictive models for asset allocation, high-net-worth individuals may delegate more of their portfolios to quant-driven family offices that can outperform even the best human advisors. This shift could further concentrate capital in the hands of those who can afford cutting-edge technology, creating a new divide between the tech-savvy elite and traditional wealth managers. Another emerging trend is tokenized assets. Blockchain-based securities—where stocks, real estate, or even fine art are represented as digital tokens—could democratize certain forms of investment while simultaneously creating new barriers. For the 1 percent net worth individual, this means access to fractional ownership of high-value assets, but also the need to adapt to a financial system where smart contracts replace some of the human intermediaries they’ve long relied on.
Conclusion
The 1 percent net worth individual in America is more than a statistical outlier—they represent a fundamental shift in how wealth is created, preserved, and wielded. Their strategies, networks, and influence are reshaping the economic landscape in ways that will have lasting consequences. For the rest of society, this raises critical questions: Is this concentration of wealth inevitable? Or is it the result of a financial system that rewards access over merit? The answers will determine whether the next generation of ultra-wealthy individuals builds on the privileges of their predecessors—or whether they face a backlash that forces a reckoning with the structures that sustain them. One thing is certain: the rules of the game are changing. And for those who don’t adapt, the gap between the 1 percent and everyone else will only widen.Comprehensive FAQs
Q: How is the 1 percent net worth threshold defined in the U.S.?
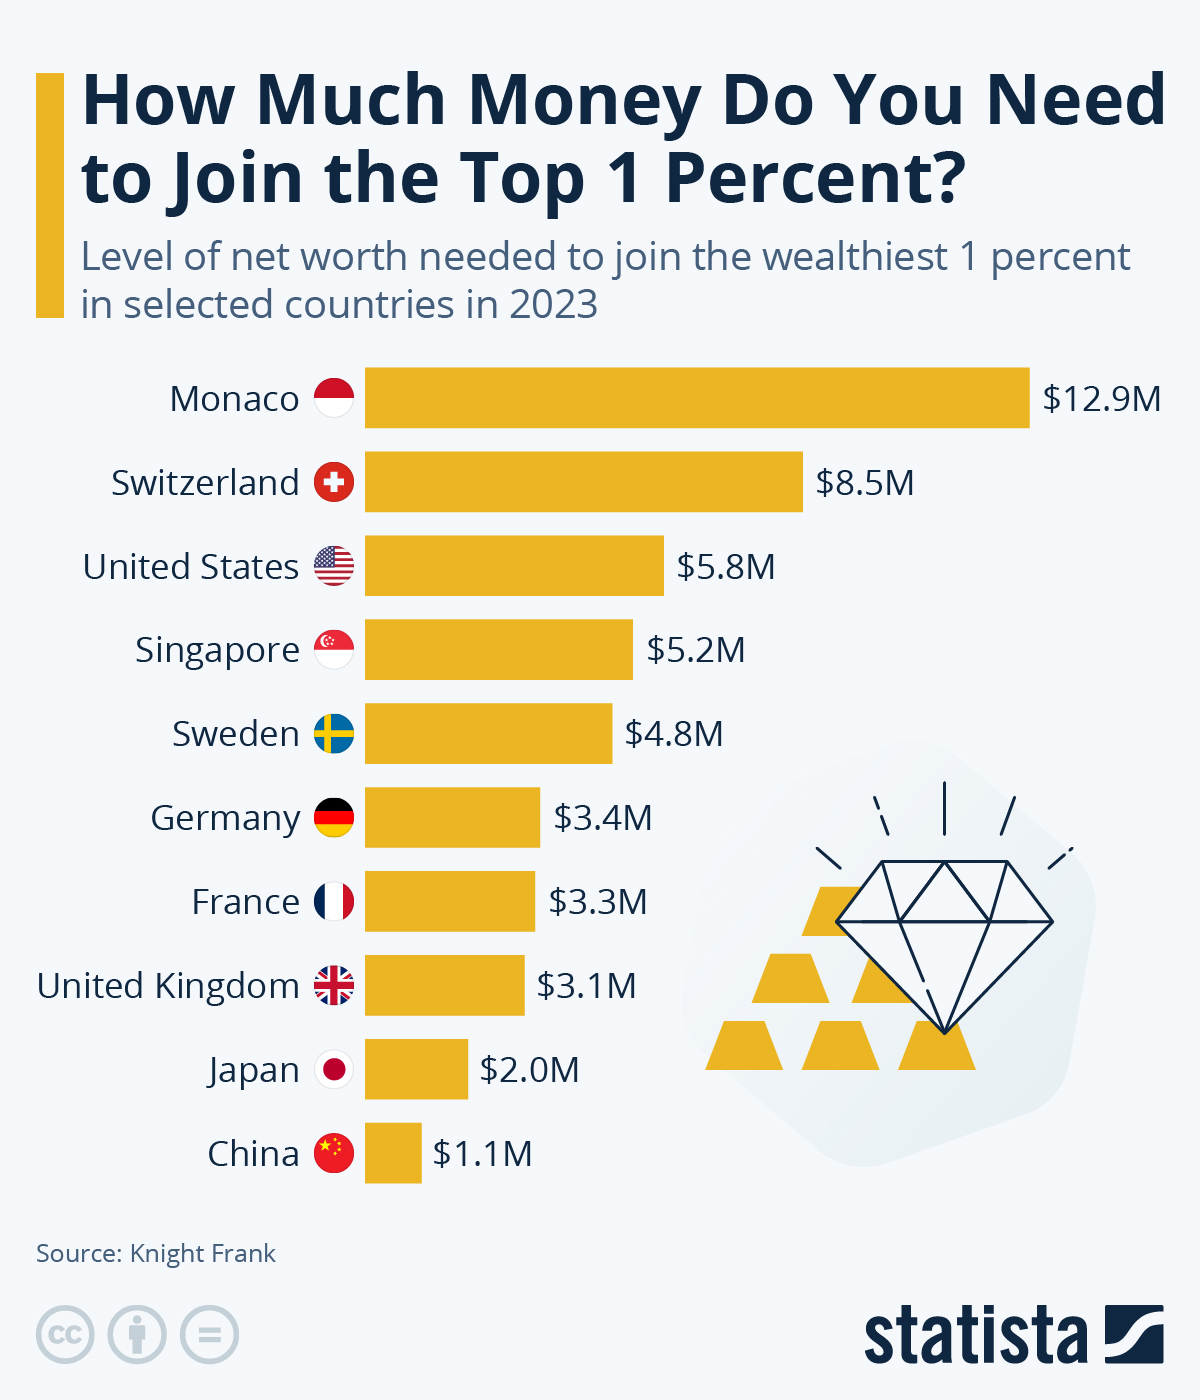
The Federal Reserve and most financial analysts use a net worth of at least $10 million (excluding primary residence) to classify an individual as part of the ultra-high-net-worth demographic. However, some studies adjust this figure based on regional cost of living or inflation. For example, in high-cost cities like New York or San Francisco, the effective threshold may be higher due to elevated asset values.
Q: What percentage of Americans qualify as 1 percent net worth individuals?
According to recent estimates, fewer than 200,000 households in the U.S. meet the $10 million net worth benchmark, representing roughly 0.15% of the population. This group holds a disproportionate share of the nation’s wealth—estimates suggest they control between 30% and 40% of all liquid assets.
Q: How do 1 percent net worth individuals typically structure their wealth for tax efficiency?
Common strategies include dynasty trusts (which can last for centuries and avoid estate taxes), grantor retained annuity trusts (GRATs) for transferring wealth to heirs, and the use of private annuities or charitable remainder trusts. Many also leverage offshore entities in jurisdictions with favorable tax treaties, though recent global transparency initiatives have made this more challenging.
Q: Are most 1 percent net worth individuals self-made, or do they inherit wealth?
The composition varies by generation. Older cohorts (e.g., those who built fortunes in the 1980s–2000s) often include a mix of self-made entrepreneurs and heirs to industrial or financial dynasties. However, newer entrants—particularly in tech—are more likely to be self-made, thanks to the low barriers to entry in digital asset creation (e.g., founding a startup or profiting from early investments in platforms like Uber or Airbnb).
Q: What industries are the most common sources of wealth for this group?
Technology, private equity, and finance dominate, but sectors like real estate, healthcare, and even entertainment (for celebrities with diversified portfolios) also play significant roles. The rise of alternative assets—such as collectibles, wine, or rare art—has also become a key diversification strategy for preserving wealth during economic downturns.
Q: How do 1 percent net worth individuals protect their assets from legal or financial risks?
Beyond tax strategies, they often use asset protection trusts (common in jurisdictions like the Cook Islands or Nevis), limited liability companies (LLCs) for real estate, and insurance products tailored to high-net-worth individuals. Many also maintain family offices—private entities that manage investments, legal compliance, and even personal security—though these typically require a minimum of $100 million in assets to justify the overhead.
Q: What’s the biggest misconception about 1 percent net worth individuals?
The assumption that their wealth is solely the result of individual effort or genius. While ambition and risk-taking play a role, systemic advantages—access to capital, education, networks, and favorable tax policies—are often more decisive. Many of today’s ultra-wealthy individuals benefited from being in the right place at the right time (e.g., early investors in tech or beneficiaries of asset bubbles) rather than outworking everyone else.
