
Breaking Down the Numbers
Disney’s financial health is often reduced to a single metric: its market cap, which hit a peak of over $300 billion in 2019 before plummeting to around $100 billion in 2022. But that oversimplifies the Disney Corporation net worth, which encompasses cash reserves, long-term debt, and the value of its assets—both tangible (theme parks, real estate) and intangible (IP portfolios, streaming subscriptions). The company’s 2023 annual report reveals a total enterprise value (market cap plus debt minus cash) that industry analysts estimate to be in the $150–180 billion range, depending on how one accounts for goodwill and streaming liabilities. The gap between its stock price and intrinsic value stems from investor skepticism about Disney+’s profitability and the company’s ability to service its $28 billion in debt. What complicates the picture is Disney’s segmented revenue model. In 2023, its direct-to-consumer division (streaming, merchandise) lost money, while parks, experiences, and products (PEP) and media networks (ABC, ESPN) remained cash cows. The Disney Corporation net worth is thus a tension between legacy profits and the cost of future growth. For example, Disney’s 2024 capital expenditures—$8 billion—are largely tied to theme park expansions and content production, not debt reduction. This strategy assumes that long-term IP investment will outpace short-term streaming losses, a bet that’s easier to make when interest rates are low.The Verified Baseline
Disney’s most recent 10-K filing (for fiscal 2023) provides a snapshot of its corporate net worth as of September 2023. The company reported $10.1 billion in cash and equivalents against $28.1 billion in long-term debt, a ratio that has improved since 2020 but remains a point of scrutiny. Its total assets were valued at $125.6 billion, while total liabilities stood at $84.3 billion, yielding a book value (assets minus liabilities) of roughly $41.3 billion. However, book value understates Disney’s true worth because it doesn’t fully capture the market value of its IP, which analysts estimate could add $50–70 billion to its valuation if monetized separately. The Disney Corporation net worth is also reflected in its revenue streams. In 2023, Disney generated $85.6 billion in total revenue, with $16.3 billion from its direct-to-consumer segment (Disney+, Hulu, ESPN+), $20.7 billion from media networks, and $24.1 billion from parks, experiences, and products. The streaming division’s losses—$3.5 billion in 2023—are offset by the $12 billion+ annual profit from parks and networks. This divergence explains why Disney’s stock performance is tied to macroeconomic trends (e.g., interest rates) and consumer spending habits (e.g., Disney+ subscriber growth) rather than just quarterly earnings.What the Estimates Suggest
Industry estimates of the Disney Corporation net worth vary widely, but most place its total enterprise value between $150–180 billion as of mid-2024. This range accounts for goodwill (the premium paid for acquisitions like Fox and Lucasfilm) and streaming liabilities, which are expected to persist until Disney+ achieves profitability by 2025. Some analysts, like those at Morgan Stanley, have suggested that Disney’s IP-driven assets could be worth $100–120 billion on their own, though this is speculative. The company’s debt-to-equity ratio—currently around 1.2—is seen as manageable, but rising interest rates could pressure its ability to refinance. A critical factor in these estimates is Disney’s strategy under CEO Bob Iger’s return in 2022. Iger’s focus on cost-cutting (layoffs, studio restructuring) and content efficiency (reducing originals on Disney+) aims to turn streaming profitable by 2025. If successful, this could add $20–30 billion to the Disney Corporation net worth by reducing losses. Conversely, if subscriber growth stalls or ad-supported tiers underperform, the company’s valuation could face downward pressure. The streaming wars—with Netflix, Amazon, and Apple—mean Disney’s net worth trajectory is now as much about subscriber retention as it is about traditional media metrics.
Case Study: A Closer Look
No single decision better illustrates the Disney Corporation net worth’s volatility than its $71 billion acquisition of 21st Century Fox in 2019. At the time, Disney’s market cap surged, but the deal also loaded the company with $13.5 billion in debt and saddled it with integration challenges. The acquisition was meant to bolster its streaming library and international content, but it also diluted earnings in the short term. By 2023, Disney had written down $1.5 billion in goodwill related to Fox assets, a sign that some of the acquired IP wasn’t performing as expected. The Fox deal’s legacy is still unfolding. While The Mandalorian and Avatar sequels have driven box office and streaming success, other Fox properties (e.g., X-Men’s mixed reception) have underperformed. This asset-quality mismatch is a recurring theme in Disney’s corporate net worth: the company’s ability to extract value from its IP portfolio is uneven. The table below outlines key factors influencing its valuation:| Factor | Estimated Impact on Disney Corporation Net Worth |
|---|---|
| Streaming Profitability (2025 Target) | Could add $15–25 billion if achieved; otherwise, subtracts $10–20 billion from enterprise value. |
| Debt Reduction (2024–2025) | Aggressive paydown could improve net worth by $5–10 billion, but high interest rates may limit progress. |
| IP Licensing & Merchandise | Estimated $5–8 billion annual contribution; Star Wars and Marvel remain high-margin but face saturation risks. |
| Theme Park Expansion (Shanghai, Tokyo, Florida) | Long-term play; could add $3–5 billion to net worth over 5 years but requires heavy capex. |
"Disney’s net worth isn’t just about numbers; it’s about the emotional value of its franchises. You can’t put a price on a child’s first visit to Disneyland, but you can measure how much parents will pay for a Star Wars toy or a Disney+ subscription." — Michael Eisner (former Disney CEO), in a 2021 interview with The Hollywood Reporter
What This Means Going Forward
Disney’s path to stabilizing its Disney Corporation net worth hinges on three pillars: streaming profitability, debt management, and IP monetization. The company’s 2024 strategy—reducing content spend, consolidating streaming services, and prioritizing high-ROI projects—aims to align its corporate net worth with investor expectations. If Disney+ hits 200 million subscribers (a target set for 2024) and achieves $1 billion in annual profit, it could justify a higher valuation. However, the ad-supported tier’s performance will be critical; if users migrate en masse to cheaper plans, revenue per user could drop, offsetting subscriber growth. The macroeconomic environment is the wild card. Rising interest rates increase Disney’s borrowing costs, while a recession could dampen park attendance and merchandise sales. The company’s Disney Corporation net worth is thus sensitive to global economic trends—a contrast to tech giants whose valuations are less tied to cyclical consumer spending. This makes Disney’s financial outlook more traditional, even as it competes in a digital-first industry. The challenge for leadership is balancing legacy revenue streams (parks, networks) with future growth (streaming, international expansion) without overleveraging.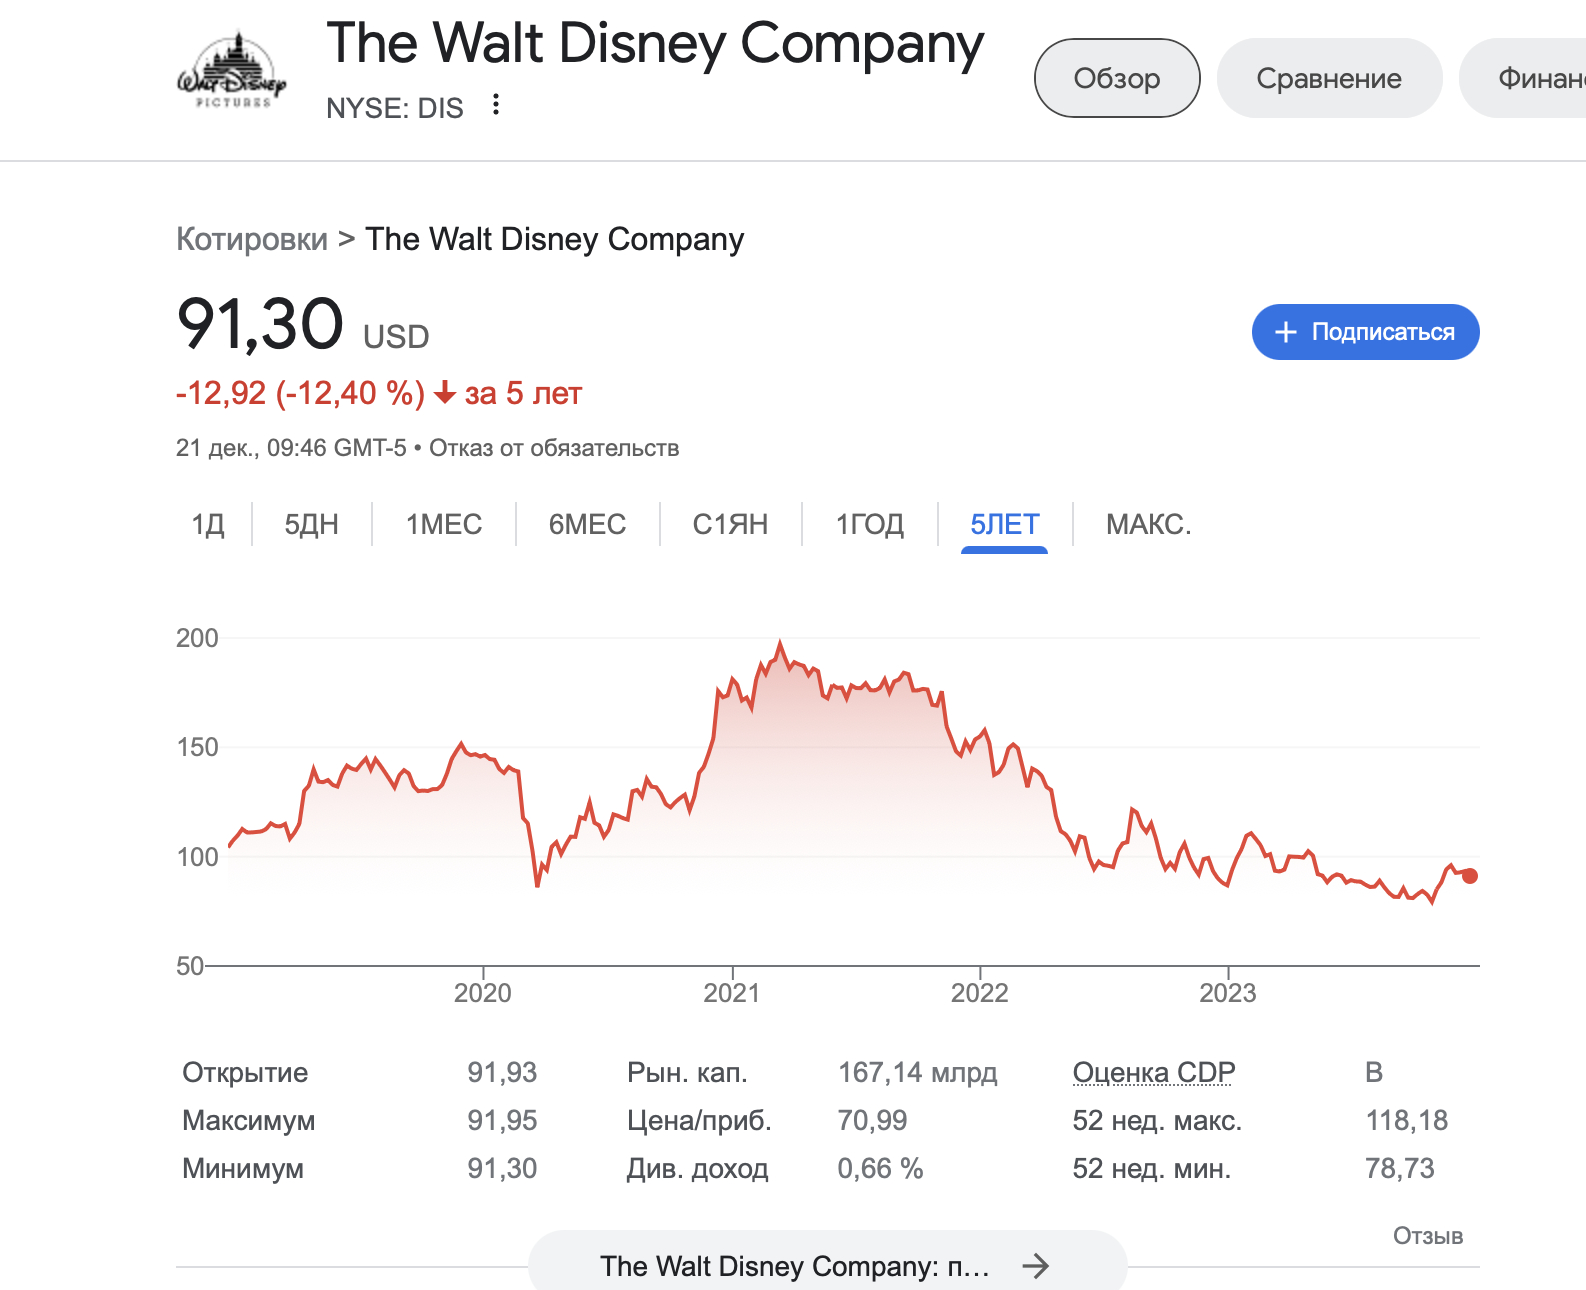
Conclusion
The Disney Corporation net worth is a study in contrasts: a $100+ billion enterprise built on both tangible assets (parks, real estate) and intangible value (IP, brand loyalty). Its financial health is a testament to Disney’s ability to reinvent itself—from animation pioneer to media conglomerate to streaming powerhouse—while grappling with the pitfalls of rapid expansion. The company’s valuation fluctuations reflect broader industry shifts, but its core strength remains its cultural dominance. Whether through Marvel movies, Star Wars sequels, or Disneyland’s magic, Disney’s net worth is ultimately a reflection of its ability to stay relevant across generations. For investors, the key question is whether Disney can transition from a debt-laden growth story to a stable, high-margin business. The answer will depend on streaming execution, debt discipline, and consumer behavior. What’s clear is that the Disney Corporation net worth isn’t just about quarterly earnings—it’s about sustaining the illusion of magic in an era where attention spans are fragmented and competition is fierce. That’s a high bar, but for Disney, it’s one it’s always met—so far.Comprehensive FAQs
Q: How does Disney’s debt compare to other media companies?
Disney’s $28 billion in long-term debt is higher than peers like Warner Bros. Discovery ($12 billion) and Netflix ($15 billion), but lower than Comcast ($100 billion). Its debt-to-equity ratio (~1.2) is in line with industry averages, though rising interest rates have increased refinancing risks. The company has prioritized debt reduction in 2024, targeting a $20 billion debt level by 2025.
Q: Why did Disney’s stock price drop so sharply in 2022?
The Disney Corporation net worth took a hit in 2022 due to three major factors: (1) Streaming losses widened as Disney+ subscriber growth slowed; (2) Rising interest rates increased borrowing costs; and (3) Park closures during COVID-19 and supply chain issues hurt PEP segment revenues. The stock fell from $200+ in 2019 to under $80 in 2022, though it has since recovered to $100–120 as cost-cutting measures take effect.
Q: How much of Disney’s revenue comes from international markets?
International revenue accounts for ~40% of Disney’s total revenue, with Asia-Pacific (especially China) and Europe as key regions. The Disney Corporation net worth is heavily influenced by park performance (Shanghai Disneyland is a major driver) and streaming adoption (Disney+ has 150+ million subscribers globally, with 50% outside the U.S.). However, geopolitical risks (e.g., China’s regulatory crackdowns) and currency fluctuations pose challenges.
Q: Could Disney spin off its parks or streaming business to boost net worth?
Spin-offs are unlikely in the near term due to synergies between segments (e.g., Star Wars content drives both streaming and park merchandise). However, analysts speculate that selling non-core assets (e.g., regional sports networks) or restructuring debt could improve the Disney Corporation net worth. A partial spin-off of ESPN or Disney+ has been discussed but would require shareholder approval and could dilute brand value.
Q: What’s the biggest threat to Disney’s long-term net worth?
The biggest existential risk is streaming failure. If Disney+ fails to turn profitable by 2025, it could force further cost cuts, content layoffs, or even a downsizing of its IP library. Other threats include competition from Netflix and Amazon, regulatory scrutiny (e.g., antitrust concerns over IP bundling), and climate-related disruptions (e.g., park closures due to extreme weather). However, Disney’s brand loyalty and franchise power make a total collapse unlikely—even in worst-case scenarios.
