Where It All Began
The roots of the gross vs. net worth divide trace back to the 19th century, when industrialists first needed to distinguish between total assets and usable capital. Before standardized accounting, a factory owner might list his machinery, land, and gold reserves as "worth" X—only for creditors to later discover that debts, pending lawsuits, and the cost of upkeep ate into those figures. The term net worth emerged as a corrective, a way to say: "Here’s what you’d actually get if everything was sold tomorrow, after paying everyone who’s owed." Early adopters of this distinction were railroad tycoons. A magnate like Jay Gould could boast a gross worth in the millions based on land deeds and stock certificates, but his net worth—after mortgages, bribes, and volatile commodity prices—was often a fraction of that. The press, eager for dramatic narratives, latched onto the gross numbers. By the 1880s, newspapers were already publishing "fortunes" that bore little resemblance to liquidity. The difference between gross and net worth became a tool for both deception and due diligence.The Early Signs
The first red flags appeared in the Gilded Age, when society pages reported on "millionaires" whose lifestyles suggested far less disposable income. A hostess might throw a ball costing £50,000—only for her husband’s creditors to later seize his yacht to cover gambling debts. The discrepancy wasn’t always malicious. Many early adopters of net-worth accounting were simply trying to avoid bankruptcy. But the confusion between the two figures created a market for speculation. By the 1920s, Hollywood studios exploited this gap. A star’s gross worth—calculated by adding up film contracts, real estate, and jewelry—could be inflated to secure better deals, while their net worth (after agent cuts, IRS demands, and the cost of upkeep) was a fraction of that. The studio system thrived on this opacity. Today, the same dynamic plays out in tech, sports, and even social media, where influencer "worth" is often a gross estimate with no liabilities factored in.The Turning Point
The shift from gross to net as the dominant measure of wealth came in the 1970s, when tax laws forced transparency. Before then, a corporation could list assets at inflated values while hiding liabilities in offshore accounts. The difference between gross and net worth became a battleground between regulators and the ultra-wealthy. The turning point? The Tax Reform Act of 1976, which required corporations to disclose net worth for valuation purposes. Suddenly, the gap between what a company claimed and what it owed couldn’t be ignored. This era also saw the rise of private equity, where gross asset values were used to attract investors, while net worth—after fees, carried interest, and hidden carry costs—was often a closely guarded secret. The difference between gross and net worth wasn’t just a footnote; it was the mechanism that allowed fund managers to justify exorbitant fees. As one former hedge fund analyst put it:"You can dress up a gross number however you want—depreciation schedules, valuation adjustments, ‘strategic reserves’—but net worth is what the bank sees when you ask for a loan. The rest is theater."
The Build-Up, Year by Year
| Period | What Changed |
|---|---|
| 1980s | Leveraged buyouts (LBOs) became common, where gross asset values were used to secure debt, but net worth—after interest and restructuring costs—often plunged investors. The savings & loan crisis exposed how inflated gross figures masked insolvency. |
| 1990s | Dot-com boom saw gross valuations of startups skyrocket, but most had negative net worth after burn rates and unpaid salaries. The crash revealed that the difference between gross and net worth could be the difference between a unicorn and a cautionary tale. |
| 2000s | Private equity firms refined the art of gross inflation, using complex debt structures to show "paper wealth" while net worth eroded under management fees. The 2008 crisis proved that even billion-dollar gross figures couldn’t shield assets from systemic risk. |
| 2010s | Celebrity endorsements and influencer "worth" became gross estimates with no liabilities. A musician’s gross worth might be listed as £100M, but after tour costs, legal fees, and unpaid advances, their net worth could be a fraction of that. |
| 2020s | Crypto and NFT markets blurred the lines further, where gross valuations of digital assets had no correlation to net liquidity. The FTX collapse exposed how the difference between gross and net worth could disappear overnight. |
Lessons From the Journey
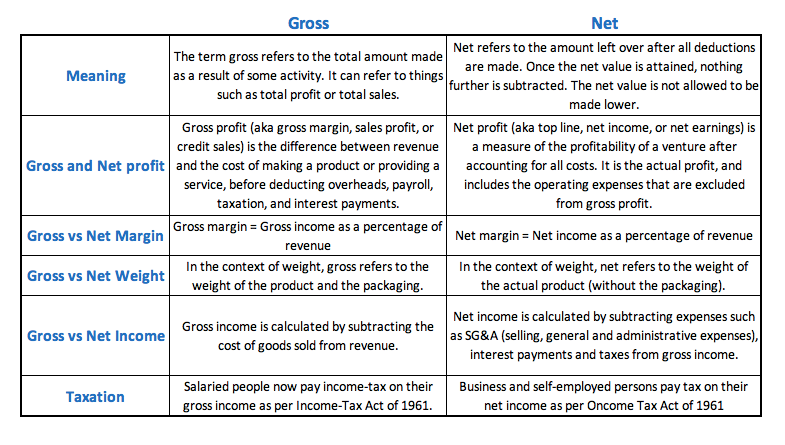
- Gross worth is a starting point, not a destination. It’s what you claim to own; net worth is what you actually control after obligations.
- Liabilities aren’t just debts—they include taxes, legal risks, and the cost of maintaining wealth (e.g., staff, security, upkeep).
- The difference between gross and net worth widens in volatile markets, where asset values fluctuate but liabilities remain fixed.
- Public figures often manipulate gross numbers for leverage (e.g., loan applications, divorce settlements), while private individuals focus on net liquidity.
Where Things Stand Today
Today, the difference between gross and net worth is more pronounced than ever. In an era of algorithmic trading, offshore trusts, and "paper wealth" (e.g., unlisted stocks, crypto), the gap between what’s reported and what’s real has never been wider. A tech CEO might see their gross worth spike after a stock option grant, only for their net worth to drop when those options vest with restrictions. Meanwhile, a musician’s gross worth—based on catalog sales and merchandise—can be inflated by resale markets, while their net worth suffers from unpaid advances and tour deficits. The confusion extends to everyday finance. A homeowner might list their property’s gross value at £1M, but after mortgage, taxes, and maintenance, their net equity is a fraction of that. The same applies to small businesses, where gross revenue is often confused with net profit. The result? Poor financial decisions, overleveraged lifestyles, and a distorted view of what wealth truly means.
Conclusion
The difference between gross and net worth isn’t just a technicality—it’s the foundation of financial literacy. Ignoring it leads to bad investments, unrealistic expectations, and even legal trouble. Yet, the temptation to focus on gross figures persists, whether for marketing, ego, or sheer ignorance. The key is to ask: What’s the real cost of that wealth? Is it liquid? Is it at risk? And most importantly, does it reflect reality? For individuals, this means moving beyond vanity metrics and focusing on net liquidity—what you can actually spend or invest. For institutions, it’s about transparency: disclosing liabilities alongside assets. And for the public? It’s about recognizing that the numbers you see are rarely the full picture. Wealth, like any currency, is only as valuable as what it can buy after the dust settles.Comprehensive FAQs
Q: Why do celebrities and public figures often have inflated gross worth figures?
Public figures—celebrities, athletes, and executives—often have gross worth figures inflated for branding, leverage in negotiations (e.g., endorsements, loans), or to secure favorable terms in divorces. Their net worth is typically lower due to unpaid taxes, legal fees, lifestyle costs (e.g., security, travel), and the true depreciation of assets like art collections or private jets. For example, a musician’s catalog might be valued at £50M gross, but after royalties, advances, and management cuts, their net worth could be significantly less.
Q: Can net worth ever be higher than gross worth?
No, by definition, net worth is always equal to or lower than gross worth because it subtracts liabilities (debts, taxes, expenses) from total assets. However, in rare cases—such as when a company’s liabilities are negative (e.g., tax refunds or pending settlements)—the net worth might appear artificially high compared to a misleadingly low gross asset figure. But this is an exception, not the rule.
Q: How do businesses use the difference between gross and net worth to their advantage?
Businesses exploit the gross vs. net worth gap in several ways:
- Securing loans: Banks may lend based on gross asset values, even if the company’s net worth is far lower.
- Mergers & acquisitions: A target company’s gross worth is inflated to justify a high purchase price, while its net worth (after debt and restructuring costs) becomes the buyer’s burden.
- Investor appeals: Startups and private equity firms highlight gross valuations to attract capital, while net worth—after fees and burn rates—is downplayed.
Q: What’s the most common mistake people make when calculating their own worth?
The biggest mistake is ignoring liabilities and focusing only on assets. Many people list their home, car, and investments as their gross worth, then assume that’s their net worth. But they forget:
- Mortgages, loans, and credit card debt.
- Pending legal or tax obligations.
- The cost of maintaining assets (e.g., property upkeep, insurance).
Q: How can I protect myself from being misled by gross worth figures?
To avoid falling for inflated gross worth claims:
- Demand transparency: Ask for a full breakdown of assets and liabilities.
- Verify sources: Gross figures from tabloids or social media are often speculative. Look for audited financials.
- Focus on liquidity: A high gross worth with illiquid assets (e.g., real estate, art) is less valuable than cash or easily tradable securities.
- Consider the context: A celebrity’s gross worth might include future earnings (e.g., royalties), but their net worth reflects current spendable funds.
