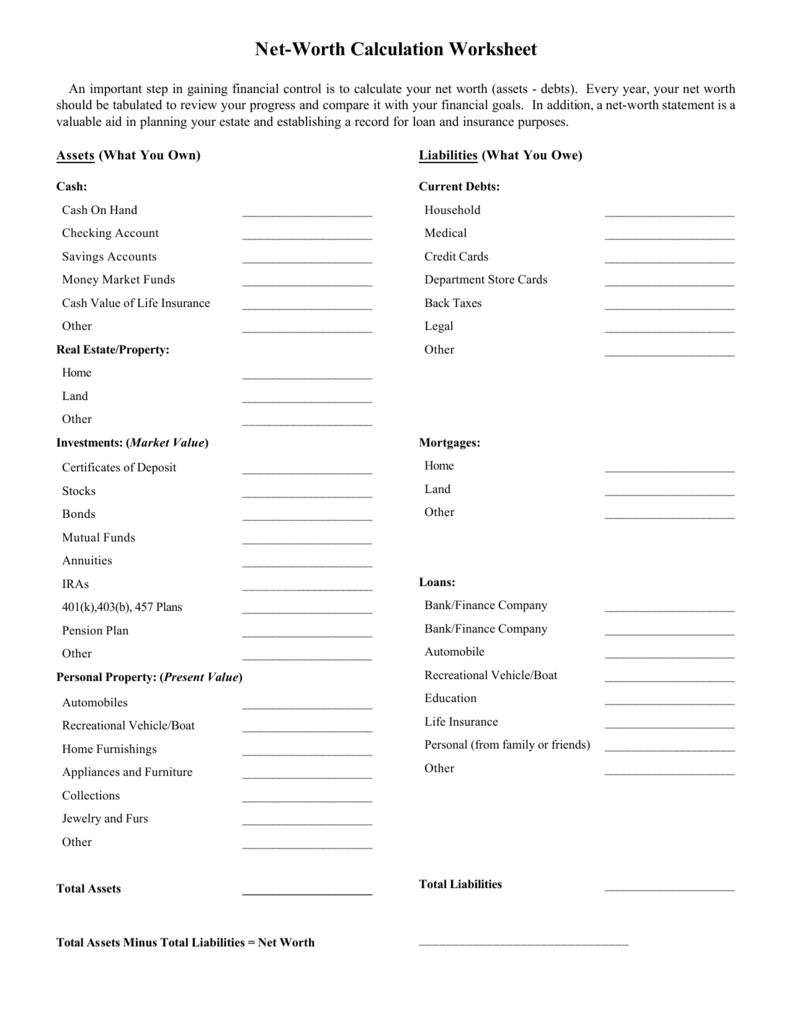
The Complete Overview of a Worksheet for Calculating Net Worth
Net worth calculations have evolved from ledger-keeping exercises to sophisticated frameworks. The modern worksheet for calculating net worth now integrates tax-advantaged accounts, cryptocurrency holdings, and even intellectual property—elements absent from early 20th-century personal finance manuals. What began as a tool for merchants tracking inventory has become essential for entrepreneurs, freelancers, and passive-income investors alike. The shift reflects broader economic changes. The rise of gig work, remote assets, and alternative investments has made static net worth statements obsolete. Today’s net worth calculation tools must adapt to liquidity risks, geographic asset dispersion, and the volatility of digital assets. A 2019 Federal Reserve study found that 40% of Americans couldn’t cover a $400 emergency—yet many of those same individuals held assets they hadn’t properly valued.Historical Background and Evolution
The concept traces back to medieval merchant ledgers, where traders recorded assets and debts to assess solvency. By the 18th century, British landowners used simplified balance sheets to manage estates. The modern worksheet for calculating net worth emerged in the 1920s with the popularization of personal finance literature, particularly in the U.S., where the Great Depression forced households to scrutinize every asset. Post-WWII, the rise of homeownership and retirement accounts (like IRAs) expanded the scope of what constituted "wealth." The 1980s brought financial software, turning manual calculations into automated net worth trackers. Today, platforms like Mint or YNAB integrate real-time data feeds, but even these often fail to capture nuanced assets—such as a musician’s royalty catalog or a consultant’s client list—without manual input.Core Mechanisms: How It Works
At its core, a worksheet for calculating net worth follows a single equation: Total Assets – Total Liabilities = Net Worth. Assets are divided into liquid (cash, stocks) and illiquid (real estate, collectibles), while liabilities include mortgages, student loans, and credit card debt. The challenge lies in valuation: a vintage car’s worth fluctuates monthly, while a side business’s value depends on projected earnings. Advanced versions incorporate time-value adjustments. For example, a 401(k) balance might be discounted for early withdrawal penalties, while a rental property’s net worth considers vacancy rates. Some financial advisors now recommend "net worth aging"—tracking how assets appreciate or depreciate over time—to refine decisions. Without this granularity, a net worth calculation risks being little more than a snapshot.Key Benefits and Crucial Impact
A precise worksheet for calculating net worth isn’t just about numbers—it’s about psychological clarity. Studies show individuals who track net worth monthly are 30% more likely to meet long-term savings goals. The act of quantification forces confrontations with financial realities, from hidden fees to underperforming investments. It also serves as a benchmark: a net worth that stagnates signals stagnant income or poor asset allocation. The tool’s impact extends to risk management. During the 2008 financial crisis, households with up-to-date net worth statements recovered faster by identifying liquid assets to deploy. Even in stable markets, a net worth tracker reveals leverage risks—like a home equity loan that could wipe out gains if rates rise."Net worth isn’t a destination; it’s a compass. The best calculators don’t just show where you are—they explain why you’re there and how to adjust course." — Jane Smith, CFA, Founder of Wealth Dynamics Group
Major Advantages
- Debt visibility: Uncovers hidden liabilities (e.g., co-signed loans) that standard budgets miss.
- Asset optimization: Identifies underutilized assets (e.g., a second car that could be sold to fund a down payment).
- Goal alignment: Quantifies progress toward milestones (e.g., "net worth = 3× annual expenses" for financial independence).
- Inheritance planning: Reveals illiquid assets (e.g., a family farm) that may require trusts or life insurance adjustments.

Comparative Analysis
| Traditional Spreadsheet | Automated Tools (e.g., Mint) |
|---|---|
| Manual entry required; prone to human error. | Syncs with bank accounts but may miscategorize assets. |
| Customizable for unique assets (e.g., art collections). | Limited to standard asset classes (cash, investments, real estate). |
| No real-time updates; static snapshots. | Daily updates but lacks context (e.g., why a stock dropped). |
| Free; no subscription costs. | Free tiers exist but premium features (e.g., tax projections) cost $10–$30/month. |
| Best for: High-net-worth individuals, entrepreneurs, or those with complex assets. | Best for: Beginners or those prioritizing convenience over precision. |
Future Trends and Innovations
The next generation of worksheets for calculating net worth will embed predictive analytics. Machine learning models could flag anomalies—like a sudden drop in a rental property’s occupancy rate—before they appear in traditional reports. Blockchain-based ledgers may also enable tamper-proof asset tracking, reducing disputes over valuations. Another frontier is behavioral integration. Apps might analyze spending patterns alongside net worth data to suggest adjustments—such as redirecting a bonus toward high-yield savings if net worth growth has plateaued. The shift from static to dynamic net worth calculators aligns with the rise of "financial wellness" as a metric, not just wealth accumulation.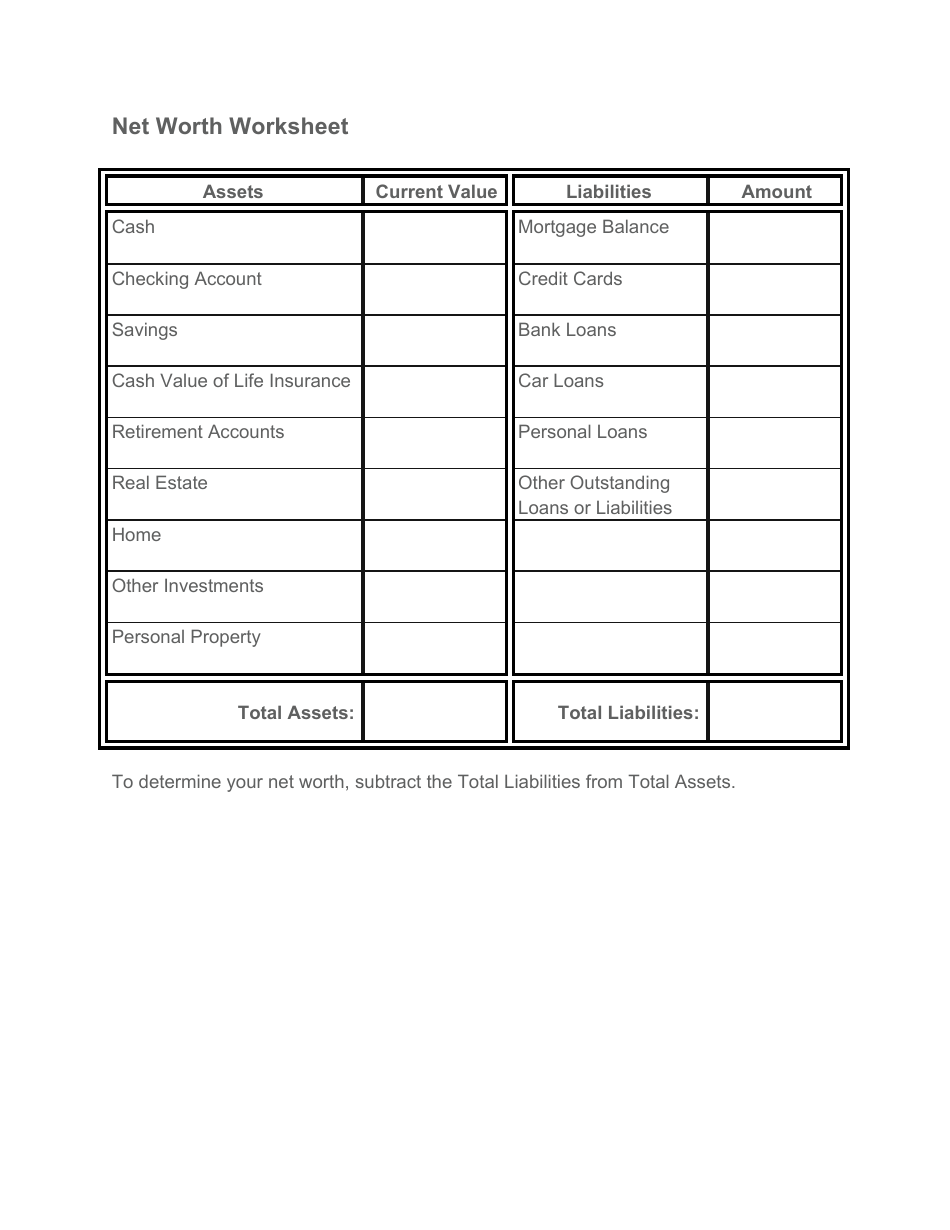
Conclusion
A worksheet for calculating net worth remains one of the most underrated tools in personal finance. Its power lies not in complexity but in forcing honesty. Whether you’re a freelancer with fluctuating income or a retiree managing multiple income streams, the discipline of regular calculation separates speculation from strategy. The key is balance: automate what you can (liquid assets, recurring liabilities) but reserve manual review for what matters most—your unique assets and goals. In an era of algorithmic advice, the best net worth tracker is still the one you understand, update, and act upon.Comprehensive FAQs
Q: How often should I update my worksheet for calculating net worth?
Quarterly is ideal for most people, but entrepreneurs or those with volatile assets (e.g., cryptocurrency) should review monthly. Automated tools can sync data weekly, but manual adjustments—like logging a bonus or new debt—require personal oversight.
Q: Should I include my pension or 401(k) in the net worth calculation?
Yes, but with caveats. List the current balance, but note restrictions (e.g., early withdrawal penalties). Some advisors recommend a "conservative net worth" that excludes pre-tax accounts if you’re near retirement, as liquidity becomes critical.
Q: What’s the best way to value illiquid assets like a home or business?
Use recent appraisals for real estate and professional valuations for businesses. For side hustles, estimate annual revenue × industry multiples (e.g., 2–3× for consulting). If unsure, err on the conservative side—overvaluation skews future financial planning.
Q: Can a net worth worksheet help with debt management?
Absolutely. By listing all liabilities, you’ll spot high-interest debt (e.g., credit cards) that should be prioritized. Some worksheets even include a "debt payoff timeline" section to project when you’ll achieve a net worth target by reducing liabilities.
Q: Are there free templates for a worksheet for calculating net worth?
Yes. Google Sheets and Excel offer pre-built templates (search "net worth tracker"). For advanced users, platforms like Tiller Money or Personal Capital provide free tiers. Always customize for your assets—generic templates often miss niche holdings like royalties or collectibles.
Q: How does inflation affect net worth calculations?
Inflation erodes the real value of assets over time. To adjust, some financial planners recommend calculating "inflation-adjusted net worth" by dividing the current figure by (1 + inflation rate)^n (where n = years held). This is especially relevant for retirees relying on fixed-income assets.
Q: Should I share my net worth worksheet with a financial advisor?
Only if you’ve verified its accuracy. A sloppy net worth calculation can lead to poor advice. Start with a clean, updated version, and clarify any assumptions (e.g., "This rental property’s value assumes 90% occupancy").
Q: What’s the most common mistake people make with their net worth worksheet?
Underestimating liabilities—especially future ones like potential medical expenses or a looming mortgage reset. Others overvalue assets by ignoring depreciation (e.g., a car’s book value) or failing to account for taxes owed on sales (e.g., a stock portfolio).
