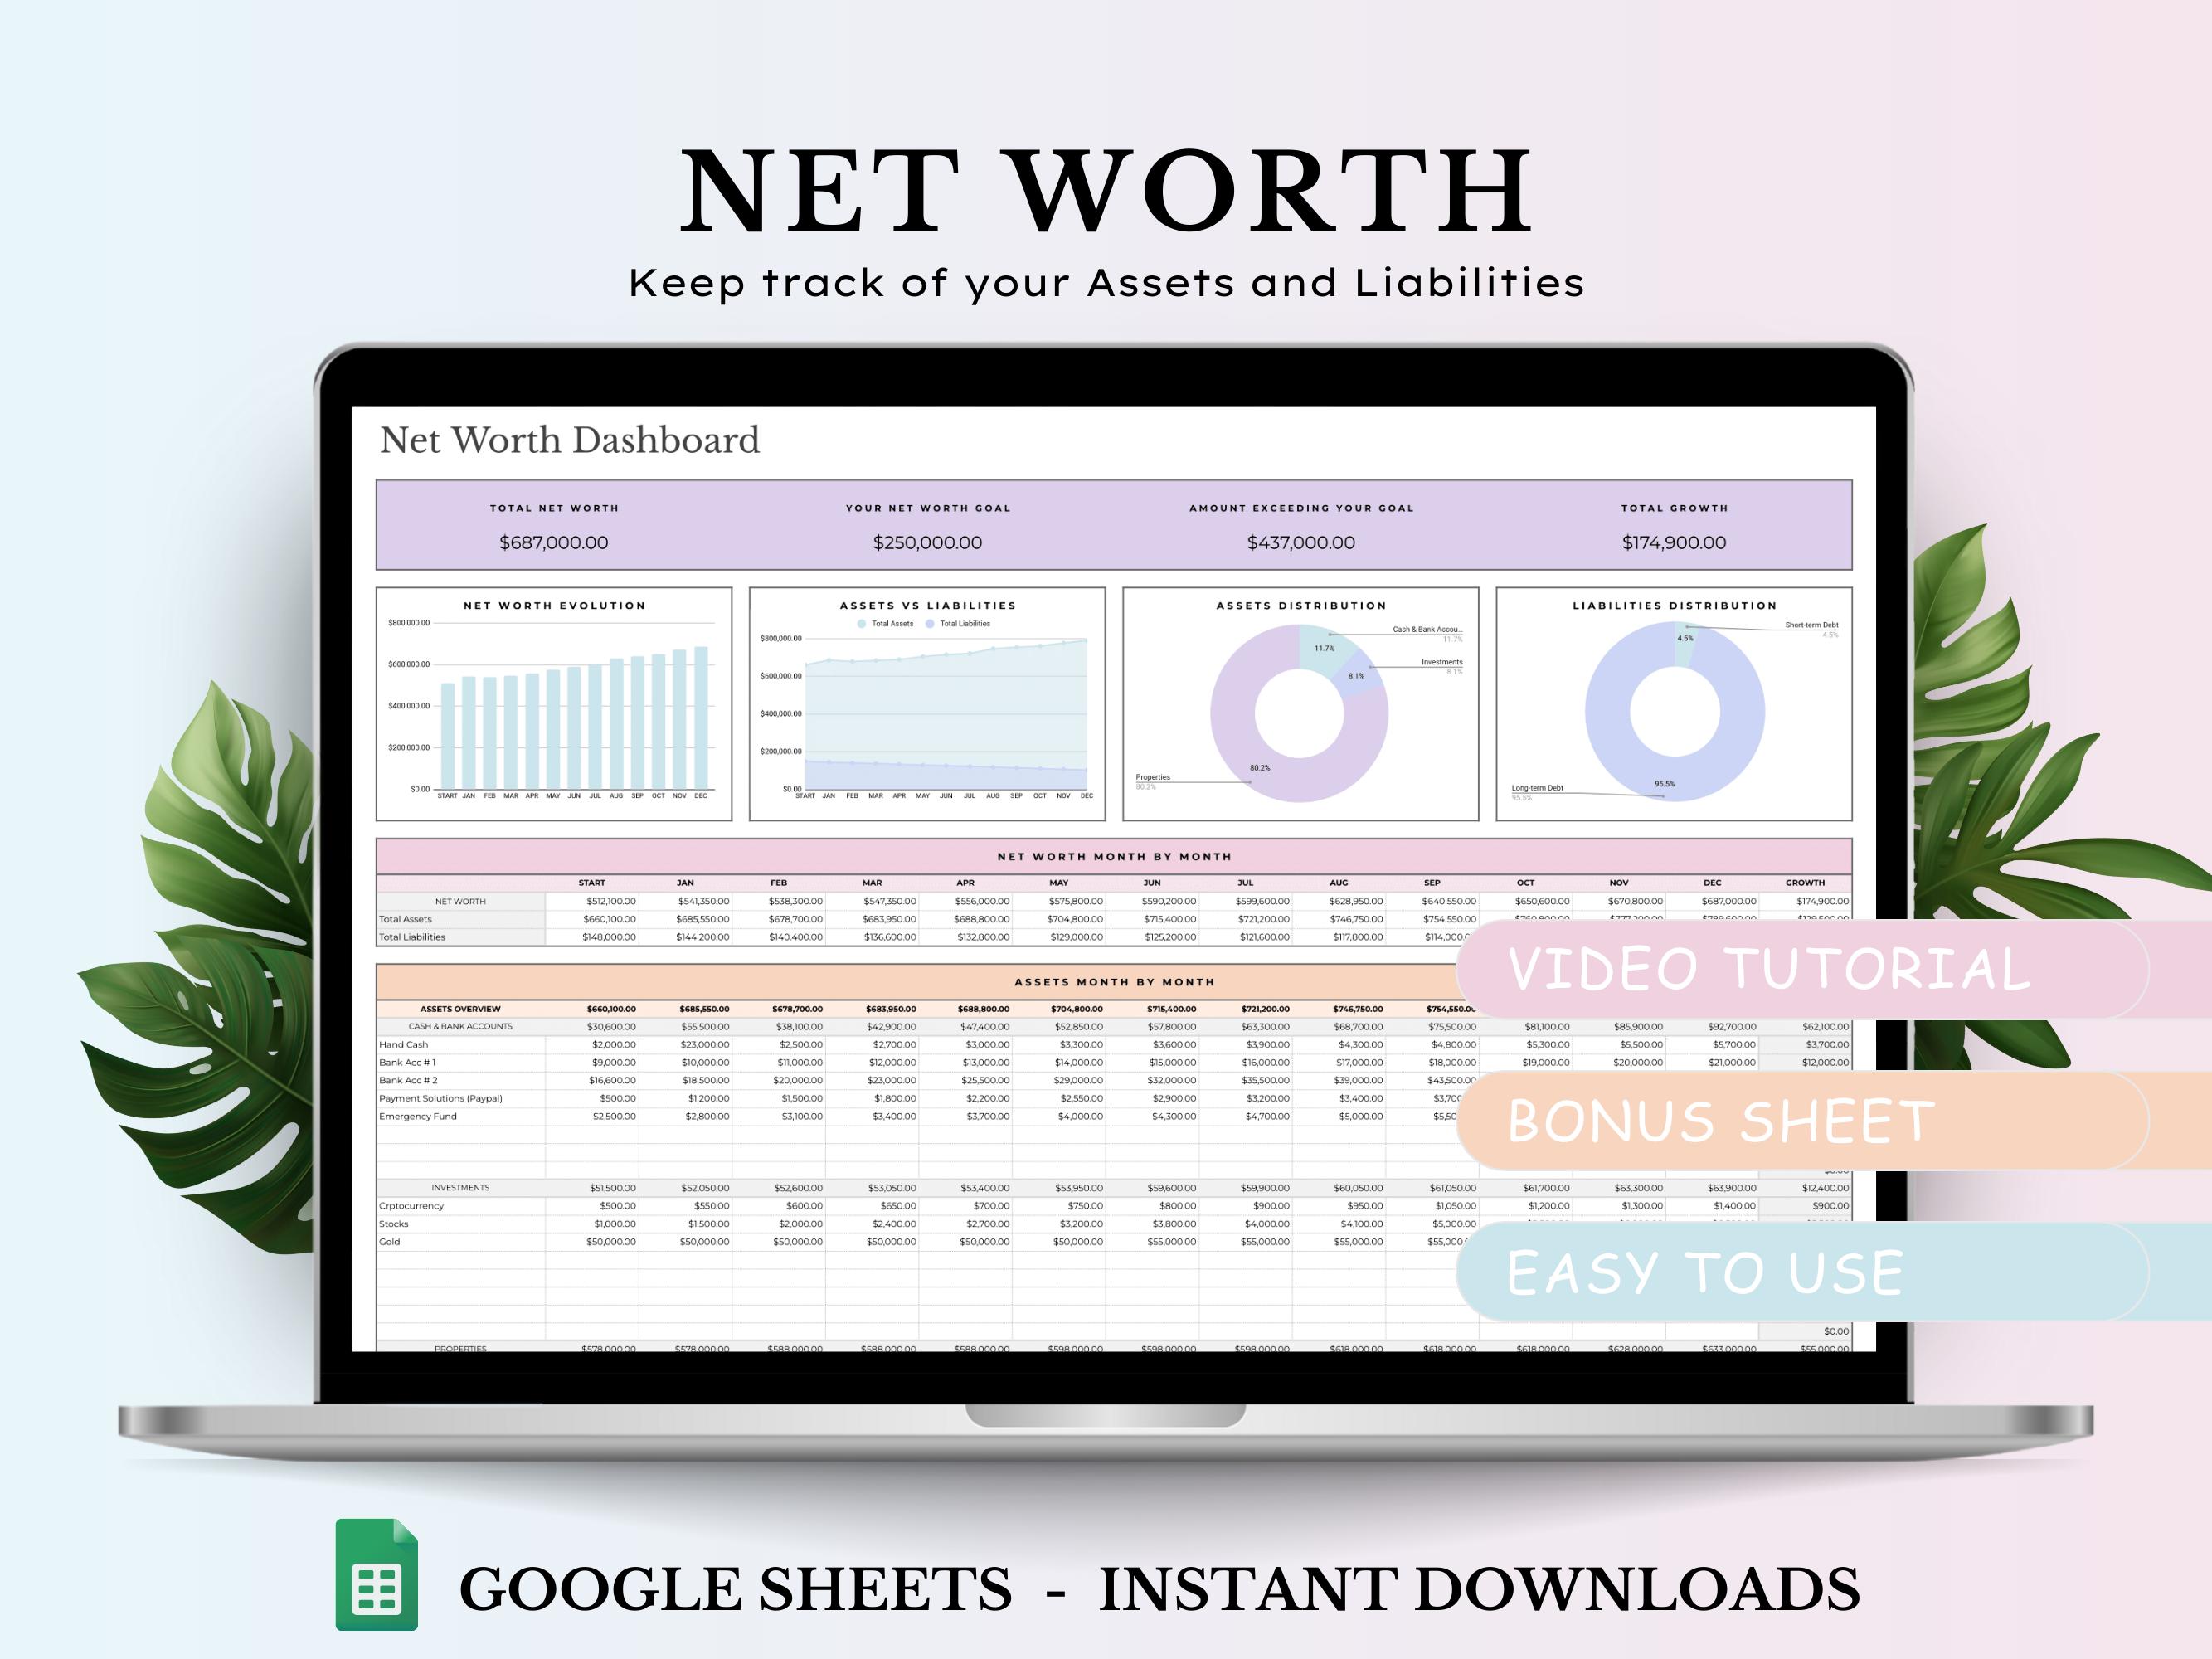
5 Things Worth Knowing About How to Perform a Net Worth Analysis
Understanding how to perform a net worth analysis starts with recognizing its five critical dimensions. These aren’t just theoretical concepts—they’re the difference between a snapshot and a strategic tool.1. Assets Aren’t All Equal in Valuation
Not all assets contribute equally to net worth. Tangible assets like real estate or collectibles require professional appraisals, while intangible assets—such as patents or digital royalties—demand legal verification. The mistake many make is treating all assets as liquid; a family heirloom might hold sentimental value but zero market liquidity. Even cash isn’t uniform: a high-yield savings account earns interest, while a locked-in pension fund has restricted access. How to perform a net worth analysis correctly means categorizing assets by liquidity tier—immediate, short-term, or illiquid—and adjusting for time-sensitive factors like depreciation or obsolescence. For example, a 2010 luxury car might appear on a balance sheet at its original purchase price, but its actual market value could be 60% lower due to wear and tear. Meanwhile, a 20-year-old wine investment could appreciate 15% annually if properly stored. The analysis must account for these variables, not just static figures.2. Debt Isn’t Just a Liability—It’s a Strategic Tool
Debt isn’t inherently good or bad; it’s a lever. A mortgage on a rental property generating £20,000/year in profit is an asset, while a credit card balance at 20% APR is a drain. How to perform a net worth analysis requires distinguishing between good debt (income-generating) and bad debt (consumptive). Even student loans—often framed as a burden—can be assets if they lead to higher-earning careers. The key is calculating the debt-to-income ratio and the debt service coverage ratio (DSCR) for each liability. A DSCR below 1.25 signals financial strain; above 1.5 suggests leverage is working in your favor. Consider a freelancer with £50,000 in business loans funding a client pipeline. If those loans generate £60,000 in annual revenue, they’re an asset. But if the same loans cover personal expenses, they’re a liability. The analysis must trace each debt back to its purpose.3. Hidden Assets and Liabilities Distort the Picture
Most people overlook off-balance-sheet items—assets or debts not formally recorded. A side hustle’s unbanked cash, a partner’s undocumented contribution to a business, or a co-signed loan for a relative can skew net worth by 30% or more. How to perform a net worth analysis with integrity means auditing: - Unreported income (e.g., gig economy earnings, rental income from Airbnb) - Informal loans (e.g., money lent to friends/family without contracts) - Deferred compensation (e.g., stock options, restricted shares) - Joint accounts where liability isn’t clear-cut A high-net-worth individual might exclude a £100,000 art collection because it’s held in a trust, but that trust’s terms could restrict liquidity. The analysis must account for both the asset’s value and its accessibility.4. Time Horizon Changes Everything
A net worth statement today may look strong, but if assets are illiquid and liabilities are short-term, it’s a ticking time bomb. How to perform a net worth analysis effectively means stress-testing three scenarios: 1. Immediate liquidity: Can you cover six months of expenses if laid off tomorrow? 2. Mid-term shocks: What if a major asset (e.g., rental property) becomes unrentable? 3. Long-term inflation: Will your pension or investments outpace rising costs? A tech executive with £2 million in stock options might have a high net worth on paper, but if those options vest over 10 years, their real-time liquidity is near zero. The analysis must align assets with time-sensitive goals—retirement, education, or legacy planning.5. Tax and Legal Structures Alter the Equation
A £5 million portfolio isn’t the same as a £5 million portfolio held in a tax-efficient trust or limited liability company. How to perform a net worth analysis requires factoring in: - Capital gains taxes on asset sales - Estate taxes on inherited wealth - Corporate tax liabilities if assets are held through a business - Currency risk for international holdings For instance, selling a £1 million property might yield £800,000 after taxes and fees—reducing net worth by 20%. Meanwhile, holding it in a family trust could preserve more value for heirs. The analysis must quantify these hidden costs before they erode wealth.
How These Facts Connect
The five elements above don’t operate in isolation. They intersect in ways that define financial resilience. A high net worth on paper can mask liquidity risks, while a low net worth might hide strategic leverage. How to perform a net worth analysis with depth means seeing these connections: - Asset liquidity and debt structure determine survival in downturns. A portfolio heavy in illiquid assets (e.g., private equity) with high-interest debt is vulnerable to rate hikes. - Hidden liabilities (like co-signed loans) can offset apparent wealth. A £3 million balance sheet might shrink to £1.5 million if £1.5 million is contingent obligations. - Time horizon dictates risk tolerance. A 30-year-old can afford volatile assets; a 65-year-old cannot. The analysis must reflect this. The most revealing metric isn’t net worth itself, but its velocity—how quickly it can be converted to cash without penalty. A £10 million portfolio with £1 million in liquid assets behaves differently than one with £9 million tied up in real estate.| Factor | Impact on Net Worth | Example | Analysis Requirement |
|---|---|---|---|
| Asset Liquidity | Determines crisis survival | Private equity vs. cash savings | Tiered valuation by liquidity |
| Debt Classification | Distinguishes leverage from burden | Mortgage on rental property vs. credit card | DSCR and debt purpose tracing |
| Hidden Items | Can skew results by 30%+ | Unreported freelance income | Full disclosure audit |
| Time Horizon | Influences risk and liquidity needs | Stock options vesting in 5 years | Stress-testing scenarios |

Conclusion
How to perform a net worth analysis isn’t about crunching numbers—it’s about uncovering financial truth. The process reveals where wealth is concentrated, where risks lurk, and where opportunities lie. Done poorly, it’s a vanity metric. Done right, it’s a roadmap. The most sophisticated analysts don’t stop at a single snapshot. They track net worth over time, adjusting for inflation, market shifts, and personal changes. A £1 million net worth in 2010 might be worth £700,000 today after taxes and depreciation. The analysis must account for this erosion. Similarly, a £500,000 portfolio growing at 8% annually will outpace one stagnating at 2%. The goal isn’t just to measure—it’s to optimize.Comprehensive FAQs
Q: How often should I update my net worth analysis?
A: Quarterly for active investors, annually for stable portfolios. Major life events (marriage, inheritance, job change) require immediate updates. Asset classes like crypto or private equity may need monthly reviews due to volatility.
Q: Can I perform a net worth analysis without professional help?
A: Yes, but accuracy depends on thoroughness. Free tools like Mint or YNAB handle basic tracking, but complex assets (real estate, trusts) require appraisals or legal reviews. For precision, combine DIY tracking with periodic professional audits.
Q: How do I value intangible assets like a business or brand?
A: Use multiples of earnings (e.g., 3x annual profit for small businesses) or discounted cash flow (DCF) models. For personal brands, estimate monetization potential (sponsorships, merchandise) but avoid overinflating sentimental value.
Q: Does student debt count as a liability in net worth analysis?
A: Yes, but its impact varies. Federal loans with income-driven repayment plans may reduce monthly burdens, while private loans at high interest rates are pure liabilities. Factor in potential career earnings to assess net benefit.
Q: What’s the biggest mistake people make in net worth analysis?
A: Overvaluing assets and underestimating liabilities. Common errors include using purchase prices for depreciating assets (e.g., cars, electronics) or ignoring off-balance-sheet obligations (e.g., co-signed loans). Always use market values, not book values.
Q: How does inflation affect net worth over time?
A: Inflation erodes purchasing power faster than nominal growth. A £1 million net worth in 2020 might buy 20% less in 2024 due to rising costs. Adjust figures using the Consumer Price Index (CPI) for long-term comparisons.
Q: Should I include my spouse’s or partner’s finances in my analysis?
A: Only if assets/liabilities are legally or financially intertwined. Joint accounts, shared debts, or community property states require full integration. Otherwise, treat them as separate for clarity—unless planning for combined goals (e.g., retirement).
