Breaking Down the Numbers
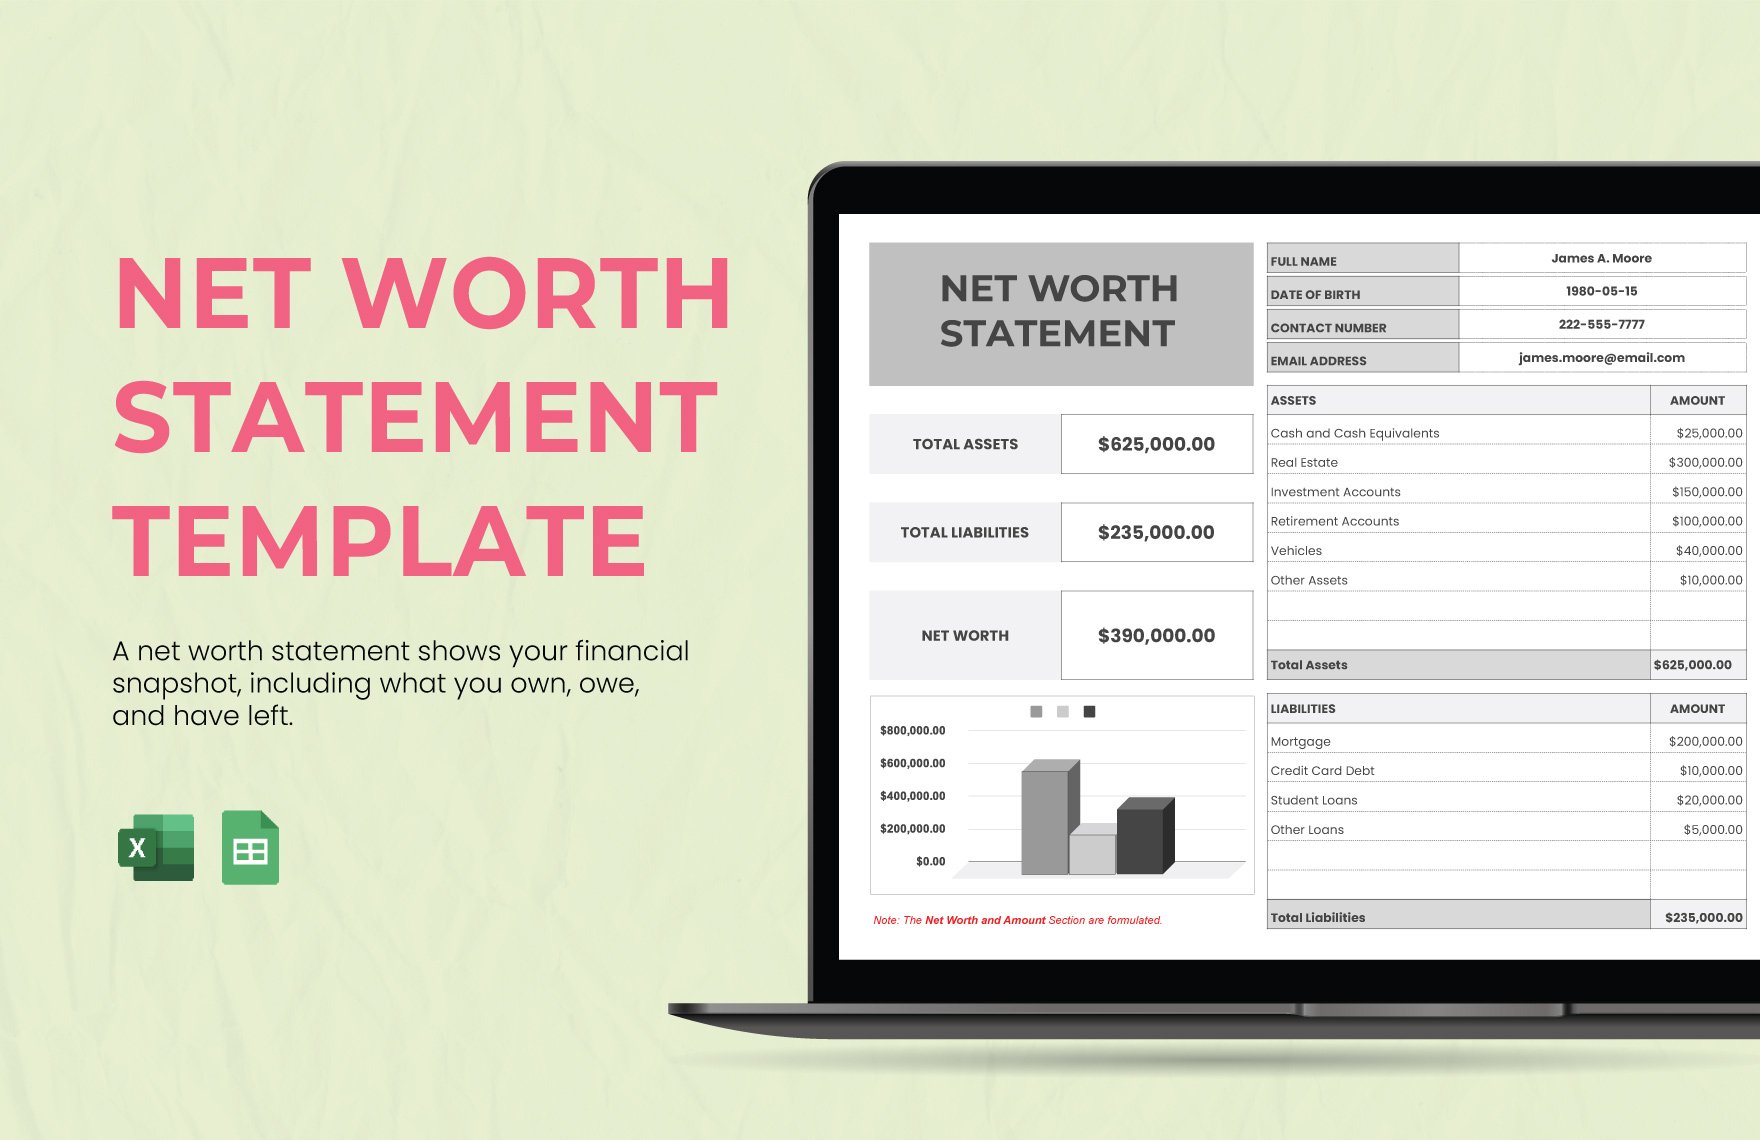
The foundation of how to obtain a statement of net worth rests on two pillars: what you own and what you owe. Assets range from liquid (cash, stocks) to illiquid (real estate, collectibles), each requiring different valuation methods. Liabilities, meanwhile, must account for both fixed debts (mortgages, loans) and contingent obligations (legal claims, unpaid taxes). The gap between these two figures—the net worth—is where precision matters most. A single misclassified asset or overlooked liability can distort the entire picture, particularly in high-stakes scenarios like estate planning or corporate acquisitions. The method you choose depends on the statement’s purpose. For personal use, a DIY approach with spreadsheets may suffice. But for legal or financial institutions, third-party verification becomes essential. Banks, for example, may accept self-certified statements for small loans, while courts often demand sworn affidavits or appraiser reports. The line between adequate and inadequate documentation is thin, and crossing it can have costly consequences. Understanding these nuances is critical to avoiding red flags that trigger deeper investigations.The Verified Baseline
Publicly available records form the bedrock of any net worth assessment. Property ownership is the most straightforward—county assessor databases list values, though these may lag behind market fluctuations. Vehicle registrations provide fair-market values, and business filings (LLCs, corporations) reveal equity stakes. For individuals, Social Security Administration records confirm retirement account balances, while IRS Form 1040 schedules detail income and deductions. These sources are verifiable, but they rarely capture the full scope of wealth, especially for those with diversified portfolios or non-traditional assets. Digital footprints also play a role. Brokerage statements from platforms like Fidelity or Vanguard are publicly accessible via court orders, and cryptocurrency exchanges may disclose holdings under subpoena. However, privacy tools like offshore accounts or anonymous trusts can obscure these trails entirely. The challenge lies in balancing transparency with the reality that some assets—like heirlooms or private investments—defy easy quantification. Even when records exist, interpreting them correctly (e.g., distinguishing between gross and net asset values) is where errors often creep in.What the Estimates Suggest
When hard data is unavailable, professional estimates become necessary. Real estate appraisers, art authentications, and business valuations provide third-party credibility, though their accuracy hinges on the appraiser’s expertise. For instance, a luxury watch collection might be valued at retail minus depreciation, while a startup’s worth could hinge on recent funding rounds or revenue projections. These estimates are rarely exact; they’re educated guesses framed by market conditions, historical data, and subjective judgments. Courts and financial institutions often accept them, but only when accompanied by clear methodologies and disclaimers. The gray area widens with intangible assets. Goodwill, patents, or brand value are notoriously difficult to quantify, yet they can dominate net worth in certain industries. Industry benchmarks or comparable sales (e.g., valuing a niche tech firm against recent acquisitions) offer a starting point, but these are inherently speculative. Even tax authorities sometimes rely on "reasonable estimates" for assets they can’t directly assess, leaving room for negotiation—or dispute. The key is to document the rationale behind every figure, ensuring the statement holds up under scrutiny.
Case Study: A Closer Look
Consider the case of a mid-career tech executive whose net worth ballooned after a successful IPO. Publicly, his LinkedIn profile listed a modest salary, but private equity stakes in his former employer, coupled with stock options, placed his net worth in the $50–70 million range—a figure far removed from his W-2 earnings. When divorce proceedings began, his spouse’s legal team demanded a statement of net worth that accounted for restricted stock units (RSUs), unvested options, and a secondary sale of shares. The executive’s initial self-report, based on liquidated assets alone, undervalued his position by nearly $20 million, triggering a contentious valuation battle. The resolution required a forensic accountant to trace the executive’s compensation history, including deferred bonuses and phantom stock awards. A table of estimated impacts clarified the discrepancies:| Factor | Estimated Impact on Net Worth |
|---|---|
| Unvested RSUs (post-IPO) | Added ~$12M (based on vesting schedule and market cap) |
| Phantom Stock Liability | Reduced net worth by ~$3M (contingent on future performance) |
| Secondary Share Sales (Private Placement) | Confirmed ~$8M in liquid assets, previously omitted |
"A net worth statement is only as good as the weakest link in its documentation. One missing RSU line can unravel months of negotiations." — Forensic Accountant, Divorce Financial Specialist
What This Means Going Forward
The rise of alternative assets—cryptocurrency, NFTs, and private credit—has complicated how to obtain a statement of net worth. Traditional methods struggle to assign values to volatile or speculative holdings. Courts are still grappling with how to treat digital assets in divorce or bankruptcy proceedings, often defaulting to "fair market value" at the time of filing. Meanwhile, high-net-worth individuals increasingly use discretionary trusts or family offices to obscure direct ownership, forcing investigators to piece together indirect evidence. The result is a growing gap between self-reported and verifiable net worth. For individuals, the takeaway is clear: proactive documentation trumps reactive scrambling. Maintaining updated appraisals, digital ledgers, and professional custody of assets reduces the risk of disputes. Financial institutions are also adapting, with some now requiring third-party verified net worth statements for loans exceeding a certain threshold. The trend reflects a broader shift toward transparency as a default, where opacity invites challenge—and costly delays.
Conclusion
The process of how to obtain a statement of net worth is part art, part science. It demands a mix of financial literacy, legal awareness, and sometimes creative problem-solving. For most people, the task begins with straightforward record-keeping—bank statements, tax returns, and property deeds—but the complexities multiply with non-liquid assets, offshore structures, or high-stakes disputes. The difference between a statement that holds up and one that fails often comes down to attention to detail: a missed liability, an undervalued asset, or an unclear valuation method can derail even the most carefully prepared document. The lesson for individuals and professionals alike is to treat net worth statements as living documents, not static snapshots. Markets change, assets appreciate or depreciate, and legal requirements evolve. Staying ahead means not just knowing how to obtain a statement of net worth but also how to defend it—whether in court, during negotiations, or under regulatory scrutiny. In an era where wealth is increasingly global and assets increasingly digital, the ability to assemble, verify, and present a net worth statement with confidence is no longer optional. It’s a necessity.Comprehensive FAQs
Q: Can I prepare a statement of net worth myself, or do I need a professional?
For personal use or low-stakes financial reviews, a DIY approach with spreadsheets and public records may suffice. However, for legal proceedings, loan applications over a certain threshold, or high-asset divorces, a certified public accountant (CPA) or forensic accountant is strongly recommended. Professionals can navigate complex assets (e.g., business equity, art collections) and ensure compliance with disclosure requirements.
Q: How often should I update my net worth statement?
There’s no universal rule, but high-net-worth individuals and those in volatile industries (tech, crypto, real estate) should review their statements quarterly or annually. For most people, an annual update aligned with tax season is practical. Major life events—divorce, inheritance, significant investments—demand immediate revisions to reflect accurate figures.
Q: What’s the difference between a net worth statement and a balance sheet?
A net worth statement is a simplified summary of assets minus liabilities, often used for personal finance or legal disclosures. A balance sheet (common in accounting) includes additional details like equity accounts, revenue streams, and operational metrics. While both serve similar purposes, balance sheets are far more granular and typically used by businesses or financial institutions.
Q: Can I be forced to disclose my net worth to a third party?
Yes, under specific circumstances. Courts may order net worth disclosures in divorce, bankruptcy, or civil litigation. Lenders may request them for large loans or credit lines. Employers might ask for how to obtain a statement of net worth during executive hiring or bonus negotiations. However, voluntary disclosures (e.g., to investors or business partners) require explicit consent.
Q: How are cryptocurrency holdings treated in a net worth statement?
Cryptocurrency is treated as an asset, valued at its fair market price on the date of the statement. For tax or legal purposes, exchanges may provide transaction histories under subpoena. However, private wallets or cold storage can complicate verification. Some jurisdictions treat crypto as property, while others classify it as currency—always check local regulations.
Q: What happens if I underreport my net worth intentionally?
Intentional misrepresentation can lead to perjury charges (if sworn under oath), civil penalties, or fraud investigations. In divorce cases, courts may impose punitive damages or adjust settlements retroactively. Financial institutions may deny loans or report discrepancies to credit agencies. The risks far outweigh the benefits of underreporting.
Q: Are there industry standards for formatting a net worth statement?
No single standard exists, but most follow a three-column format: assets (with descriptions and values), liabilities (debts, taxes owed), and net worth (assets minus liabilities). Legal documents often require signed affidavits or notary acknowledgments. For businesses, GAAP or IFRS principles may apply. Always tailor the format to the recipient’s expectations—banks prefer simplicity, while courts demand exhaustive detail.
Q: How do I handle assets with fluctuating values (e.g., stocks, real estate)?
Use the most recent verifiable value at the time of the statement. For public stocks, brokerage statements suffice. For real estate, a professional appraisal or recent sale price is ideal. If values are volatile (e.g., crypto), note the valuation date clearly. Avoid averaging or guessing—transparency is critical to avoiding disputes.
