
Common Myths About Calculating Estimated Net Worth
The first misconception is that net worth is a static figure, best calculated once a year. In reality, it’s a dynamic metric that should be tracked quarterly—or even monthly—for those with significant assets or debt. The second myth is that only the ultra-wealthy need to worry about it. In truth, a net worth calculation is the financial equivalent of a health check: it exposes imbalances before they become crises. Finally, many assume that "liquid assets" are the only ones that count, ignoring illiquid holdings like real estate or private equity that can still represent substantial value. These oversights lead to dangerous blind spots. Someone might boast about a $2 million home while carrying $1.8 million in mortgage debt, leaving them with a net worth closer to zero. Others dismiss retirement accounts as "future money," failing to recognize their present value. The core issue? Net worth isn’t about what you own—it’s about what you own after what you owe.Myth 1: "My home’s value is my net worth."
The allure of real estate as a wealth proxy is understandable—homes often represent the largest single asset for middle-class households. But conflating home equity with total net worth ignores two critical factors: leverage and liquidity. A property valued at $1 million with a $600,000 mortgage contributes only $400,000 to net worth. Worse, illiquid assets like real estate can’t be easily converted to cash during emergencies. Industry estimates suggest that over 60% of homeowners underestimate their true net worth by at least 20% when they exclude mortgage debt or fail to adjust for market volatility. The reality is more nuanced. A home’s value fluctuates with local market conditions, property taxes, and maintenance costs—none of which are reflected in a simple Zillow estimate. For accurate how to calculate estimated net worth, you must subtract all secured debts (mortgage, HELOCs) and factor in opportunity costs (e.g., the capital gains tax hit when selling). Even then, a home’s contribution to net worth is only as solid as the rental market’s demand—or the risk of a forced sale.Myth 2: "Stocks and crypto are the only assets that matter."
The tech boom and crypto hype have warped perceptions of what constitutes "real" wealth. While public equities and digital assets are highly liquid and often volatile, they’re just one slice of the asset pie. Private business ownership, collectibles (art, wine, rare stamps), and even intellectual property (patents, royalties) can represent far greater long-term value—yet they’re rarely factored into casual net worth discussions. According to a 2023 study by the Federal Reserve, households with illiquid assets (e.g., family businesses, farmland) often underreport their net worth by 30% or more when focusing solely on marketable securities. The mistake lies in treating net worth as a binary—either you’re a "stock investor" or you’re not. A farmer with $5 million in land but $2 million in equipment debt has a net worth that dwarfs a tech employee’s $1.2 million in 401(k) balances. The key to accurate how to calculate estimated net worth is recognizing that not all assets trade on an exchange, and not all liabilities are listed on a credit report.Myth 3: "Net worth is just savings minus debt."
This oversimplification ignores the time value of money and the role of appreciating assets. A $500,000 retirement account isn’t the same as $500,000 in cash—especially if the account is tax-deferred and grows annually. Similarly, student loans or business debts may carry lower interest rates than consumer debt, altering their true cost. The Federal Reserve’s Survey of Consumer Finances found that households adjusting for asset appreciation see their net worth inflate by 15–25% annually, even without new income. The flaw in the "savings minus debt" model is that it treats all debt equally and all assets as equivalent. A $100,000 car loan at 8% interest erodes net worth far faster than a $500,000 mortgage at 3%—yet both are often lumped together. For precise how to calculate estimated net worth, you must categorize debts by interest rate, assets by growth potential, and liabilities by enforceability (e.g., alimony vs. medical bills).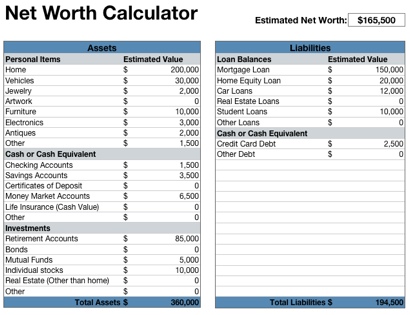
What Holds Up to Scrutiny
At its core, net worth is a simple equation: total assets minus total liabilities. But the challenge lies in defining "assets" and "liabilities" with surgical precision. Assets include everything from cash and investments to tangible property and intangible rights (e.g., a book’s advance payments). Liabilities encompass not just loans but also future obligations like child support, pending lawsuits, or even the cost of caring for aging parents. The verifiable truth? Net worth isn’t a guess—it’s a calculation grounded in documented values. The catch? Values aren’t static. A 2022 Bank of America study revealed that net worth calculations can vary by 10–15% depending on whether you use book value (original cost) or market value (current worth). For example, a vintage car might be worth $50,000 to a collector but only $10,000 to a junkyard. The solution? Use conservative estimates for illiquid assets and real-time valuations for liquid ones (e.g., checking your 401(k) balance weekly)."Net worth is the financial equivalent of a balance sheet—except most people treat it like a suggestion rather than a mandate. The difference between a $1 million and a $500,000 net worth isn’t just money; it’s risk tolerance, liquidity, and peace of mind." — Jane D. Parker, CFA and author of The Wealth Equation
| Common Belief | What the Evidence Says |
|---|---|
| Retirement accounts are "future money" and shouldn’t count toward current net worth. | They represent present value—even if locked until age 59½. A $1M IRA is worth ~$700K after taxes if withdrawn early. |
| Credit card debt is the only liability that matters. | High-interest debt (e.g., payday loans, private student loans) can erode net worth faster than mortgages or auto loans. |
| Real estate is always a net worth booster. | Only equity (home value minus mortgage) counts. A $1M home with $900K debt adds $100K to net worth—not $1M. |
Why the Confusion Persists
Two forces distort how people approach how to calculate estimated net worth. First, social comparison bias: seeing others flaunt luxury purchases without disclosing debt creates a skewed perception of wealth. Second, financial literacy gaps: many lack the tools to distinguish between "net worth" (assets minus liabilities) and "gross worth" (assets alone). Even financial advisors sometimes conflate the two, leading clients to believe they’re richer than they are. The result? A culture where net worth is treated as a secret handshake—something only the "financially elite" understand. In truth, the formula is straightforward, but the execution demands discipline. Without it, even high earners can wake up with a net worth lower than they assumed, thanks to hidden debts or overvalued assets.
Conclusion
Calculating your estimated net worth isn’t about chasing a number—it’s about gaining control. The most accurate how to calculate estimated net worth starts with honesty: listing every asset, every liability, and every pending obligation. It requires recognizing that a $200,000 car collection might be worth $50,000 in reality, or that a $1.5M home with $1.2M in debt is a liability trap. The goal isn’t to hit an arbitrary target (e.g., "I need $1M to retire") but to understand your true financial position—so you can make decisions accordingly. The irony? The people who obsess over net worth are often the ones who miscalculate it. The rest—those who treat it as a living document—build wealth quietly, without the noise. The first step? Stop guessing. Start calculating.Comprehensive FAQs
Q: How often should I update my net worth calculation?
At minimum, quarterly. If you have significant assets (e.g., stocks, real estate) or debt (e.g., business loans, mortgages), track it monthly. Market fluctuations, new debts, or large purchases can shift your net worth faster than you think.
Q: Do I need to include my spouse’s or partner’s assets/debts?
Only if they’re legally yours (e.g., joint accounts, co-signed loans). For separate finances, calculate net worth individually. If you’re married but track separately, note that combined net worth (yours + partner’s) is often the more useful metric for major life goals (e.g., buying a home, retirement).
Q: How do I value illiquid assets like a family business or art collection?
Use conservative estimates:
- Family business: Appraise based on replacement cost or earnings multiple (e.g., 3–5x annual profit).
- Art/collectibles: Check recent auction sales (e.g., Artsy, Sotheby’s) or get a professional appraisal.
- Rental property: Subtract mortgage, taxes, and maintenance costs from rental income to estimate net operating income, then apply a cap rate (e.g., 6–8%).
Q: Should I include pending lawsuits or future inheritances in my net worth?
No. Net worth is a snapshot of current assets and liabilities. Pending lawsuits (even if likely to win) are speculative, and inheritances aren’t yours until received. However, if you’re certain of an inheritance (e.g., a parent’s will), you may include it as a contingent asset—but label it clearly to avoid overstating your position.
Q: What’s the difference between net worth and cash flow?
Net worth = what you own minus what you owe (a static measure). Cash flow = income minus expenses (a dynamic measure). A high net worth but negative cash flow means you’re living off assets (e.g., renting out property but spending all rental income). A low net worth but positive cash flow means you’re building wealth over time (e.g., saving aggressively). Both matter—but they answer different questions.
Q: Can I calculate net worth for a business separately from personal finances?
Yes. Business net worth = business assets (equipment, inventory, cash) minus business liabilities (loans, payables). Personal net worth = personal assets (home, investments) minus personal liabilities (mortgage, credit cards). Some assets (e.g., a home used for business) may split between both. For accuracy, keep records separate.
