
The Complete Overview of How to Find Net Assets
Net assets are the residual value after subtracting all liabilities from total assets. For individuals, this is often called net worth; for businesses, it’s shareholders’ equity. The calculation is deceptively straightforward—assets minus liabilities—but the devil lies in the definitions. Assets aren’t just cash; they include tangible property (real estate, vehicles), intangible assets (patents, goodwill), and financial instruments (stocks, bonds). Liabilities, meanwhile, encompass mortgages, loans, credit card debt, and even future obligations like lease commitments. The challenge amplifies when assets are illiquid or hard to value. A family-owned vineyard might be worth $20 million on paper, but if it’s encumbered by a $15 million loan and the wine market is soft, its net contribution could be negligible. Similarly, a tech startup’s "assets" might include unproven IP—valuable only if the company secures funding or acquires a buyer. The process requires not just arithmetic but an understanding of market dynamics, legal structures, and tax implications. Even a minor misclassification—like treating a deferred tax asset as current—can skew results by millions. For professionals, the task often involves cross-referencing multiple sources. Public companies disclose net assets in annual reports (under "shareholders’ equity"), but private entities may require third-party appraisals. Personal net worth calculations, meanwhile, demand tracking everything from 401(k) balances to the depreciated value of a vintage car. The key is consistency: using the same valuation methodology across all assets to avoid inconsistencies that could mislead stakeholders or regulators. Industry standards vary by jurisdiction. In the U.S., the IRS provides guidelines for reporting net worth in tax filings, while the UK’s HMRC has specific rules for capital gains tax. For businesses, frameworks like IFRS or GAAP dictate how assets and liabilities are recognized. The lack of uniformity means that how to find net assets isn’t a one-size-fits-all problem—it’s a puzzle that changes based on legal, geographic, and operational contexts.Historical Background and Evolution
The concept of net assets traces back to medieval merchant ledgers, where traders recorded assets (gold, spices) against debts (loans, trade credits). By the 17th century, European banks formalized balance sheets to assess solvency, laying the groundwork for modern accounting. The Industrial Revolution accelerated the need for precise asset valuation as companies issued shares and bonds, requiring transparent equity calculations. By the 20th century, corporate net assets became a cornerstone of financial reporting, with the rise of limited liability companies demanding clear distinctions between assets and liabilities. The digital age has rewritten the rules. The 1990s saw the dot-com boom, where intangible assets (brand value, user bases) inflated net worth calculations—only to collapse when revenue failed to materialize. The 2008 financial crisis exposed gaps in mortgage-backed securities valuation, revealing how off-balance-sheet liabilities could hide true net asset positions. Today, the integration of digital assets complicates matters further. A 2021 report by the Bank for International Settlements noted that cryptocurrency holdings, while technically assets, lack standardized valuation methods, creating volatility in net worth assessments. For individuals, the evolution has been equally transformative. The post-WWII era saw the rise of homeownership as a primary asset class, while the 1980s bull market popularized stock portfolios. The 2010s introduced gig economy earnings and peer-to-peer lending as new asset categories. Each shift forces a reevaluation of how to find net assets, as traditional metrics (like the "three asset classes" model) fail to capture modern financial ecosystems. The lesson? Net assets aren’t static; they’re a living snapshot of economic conditions, regulatory changes, and personal or corporate strategy.Core Mechanisms: How It Works
At its core, the net asset calculation follows a hierarchical approach. First, identify all assets: cash, securities, real estate, personal property, and even intellectual property like trademarks. Each must be valued at its fair market value—the price a willing buyer would pay in an arm’s-length transaction. For publicly traded stocks, this is straightforward; for a private business, it may require a discounted cash flow analysis or comparable company multiples. Liabilities follow the same logic: mortgages are clear, but contingent liabilities (like lawsuits) require estimates based on legal advice. The second step is categorization. Assets are often divided into current (convertible to cash within a year) and non-current (long-term investments). Liabilities follow suit: current (due within a year) and long-term. This separation is critical for liquidity analysis. A business with $100 million in real estate but $90 million in long-term debt may appear solvent on paper but struggle with short-term obligations. The net asset figure emerges only after netting these categories—current assets minus current liabilities, plus non-current assets minus non-current liabilities. Technology has streamlined parts of this process. Wealth management platforms now auto-categorize brokerage accounts and retirement funds, while AI tools can flag anomalies (e.g., a sudden spike in credit card debt). However, human oversight remains essential. An algorithm might miss a pending lawsuit or an undervalued collectible. The most reliable methods combine digital tools with manual reviews, especially for high-value or complex assets. For businesses, auditors often use workpapers—detailed documentation of asset valuations—to justify net asset figures to stakeholders.Key Benefits and Crucial Impact
Understanding how to find net assets isn’t just an academic exercise—it’s a strategic imperative. For individuals, net worth serves as a benchmark for financial health, influencing everything from mortgage approvals to college funding plans. A net asset shortfall can trigger insolvency risks, while a surplus enables leverage for investments or philanthropy. Businesses use net asset data to secure loans, attract investors, or plan acquisitions. Even governments rely on net asset calculations to assess national wealth, though political factors often distort these figures. The impact extends beyond finance. Net assets determine eligibility for trusts, influence divorce settlements, and affect tax liabilities. A misclassified asset—like a rental property treated as personal use—can trigger audits or penalties. For entrepreneurs, net asset transparency builds credibility with lenders and partners. The ability to accurately determine net assets separates opportunistic gambles from calculated growth strategies. > "Net assets are the silent language of financial credibility. Whether you're a startup founder or a family office, the numbers don’t lie—but the interpretations often do." — James Altucher, Investor and AuthorMajor Advantages
- Financial Clarity: A precise net asset calculation reveals true wealth, not just surface-level liquidity. This clarity helps in budgeting, risk management, and long-term planning.
- Investor Confidence: Public companies with transparent net asset disclosures attract more capital. Private entities benefit similarly when presenting to venture capitalists or private equity firms.
- Tax Optimization: Accurate asset valuation ensures compliance with capital gains, inheritance, and property taxes. Undervaluing assets can lead to audits; overvaluing may trigger unnecessary tax burdens.
- Risk Mitigation: Identifying hidden liabilities—such as unfunded pension obligations or environmental cleanup costs—prevents financial shocks.
- Estate Planning: Net assets determine inheritance strategies. A well-documented net worth statement simplifies probate and ensures heirs receive intended assets.

Comparative Analysis
| Individual Net Worth | Corporate Net Assets |
|---|---|
| Focuses on personal liabilities (credit cards, mortgages) and assets (real estate, investments). | Includes shareholders’ equity, retained earnings, and off-balance-sheet items like lease obligations. |
| Valuation relies on market data and personal appraisals (e.g., home values from Zillow). | Requires audited financial statements and industry-specific metrics (e.g., goodwill impairment tests). |
| Updated annually or quarterly, often manually. | Reported quarterly/annually under GAAP/IFRS, with third-party audits. |
| Primary use: Personal financial planning, loan applications. | Primary use: Investor relations, M&A due diligence, regulatory filings. |
| Challenges: Subjective valuations (e.g., art, collectibles). | Challenges: Intangible assets (brand value), contingent liabilities. |
Future Trends and Innovations
The next decade will redefine how to find net assets, driven by three forces: tokenization, regulatory tech (RegTech), and behavioral finance. Tokenized assets—where real estate, art, or even carbon credits are represented as blockchain-based securities—will introduce new valuation challenges. Smart contracts could automate net asset calculations in real time, but only if standardized valuation protocols emerge. RegTech, meanwhile, is already enabling AI-driven compliance checks, reducing errors in liability reporting. Behavioral shifts will also play a role. The rise of "quiet luxury" spending—where individuals prioritize experiences over assets—may reduce traditional net worth metrics. Meanwhile, the gig economy’s fragmented income streams complicate asset tracking. Future net asset calculations will likely incorporate liquidity scores, ranking assets by how quickly they can be converted to cash, not just their nominal value. For businesses, ESG (Environmental, Social, Governance) metrics may become as critical as financial net assets, with investors demanding transparency on sustainability-linked liabilities. The biggest wild card? Central Bank Digital Currencies (CBDCs). If adopted widely, CBDCs could reclassify cash as a digital asset, altering how net worth is computed. Banks might no longer hold physical reserves, forcing a rethink of liquidity-based asset valuations. The question isn’t whether these changes will happen—but how quickly institutions and individuals adapt to new methods of determining net assets in a digital-first economy.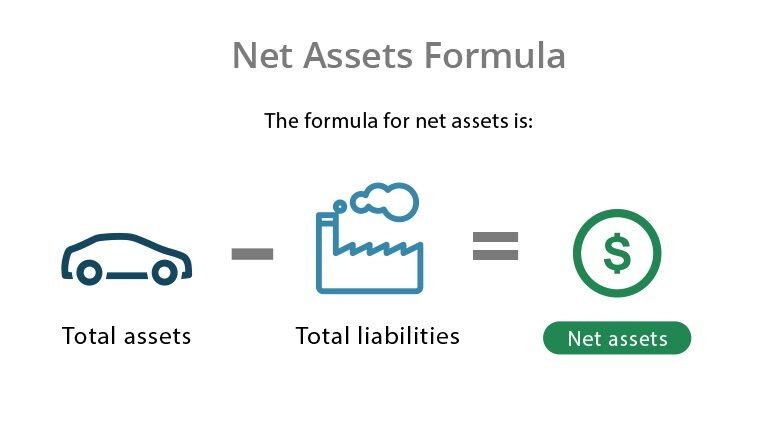
Conclusion
Mastering how to find net assets is less about memorizing formulas and more about developing a framework that evolves with financial complexity. The tools exist—spreadsheets, auditors, AI—but their effectiveness hinges on context. A luxury watch collector’s net worth isn’t just the sum of Rolex prices; it’s the liquidity of those assets in a recession. A tech CEO’s net assets aren’t just stock options; they’re the untested potential of unlaunched products. The process demands humility, as even the most rigorous calculations can be upended by black swan events. The takeaway? Net assets are a snapshot, not a destination. They must be recalculated regularly, with an eye toward both precision and adaptability. For individuals, this means annual reviews; for businesses, it’s continuous disclosure. The goal isn’t perfection—it’s a dynamic understanding of what net assets truly represent: not just numbers, but the foundation of financial strategy.Comprehensive FAQs
Q: What’s the simplest way to calculate personal net worth?
A: Start with a spreadsheet. List all assets (cash, investments, property) at their current market value, then subtract all liabilities (debts, mortgages, taxes owed). Use tools like Personal Capital or Mint for automation, but verify manual entries—especially for illiquid assets like art or private business stakes. Recalculate quarterly to track trends.
Q: How do businesses value intangible assets like patents or brand equity?
A: Intangible assets are typically valued using three methods: income approach (projecting future cash flows), market approach (comparing to similar sold assets), or cost approach (original development costs adjusted for depreciation). For patents, the income method is common; for brands, licensing revenue or royalty rates may apply. Auditors often use a weighted average of these methods to justify valuations in financial statements.
Q: Can digital assets (crypto, NFTs) be included in net asset calculations?
A: Yes, but with caveats. Cryptocurrencies should be valued at their fair market value on the day of calculation (e.g., Bitcoin’s price on CoinMarketCap). NFTs are trickier—use recent sale prices for similar pieces or appraise based on utility (e.g., access to exclusive events). The IRS treats crypto as property, so gains/losses must be tracked for tax purposes. However, extreme volatility means these assets should be recalculated frequently.
Q: What’s the most common mistake people make when calculating net assets?
A: Overvaluing illiquid assets or ignoring hidden liabilities. For example, listing a home at its peak purchase price instead of current market value, or forgetting to include pending legal judgments or deferred tax liabilities. Another pitfall is double-counting assets (e.g., including both a retirement account and its underlying investments). Always cross-check with a third party—like a CPA or financial advisor—for high-value holdings.
Q: How often should net assets be recalculated?
A: Individuals should review net worth annually, or after major life events (marriage, inheritance, job changes). Businesses must update net asset figures quarterly or annually, depending on regulatory requirements (e.g., public companies file 10-Q/10-K reports). Digital assets and volatile markets may require monthly checks. The frequency depends on the entity’s complexity—high-net-worth individuals or public companies need more rigorous tracking than average consumers.
Q: Are there industry-specific tools for calculating net assets?
A: Yes. Real estate investors use comps analysis (comparable sales) and cap rate calculators. Tech startups rely on pre-money/post-money valuation models tied to funding rounds. Financial advisors leverage wealth management software (e.g., Black Diamond, eMoney) to track diversified portfolios. For businesses, ERP systems (like SAP or Oracle) integrate asset and liability tracking. The right tool depends on the asset class—no single solution fits all scenarios.
