6 Things Worth Knowing About How to Create an Excel Sheet That Tracks Your Net Worth
The most common mistake isn’t technical; it’s conceptual. People treat net worth as a static balance sheet when it’s actually a living document. A tracker that works requires six foundational principles: asset granularity, liability tiering, automation triggers, projection layers, security protocols, and adaptability to life stages. Skip any of these, and the sheet becomes a relic by next year.1. Assets Should Be Categorized by Liquidity, Not Just Type
Most templates lump everything into "cash" and "investments," but that obscures reality. A high-yield savings account isn’t the same as a 401(k) match, and a rental property’s value isn’t its liquidation potential. The key is three-tiered categorization: - Immediate liquidity (checking, HYSA, CD ladder) - Short-term liquidity (brokerage accounts, money market funds) - Illiquid assets (real estate, private equity, collectibles) Why? Because a sudden expense—say, a $20,000 emergency—shouldn’t force you to sell a rental property at a loss. The sheet must reflect time-to-cash, not just nominal value. Use conditional formatting to flag illiquid assets in red, with a note on estimated sale timelines.2. Liabilities Need Weighted Valuation, Not Face Value
A $300,000 mortgage isn’t just a liability; it’s a leveraged asset if the property appreciates. The sheet must distinguish between: - Discretionary debt (credit cards, personal loans) - Strategic debt (mortgages, student loans with tax benefits) - Non-recourse liabilities (lease obligations, co-signed debts) Pro tip: Assign a "net debt" column where strategic debt is reduced by its tax shield (e.g., mortgage interest deductions). This turns a negative into a neutral or even positive contributor to net worth—if structured correctly.3. Automation Is Non-Negotiable for Monthly Updates
Manual entry is the fastest way to abandon the sheet by February. The solution? Three layers of automation: 1. Data pulls: Use Excel’s `IMPORTXML` or Power Query to pull account balances from banks (if APIs are available). 2. Formula triggers: Set up `IF` statements to auto-categorize new transactions (e.g., "Any deposit over $5K → 'Investment Income'"). 3. Alert systems: Conditional formatting to highlight when an asset drops below a threshold (e.g., "Cash reserve < 3 months of expenses"). Even a basic `=VLOOKUP` can save hours. The sheet should require less than 10 minutes of active work per month.4. Projections Are More Valuable Than Historical Data
A net worth tracker without a "what-if" layer is just a ledger. The most powerful sheets include: - Inflation-adjusted columns (e.g., "Projected Home Value in 5 Years") - Scenario modeling (e.g., "If I max out 401(k) contributions, net worth grows X% annually") - Debt payoff accelerators (e.g., "Aggressive vs. snowball method impact") Blockquote: "A net worth sheet without projections is like a car without a dashboard—you know where you’ve been, but not where you’re headed." — Morgan Housel, The Psychology of Money Use Excel’s `FORECAST.ETS` function to predict asset growth based on historical trends, then stress-test with 10% market drops or 20% inflation spikes.5. Security and Backup Are Often an Afterthought
Password-protecting a sheet isn’t enough. The real risks are: - Version control (accidentally overwriting last year’s data) - Accessibility (who else needs read-only permissions?) - Disaster recovery (cloud vs. local backups) Solution: Store the master file in two places (Google Drive + encrypted local drive) with version history enabled. For sensitive data, use Excel’s `Password Protect Workbook` feature, but avoid storing passwords in the file itself.6. The Sheet Must Evolve with Your Life Stages
A 25-year-old freelancer’s tracker differs from a 45-year-old homeowner’s. The sheet should include: - Life-stage triggers (e.g., "Add 'College Fund' column when children are born") - Role-based views (e.g., spouse vs. accountant access levels) - Legacy planning (e.g., "Estate liquidity" calculations for heirs) The best trackers have a "Future Me" tab where you outline upcoming changes (e.g., "Refinance mortgage in Q3 2025") and their projected impact.
How These Facts Connect
The six principles above aren’t isolated; they form a feedback loop. Categorizing assets by liquidity directly informs how liabilities are weighted, which in turn dictates what automation rules you need. Projections rely on accurate historical data, which requires security protocols to trust. And the sheet’s adaptability ensures it doesn’t become obsolete when your circumstances change. The table below compares the most critical elements side by side, revealing how they interact:| Element | Purpose | Excel Function/Tool | Common Pitfall | Pro Tip |
|---|---|---|---|---|
| Asset Liquidity Tiers | Prevents forced illiquid sales | Conditional formatting + color scales | Overestimating real estate liquidity | Add a "Days to Sell" column |
| Weighted Liabilities | Accurately reflects net worth | Nested IF + tax deduction formulas | Ignoring mortgage interest shields | Use `=MAX(0, [Debt] - [Tax Benefit])` |
| Automation Layers | Reduces manual errors | Power Query + IMPORTXML | Over-automating without safeguards | Set up monthly email alerts for errors |
| Scenario Projections | Tests resilience to shocks | FORECAST.ETS + Data Tables | Over-optimistic growth assumptions | Run "best-case" and "worst-case" side by side |
| Security Protocols | Prevents data loss | File encryption + version history | Single-point failure (e.g., cloud-only) | Use OneDrive’s "Personal Vault" for sensitive sheets |
Conclusion
Creating an Excel sheet that tracks your net worth isn’t about building a static ledger; it’s about constructing a dynamic financial operating system. The difference between a sheet that’s used and one that’s abandoned comes down to three things: structure (how it’s organized), automation (how it updates itself), and adaptability (how it grows with you). Start with the six principles outlined above, then refine as you go. The first version won’t be perfect—and that’s the point. The goal is a tool that evolves alongside your goals, not a monument to spreadsheet perfection. Begin with what you know, automate what you can, and adjust as your life changes. The numbers will follow.Comprehensive FAQs
Q: Can I use a free template from the internet and modify it?
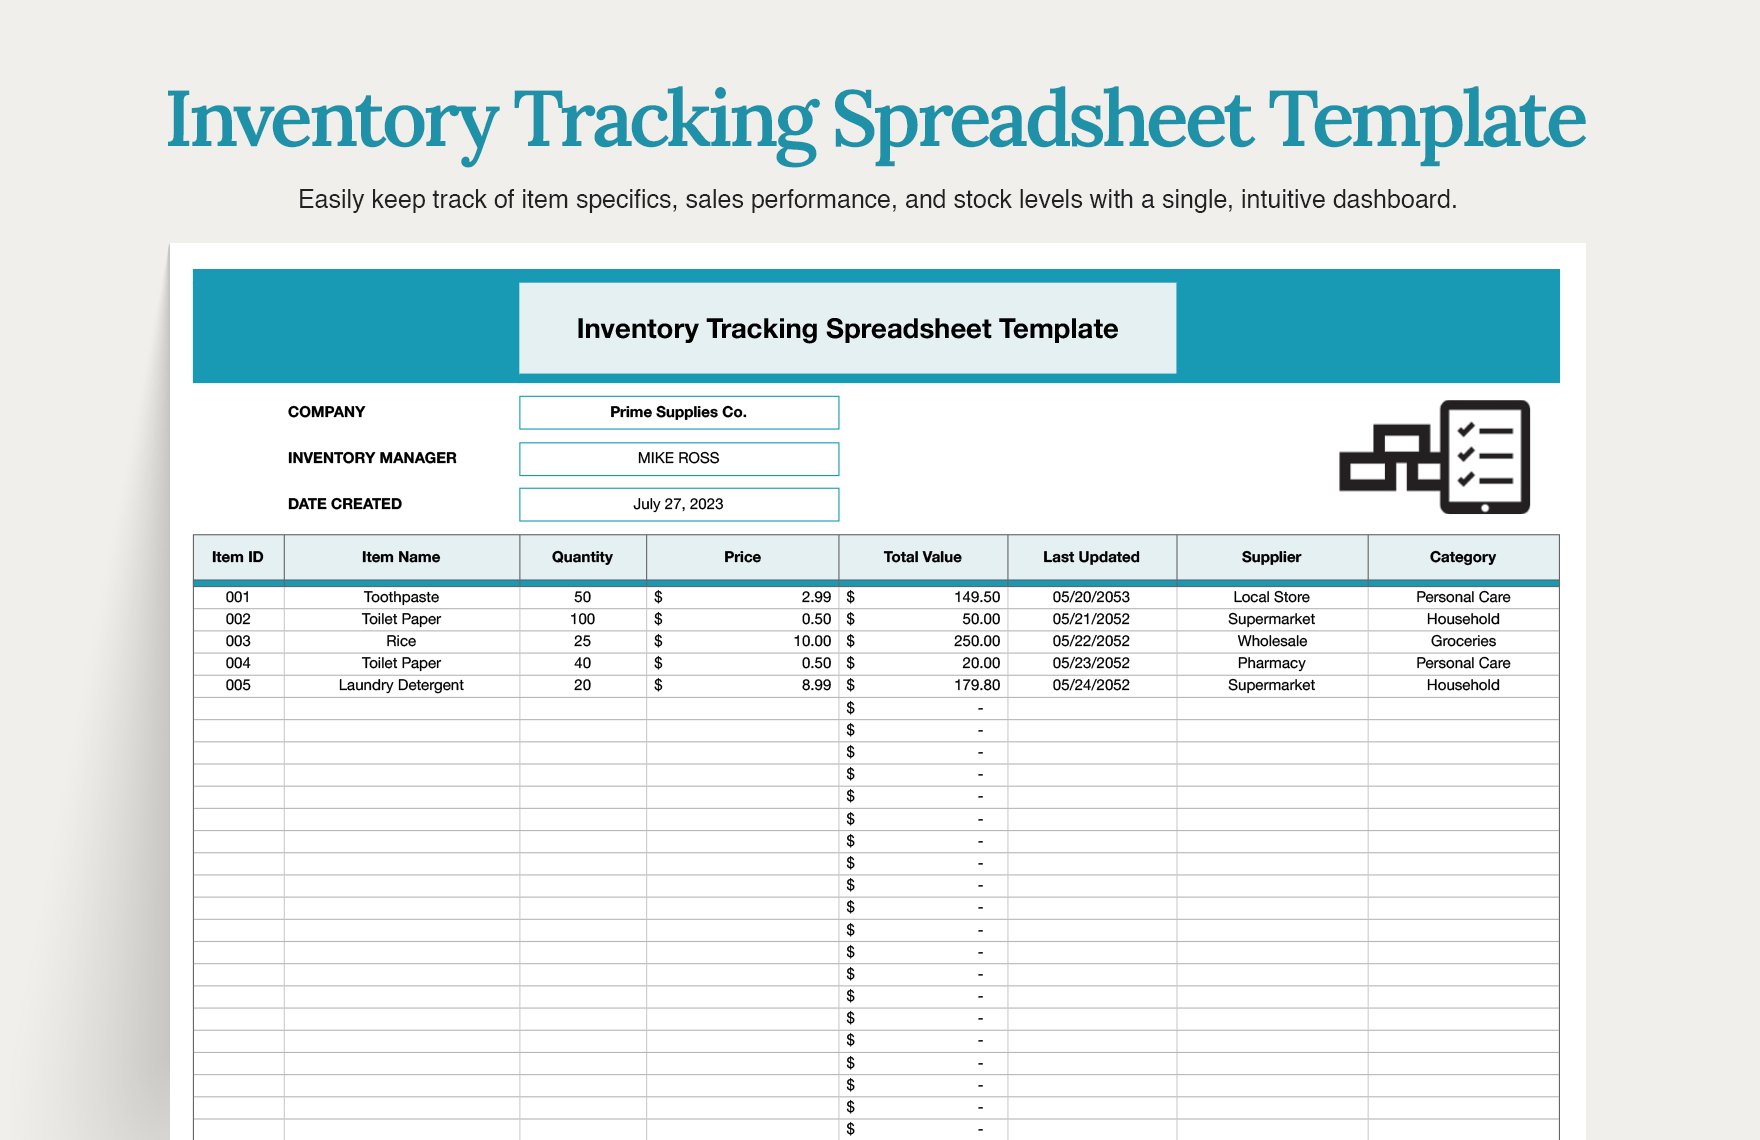
A: Yes, but with caution. Most free templates lack liquidity tiering or projection layers, which are critical for accuracy. Start with a blank sheet and build the six core elements yourself—it takes longer but ensures the tool fits your needs. If you must use a template, audit it first: Does it distinguish between strategic and discretionary debt? Can you easily add new asset classes?
Q: How often should I update my net worth tracker?
A: Monthly, but with a focus on quarterly deep dives. Monthly updates ensure you catch fluctuations (e.g., stock market dips, new loans), while quarterly reviews let you reconcile discrepancies, adjust projections, and spot trends. Automate the monthly pulls for balances, but manually verify illiquid assets (like property values) quarterly.
Q: What’s the best way to handle assets with fluctuating values (e.g., crypto, art)?h3>
A: Use a "Cost Basis vs. Market Value" split. For crypto, pull real-time prices via `IMPORTXML` from CoinGecko or CoinMarketCap. For art, create a "Valuation Notes" column where you document appraisals or auction results. Never rely on a single snapshot—track the high, low, and average over the past year to smooth volatility.
Q: Should I share my net worth tracker with my spouse or accountant?
A: Yes, but with access controls. Use Excel’s "Review" tab to set view-only permissions for non-editors. For accountants, export a redacted version (e.g., hide exact credit card balances) and use `PROTECT SHEET` to lock critical formulas. Never share login credentials to linked accounts—only the finalized Excel file.
Q: How do I handle inherited assets or gifts in the tracker?
A: Create a "Source of Funds" column to flag non-earned assets. For inheritances, note the date acquired and basis (e.g., stepped-up cost basis for real estate). Gifts should be tracked separately from earned income to avoid overstating liquidity. Use a separate tab for "Non-Operational Assets" to avoid mixing them with active wealth-building tools.
Q: What’s the most common mistake people make when building their first tracker?
A: Underestimating the time cost of maintenance. A tracker that requires 30 minutes of manual work monthly will get abandoned. The fix? Prioritize automation—even if it’s just setting up a `SUMIF` formula to auto-categorize transactions. Start small: Track only the top 80% of your assets (by value) first, then expand. Perfection is the enemy of progress.
