
The Complete Overview of the David Bowie Bond
The Bowie bond was the brainchild of Bowie’s estate, led by his longtime collaborator and widow, Angela Barnett, and financial advisors including Wilbur Ross’s WL Ross & Co. The bond’s issuance in 2017 marked the first time a royalty-backed security was offered to institutional investors, with proceeds reportedly exceeding $100 million. The instrument was structured as a streaming bond, meaning payments were tied to Bowie’s future earnings rather than a fixed coupon. This innovation allowed investors to participate in the ongoing value of his catalog without owning the rights outright. What made the Bowie bond distinctive was its dual appeal: it satisfied Wall Street’s demand for yield while catering to cultural investors who saw value in Bowie’s enduring influence. The bond’s success also highlighted a broader trend in finance—the rise of asset-backed securities tied to intellectual property. Unlike traditional bonds, which rely on corporate balance sheets, the Bowie bond’s security came from Bowie’s music itself. This shift reflected a growing recognition that creative assets could be as reliable as physical collateral, provided they were properly structured.Historical Background and Evolution
The concept of securitizing royalties predates Bowie, but his bond was the first to achieve mainstream legitimacy. Earlier attempts, such as the 1980s music royalties-backed loans, were often opaque and targeted niche investors. Bowie’s bond, however, was transparent, rated by agencies like Moody’s, and marketed to institutions. This transparency was crucial: it signaled that royalty streams could be treated as a legitimate asset class, akin to mortgages or corporate debt. The bond’s structure was a response to Bowie’s estate’s need for liquidity. While his catalog generated steady income, the estate required capital for litigation, taxes, and administrative costs. By issuing the bond, the estate unlocked immediate funds while deferring payments until future royalties materialized. This approach mirrored asset-backed lending in other industries, but with a twist: the collateral was immaterial yet perpetually valuable. The bond’s success also set a precedent for other estates—from Prince to The Beatles—to explore similar financial strategies.Core Mechanisms: How It Works
At its core, the Bowie bond functioned like a collateralized loan, where Bowie’s future royalties served as security. Investors purchased the bond at a discount, with repayment tied to a percentage of Bowie’s annual earnings. The bond’s waterfall structure ensured that investors were paid only after Bowie’s estate covered its obligations, such as taxes and legal fees. This priority-of-payments model reduced risk for investors, as it mirrored the seniority of secured debt. The bond’s pricing reflected Bowie’s catalog’s projected earnings, which were audited by third parties to ensure accuracy. This transparency was a departure from traditional royalty loans, where valuations were often subjective. By attaching a market-determined value to Bowie’s music, the bond created a benchmark for future royalty-backed securities. The transaction also involved a trust mechanism, where a third party managed distributions to investors, ensuring compliance with financial regulations.Key Benefits and Crucial Impact
The Bowie bond’s most immediate impact was financial: it provided the estate with a multi-hundred-million-dollar infusion without diluting ownership of the catalog. For investors, it offered a stable, high-yield alternative to traditional fixed-income assets, with returns tied to Bowie’s enduring popularity. The bond also demonstrated that cultural capital could be quantified and traded, paving the way for similar instruments in sports, literature, and film. Beyond finance, the bond had a cultural ripple effect. It validated the idea that art could be both an emotional and economic asset, challenging the notion that creativity and commerce were mutually exclusive. For Bowie’s estate, the bond ensured that his legacy would continue to generate revenue long after his death—a fitting tribute to an artist who constantly reinvented himself."Bowie’s music was always ahead of its time, and this bond was no different. It turned his art into a financial product, but in doing so, it preserved its value for future generations." — Financial advisor involved in the bond’s structuring (2017)
Major Advantages
- Liquidity for estates: Allows artists’ estates to access capital without selling rights outright.
- Stable returns: Payments are tied to proven revenue streams, reducing volatility.
- Transparency: Audited royalty projections build investor confidence.
- Legacy preservation: Ensures ongoing income for the artist’s heirs.
- Market validation: Proves that intellectual property can be a viable collateral asset.
Comparative Analysis
| Traditional Corporate Bond | Bowie Bond (Royalty-Backed) |
|---|---|
| Backed by company assets/earnings | Backed by future royalty streams |
| Fixed coupon payments | Variable payments tied to catalog performance |
| Subject to corporate risk | Subject to artistic longevity risk |
Future Trends and Innovations
The Bowie bond’s success has spurred interest in royalty-backed securities across industries. Sports leagues, for instance, are exploring bonds tied to player contracts, while film studios may securitize box office revenues. The key challenge remains predicting longevity: unlike corporate debt, which has tangible assets, creative royalties depend on cultural trends. Advances in data analytics—such as streaming metrics and fan engagement—could improve risk assessment, making such bonds more attractive to mainstream investors. Another evolution may come from tokenization, where fractional ownership of royalties is represented as digital assets on blockchains. This could democratize access to cultural investments, allowing retail investors to participate in the value of iconic works. However, regulatory hurdles and market volatility remain obstacles. For now, the Bowie bond stands as a proof of concept: a bridge between art and finance, proving that legacy can be both immortal and monetizable.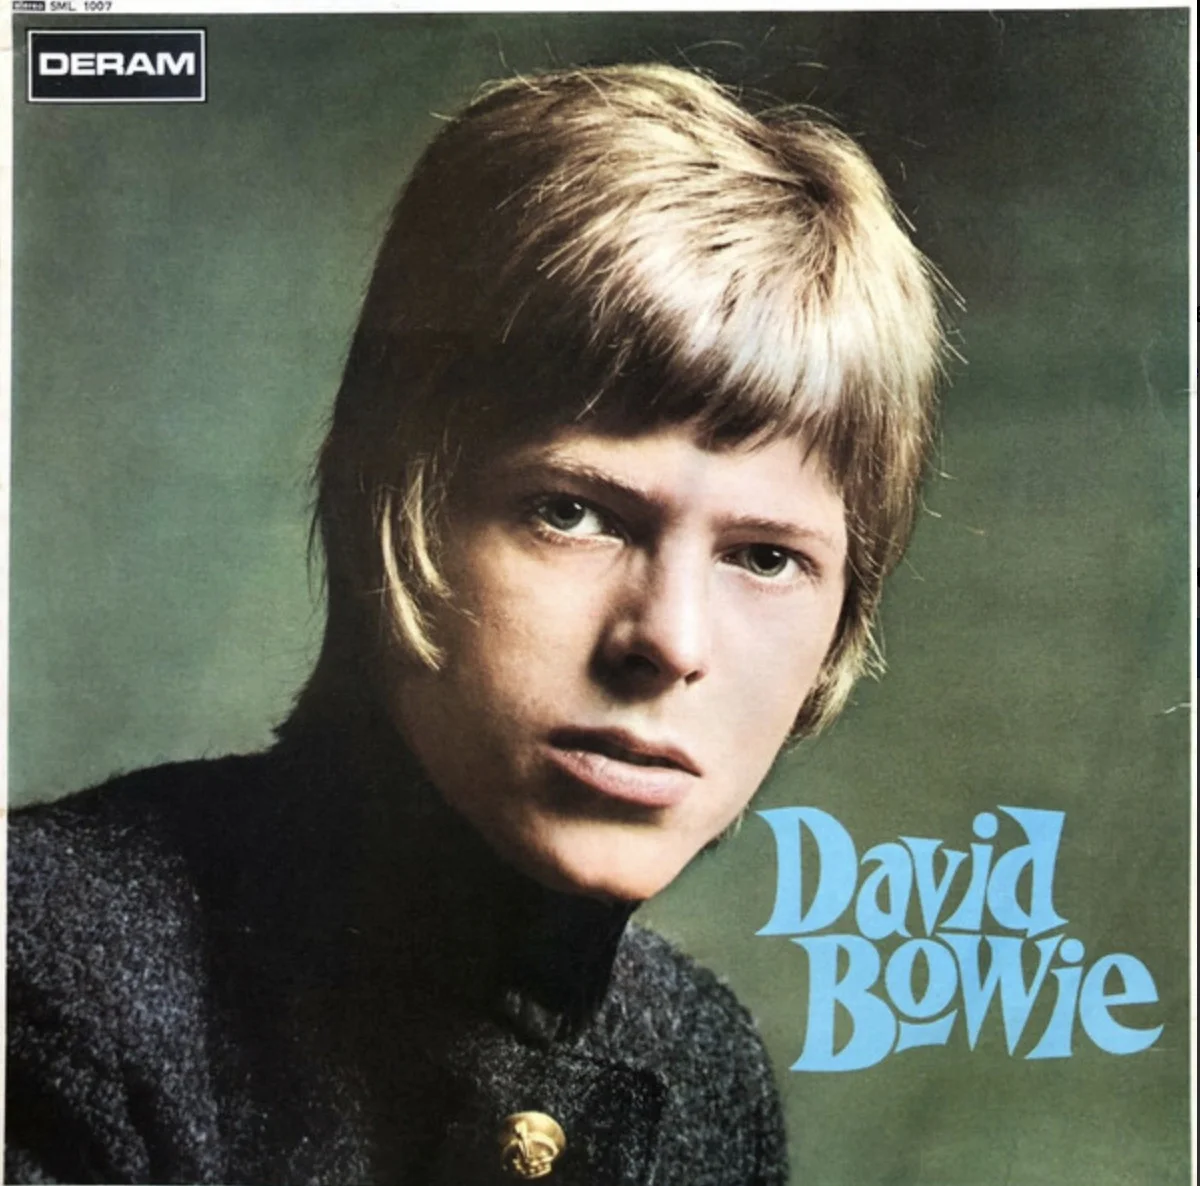
Conclusion
The Bowie bond was more than a financial product; it was a cultural experiment. By turning Bowie’s music into an investable asset, it challenged the boundaries of what could be collateralized. For the estate, it was a pragmatic solution to liquidity needs. For investors, it was a bet on the timelessness of art. And for the broader market, it was a signal that intellectual property could be as reliable as real estate or machinery—if structured correctly. As the music industry continues to grapple with streaming economics and artist compensation, the Bowie bond’s model offers a potential path forward. Whether through securitization or tokenization, the lesson is clear: legacy assets are not just sentimental—they’re financial tools. Bowie himself would have appreciated the irony: his greatest reinvention wasn’t on stage, but in the balance sheets of Wall Street.Comprehensive FAQs
Q: How much did the Bowie bond raise?
A: The bond reportedly raised around $100 million, though exact figures were not disclosed publicly. Proceeds were used to settle estate debts and provide liquidity.
Q: Can other artists’ estates issue similar bonds?
A: Yes, but success depends on the artist’s catalog value, revenue predictability, and market demand. Prince’s estate, for example, has explored similar structures post-2016.
Q: What happens if Bowie’s royalties decline?
A: Investors receive payments based on actual royalties, so declines would reduce payouts. The bond’s structure prioritizes estate obligations, meaning investors are last in line for distributions.
Q: Who manages the bond’s payments?
A: A third-party trustee, typically a financial institution, oversees distributions to ensure compliance with the bond’s terms and regulatory requirements.
Q: Are there risks to investing in such bonds?
A: Yes. The primary risk is royalty volatility—if an artist’s work loses commercial relevance, payments may shrink or cease. Additionally, legal disputes over estates can disrupt cash flows.
Q: Could this model work for non-musical IP, like books or films?
A: Absolutely. Film studios have explored bonds tied to box office revenues, and publishers could securitize advance payments from bestsellers. The key is proving the IP’s long-term cash-generating potential.
Q: What’s the difference between a Bowie bond and a traditional loan?
A: Traditional loans require repayment with interest, regardless of the borrower’s performance. The Bowie bond’s payments are contingent—investors only receive money if royalties materialize, making it a higher-risk, higher-reward instrument.
