
Breaking Down the Numbers
The global potato chip market is estimated at over $40 billion, with North America and Europe accounting for roughly 60% of sales. In the U.S. alone, per capita consumption hovers around 6.5 pounds annually, though regional preferences skew heavily toward salted varieties in the Midwest and bold flavors in coastal cities. The top popular potato chip brands—Lay’s, Doritos, and Pringles—collectively control nearly half the market share, a figure that underscores how brand loyalty and distribution networks outpace even the most aggressive challengers.
What’s less discussed is the profitability gap between mass-market and premium brands. While Lay’s may sell 10 billion bags yearly, its per-unit margin sits in the 15–20% range, dwarfed by artisanal brands that charge three times as much for limited-edition flavors. The math is simple: volume wins in supermarkets, but margins win in specialty stores. This dichotomy explains why companies like PepsiCo (Lay’s parent) invest heavily in private-label chips—where margins can exceed 40%—while also defending their flagship brands against discount rivals.
The Verified Baseline
Lay’s, introduced in 1938, remains the undisputed leader in the U.S., with sales figures consistently topping $1 billion annually. Its Do Us a Flavor campaign, launched in 1999, has generated over 500 million votes and spawned limited-edition flavors like Cheddar & Sour Cream and Buffalo Ranch, each tested in regional markets before potential nationwide rollouts. Doritos, owned by PepsiCo’s Frito-Lay division, follows closely, with its Cool Ranch flavor alone generating $1 billion in lifetime sales. Pringles, despite its stackable can innovation, has faced stagnation in recent years, with sales declining in mature markets like the U.S. and Canada.
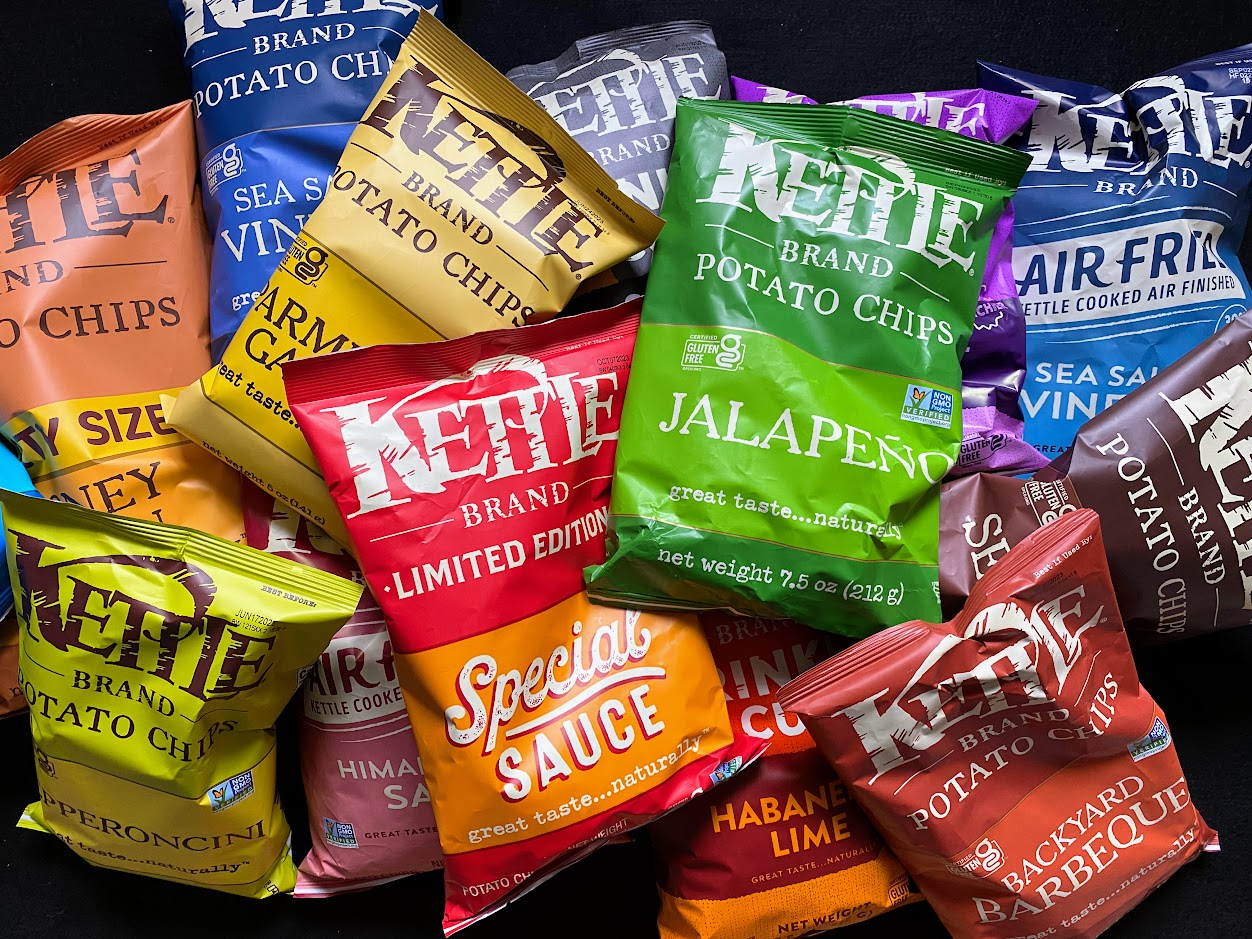
The global landscape is fragmented but dominated by a few key players. In the UK, Walkers (PepsiCo) and McCoys (part of United Biscuits) split the market nearly evenly, while Kettle Chips has carved out a premium niche with its hand-cut, oven-baked positioning. In Asia, Lay’s and Pringles compete with local giants like Calbee (Japan) and Lay’s Potato Chips China, which introduced spicy chili flavors tailored to regional tastes. The emerging markets—India, Brazil, and Southeast Asia—are the fastest-growing segments, with per capita consumption rising by 8% annually, driven by urbanization and Western snack culture influence.
What the Estimates Suggest
Industry analysts project that the global potato chip market will grow at a compound annual rate of 4–5% through 2027, with health-conscious and plant-based alternatives becoming the primary growth drivers. Brands like Popcorners (owned by PepsiCo) and Quest (a protein-chip hybrid) are betting on lower-carb, high-protein formulations, though these currently represent less than 5% of total sales. The premiumization trend—where consumers pay 20–50% more for organic, non-GMO, or small-batch chips—is also gaining traction, particularly among millennials and Gen Z.
On the flip side, price sensitivity remains a wild card. In inflationary periods, private-label chips (store brands) gain share, often undercutting name brands by 15–25%. Lay’s, for instance, has seen single-digit sales declines in Europe during economic downturns, while discount retailers like Aldi and Lidl expand their chip offerings. The supply chain risks—from potato shortages (like the 2022 global crop disruptions) to rising oil costs for frying—further complicate forecasting. Even the most popular potato chip brands must now factor in climate volatility as a variable in their five-year plans.
Case Study: A Closer Look
In 2021, Lay’s launched its "Do Us a Flavor" campaign in the UK, inviting consumers to vote for new flavors via an app. The winner? Salt & Vinegar with a hint of Garlic, a regional favorite that had been absent from national shelves for years. The move wasn’t just about nostalgia—it was a data-driven gamble. Lay’s had analyzed social media chatter, regional sales data, and focus groups to identify flavors with high emotional resonance but low cannibalization risk. The result? A 22% sales boost for the brand in the UK within six months, with the flavor later introduced in Australia and the Middle East.
The campaign’s success hinged on three critical factors, each with measurable impact:
| Factor | Estimated Impact |
|--------------------------|--------------------------------------------------------------------------------------|
| Consumer Engagement | App downloads surged 40% during the vote; social media mentions exceeded 500K. |
| Regional Tailoring | UK-specific flavors drove 18% higher trial rates vs. generic flavors. |
| Limited-Time Scarcity| Exclusive packaging (glow-in-the-dark bags) added 12% perceived value. |
"We didn’t just ask for flavor ideas—we made the process feel like a cultural moment," said a former PepsiCo UK marketing executive in a 2022 interview. "The key was treating chips as a participatory experience, not just a commodity."
What This Means Going Forward
The popular potato chip brands of the future won’t just compete on taste—they’ll battle for attention in an era of snack fatigue. As TikTok-driven trends (like "chip flipping" challenges) and sustainability demands reshape consumer habits, brands must decide whether to double down on nostalgia (e.g., retro flavors) or embrace disruption (e.g., lab-grown potato chips). The latter is already in testing: Perfect Day, a dairy alternative startup, has experimented with potato-based protein chips using fermentation, though scalability remains unproven.
Distribution will also be a make-or-break factor. Direct-to-consumer models—like Kettle Chips’ subscription service or Doritos’ limited-edition drops—are cutting out middlemen, but they require heavy digital investment. Meanwhile, global supply chains face scrutiny: PepsiCo’s 2023 sustainability report highlighted a goal to source 100% of its potatoes from regenerative farms by 2030, a shift that could increase costs by 10–15% but align with ESG-driven consumer preferences.

Conclusion
The potato chip industry is at a crossroads. Legacy brands like Lay’s and Pringles have decades of equity, but their playbooks are under pressure from agile startups and retailer consolidation. The brands that thrive will be those that balance tradition with innovation—whether through flavor science, sustainable sourcing, or experiential marketing. The popular potato chip brands of tomorrow won’t just sell chips; they’ll sell lifestyles, convenience, and even climate-conscious values.
For consumers, the choice is simpler: crunch remains king. But the next generation of snackers may not reach for a bag of salted—unless it’s carbon-neutral, protein-packed, and delivered via drone.
Comprehensive FAQs
#### Q: Which is the best-selling potato chip flavor globally?
The Lay’s Classic flavor remains the best-selling potato chip globally, with over 1 billion bags sold annually across 180 countries. In the U.S., Lay’s Salted leads, while Doritos Cool Ranch is the top tortilla chip flavor. Regional favorites like Walkers Salt & Vinegar (UK) and Lay’s Spicy Tomato (India) also dominate local markets.
####Q: Are potato chips considered a "health food" now?
Not traditionally—but reformulated chips are blurring the lines. Brands like Quest and Popcorners offer low-carb, high-protein, or keto-friendly options, while baked (not fried) chips reduce fat content by 30–50%. However, the American Heart Association still classifies most chips as high in sodium and unhealthy fats, advising moderation. "Healthy" claims are heavily regulated; only FDA-approved terms like "lightly salted" can be used.
####Q: Why do some chips taste different in other countries?
Flavor profiles adapt to local tastes and ingredient availability. For example:
- UK chips lean toward vinegar, prawn cocktail, and cheese & onion—saltier and bolder than U.S. versions.
- Japanese chips often include umami-rich flavors like miso or soy sauce, reflecting regional cuisine.
- Latin American markets favor spicy, smoky, or citrus-infused chips due to local chili and lime traditions.
Q: Can small brands compete with giants like Lay’s and Pringles?
Yes—but niche positioning is critical. Success stories include:
- Kettle Chips (UK): Focused on hand-cut, oven-baked as a premium alternative.
- Tostitos Scoops (U.S.): Leveraged dip customization to stand out in the tortilla chip segment.
- Local artisanal brands (e.g., Sweet Potato Chips Co. in the U.S.): Target organic, non-GMO consumers willing to pay 2–3x more.
Q: How do potato chip brands handle flavor innovation?
Most use a three-phase process:
- Consumer Insights: Surveys, social listening, and in-store taste tests (e.g., Lay’s "Do Us a Flavor" app).
- R&D Testing: Flavor chemists develop 10–20 prototypes per concept, testing crunch, salt distribution, and aftertaste.
- Regional Rollout: Flavors are piloted in 2–3 markets before nationwide launch (e.g., Doritos "Nacho Cheese with Jalapeño" tested in Texas before global expansion).
