Breaking Down the Numbers
The difference between working capital and net worth hinges on their core definitions and what each metric actually measures. Working capital is a snapshot of operational health, calculated as current assets minus current liabilities. It answers a critical question: Can the business or individual cover its short-term obligations without disrupting operations? Net worth, by contrast, is a balance sheet total—assets minus liabilities—offering a broader view of wealth accumulation. While working capital focuses on the next quarter, net worth reflects years or decades of financial decisions. This distinction matters because financial health isn’t monolithic. A company with strong working capital but stagnant net worth may be efficient but unproductive in the long run. Conversely, an entity with high net worth but weak working capital risks liquidity crises. The difference between working capital and net worth thus becomes a lens for evaluating risk tolerance, growth strategies, and even leadership priorities. Investors scrutinize working capital for stability; lenders assess net worth for collateral. The two metrics don’t move in lockstep, and ignoring that reality can have costly consequences.The Verified Baseline
Publicly traded companies disclose working capital and net worth in their financial statements, providing a baseline for comparison. For example, a retail chain might report working capital of $50 million—enough to cover six months of operating expenses—while its net worth stands at $200 million, reflecting decades of retained earnings and asset appreciation. The difference between working capital and net worth here is stark: the former ensures day-to-day functionality, while the latter underpins long-term equity value. In individual finance, net worth is straightforward: assets like real estate, investments, and savings minus debts like mortgages and loans. Working capital for an individual is less formal but equally critical—it’s the liquid cash available to cover unexpected expenses, such as medical bills or car repairs. The difference between working capital and net worth for a high-net-worth individual might mean having a $10 million portfolio but only $50,000 in an emergency fund. The gap highlights a reliance on illiquid assets, which can be problematic in crises.What the Estimates Suggest
Industry estimates suggest that businesses in capital-intensive sectors—like manufacturing or real estate—often prioritize net worth growth over working capital, leading to higher leverage and tighter cash buffers. Reports indicate that such firms may maintain working capital ratios as low as 1.2:1 (current assets to current liabilities), betting on asset appreciation to offset short-term liquidity risks. The difference between working capital and net worth in these cases becomes a trade-off between growth and stability. For small businesses, the dynamic shifts. Studies show that startups with strong working capital—often funded by bootstrapping or grants—survive longer, even if their net worth grows slowly. The difference between working capital and net worth here is survival versus scalability. A tech startup might report negative net worth for years but maintain positive working capital, reinvesting profits to fuel innovation. The metrics tell different stories: one about immediate viability, the other about future potential.
Case Study: A Closer Look
Consider the case of a mid-sized manufacturing firm that expanded aggressively in 2022, acquiring new machinery and increasing inventory. Its net worth surged as fixed assets appreciated, but working capital tightened due to delayed payments from clients. By mid-2023, the company faced a liquidity crunch despite its strong balance sheet. The difference between working capital and net worth became a crisis: the firm had the assets but lacked the cash to operate. The CEO later remarked:"We mistook net worth for operational health. The books showed growth, but the bank account didn’t. Working capital isn’t just numbers—it’s oxygen for the business."A breakdown of the factors at play reveals the disconnect:
| Factor | Estimated Impact |
|---|---|
| Inventory buildup | Reduced working capital by ~$8 million (unsold stock) |
| Delayed receivables | Cash flow lagged by 45 days, straining payroll |
| Fixed asset appreciation | Boosted net worth by ~$12 million (book value) |
| Debt restructuring | Increased long-term liabilities, offsetting short-term gains |
| Emergency liquidity line | Cost ~$500,000 in fees to stabilize working capital |
What This Means Going Forward
For businesses, the difference between working capital and net worth will increasingly shape investment strategies. Private equity firms, for instance, now scrutinize working capital efficiency as closely as net worth multiples. A company with high net worth but weak working capital may attract vulture investors, while those optimizing both metrics command premium valuations. Individuals, too, must reconcile the two. High-net-worth families often diversify liquidity—holding cash reserves alongside illiquid assets—to bridge the gap. The difference between working capital and net worth in personal finance isn’t just about wealth preservation; it’s about legacy planning. A family with a $50 million estate but no liquidity may face forced asset sales to cover estate taxes, eroding generational wealth.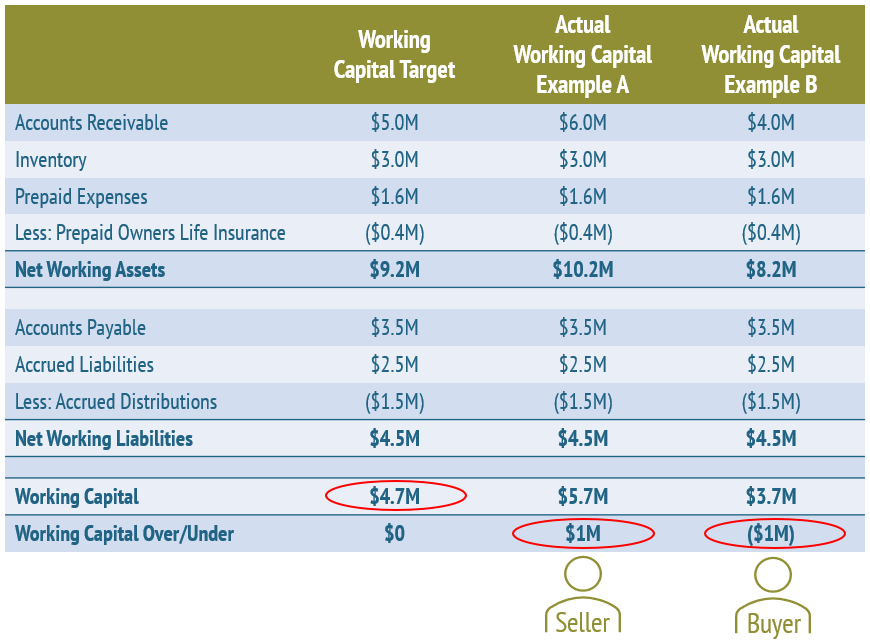
Conclusion
The difference between working capital and net worth isn’t a theoretical exercise—it’s the difference between a business that survives a downturn and one that collapses under its own weight. Net worth tells a story of accumulation; working capital tells a story of survival. Ignoring either is a strategic error. For companies, the balance between the two defines scalability. For individuals, it determines financial freedom. The metrics aren’t mutually exclusive, but they aren’t interchangeable. A savvy financial strategy aligns both: preserving liquidity while building assets. The firms and individuals who master this duality are the ones who thrive—not just in good times, but in the inevitable challenges ahead.Comprehensive FAQs
Q: Can a company have positive working capital but negative net worth?
A: Yes. A startup might have current assets (cash, inventory) exceeding current liabilities (payables) but negative net worth if its long-term liabilities (debt) or accumulated losses outweigh its assets. The difference between working capital and net worth here is critical: the company can operate today but isn’t yet profitable or asset-rich.
Q: How does working capital affect net worth over time?
A: Indirectly. Strong working capital ensures a business can reinvest profits, pay down debt, or expand—all of which can increase net worth. Poor working capital forces asset liquidation (e.g., selling equipment) to cover liabilities, which may reduce net worth. The difference between working capital and net worth is that one fuels the other, but mismanagement of either can erode both.
Q: Is net worth more important for retirement planning than working capital?
A: For retirement, net worth is the primary focus—it represents the total resources available. However, working capital (or its personal equivalent, emergency savings) is non-negotiable. A retiree with high net worth but no liquid reserves may face forced asset sales during market downturns. The difference between working capital and net worth in retirement planning is liquidity versus legacy.
Q: Can improving working capital hurt net worth?
A: Rarely, but it’s possible. For example, reducing inventory to boost working capital might lower revenue if sales decline. However, the trade-off is usually temporary. Sustainable improvements—like negotiating better payment terms—enhance both metrics. The difference between working capital and net worth in this case is short-term liquidity gains versus long-term asset growth.
Q: How do investors evaluate the relationship between working capital and net worth?
A: Investors use working capital ratios (current ratio, quick ratio) to assess liquidity risk, while net worth informs valuation multiples (e.g., price-to-book). A company with high net worth but weak working capital may trade at a discount. The difference between working capital and net worth becomes a risk premium: investors demand higher returns for illiquid assets.
Q: What’s the biggest misconception about the difference between working capital and net worth?
A: Assuming they move in tandem. Many believe that growing net worth automatically improves working capital, or vice versa. In reality, a company can have strong net worth (e.g., via asset appreciation) but poor working capital (e.g., due to slow collections). The difference between working capital and net worth is that one is a snapshot of health; the other is a measure of wealth.
Q: How can individuals track both metrics personally?
A: Net worth is straightforward: list assets and liabilities annually. Working capital for individuals is less formal but can be tracked via a liquidity buffer—typically 3–6 months of living expenses. Tools like spreadsheets or fintech apps can automate this. The difference between working capital and net worth for individuals is short-term security versus long-term accumulation.
Q: Are there industries where working capital is more critical than net worth?
A: Yes. Retail, hospitality, and manufacturing rely heavily on working capital due to high inventory turnover and receivable cycles. Net worth matters less in these sectors than operational efficiency. The difference between working capital and net worth here is that survival depends on cash flow, not asset appreciation.
