
Where It All Began
The concept of extending credit card highest credit limits beyond the average consumer emerged in the late 1950s, when Bank of America’s Frank McNamara—frustrated by forgetting his wallet at a restaurant—pitched the idea of a charge card to his colleagues. What started as a novelty for business travelers soon evolved into a financial instrument. By the 1960s, Diners Club and American Express had introduced cards with credit card highest credit limits that catered to a niche: frequent travelers, corporate executives, and high-net-worth individuals. These weren’t just transaction tools; they were credit card highest credit limits that signaled membership in an exclusive club. The early limits—often capped at $1,000—were less about spending power and more about social capital. A cardholder with a high limit wasn’t just borrowing; they were being vetted. The real inflection point came in the 1970s, when banks began tying credit card highest credit limits to credit scores and income verification. No longer was approval based on a handshake or a banker’s gut feeling. Instead, algorithms started predicting how much a person could reasonably spend without defaulting. This shift democratized access—but also created a two-tier system. While the average cardholder might see a $5,000 limit, the top 1% could negotiate credit card highest credit limits in the $50,000–$100,000 range, often with little more than a phone call to their relationship manager. The unspoken rule? The higher the limit, the more the bank expected you to use it—and the more interchange revenue they’d collect.The Early Signs
The first cracks in the system appeared in the 1980s, when credit card highest credit limits became a status symbol rather than a practical tool. Wealthy individuals began requesting credit card highest credit limits far exceeding their actual spending needs, not because they planned to max them out, but because the limit itself became a flex. Banks, eager for business, often obliged—only to later realize that these highest credit limits were being underutilized, yet still carried the same risk of default. The lesson? Credit card highest credit limits weren’t just about borrowing capacity; they were about psychological leverage. By the late 1990s, the rise of premium travel cards—like the American Express Centurion Card (the "Black Card")—further blurred the lines between credit and concierge service. These cards didn’t just offer credit card highest credit limits; they offered perks tied to those limits, from private jet charters to annual travel credits. The message was clear: the higher your credit card highest credit limit, the more the bank was willing to invest in your lifestyle. But for every success story, there was a cautionary tale—individuals who had their limits slashed after a single missed payment, or who found themselves drowning in debt because the credit card highest credit limit had lured them into overspending.The Turning Point
The early 2000s marked a turning point. The credit card highest credit limit wars had become a battleground between issuers competing for the ultra-wealthy, and banks began offering credit card highest credit limits that were effectively unchecked—at least on paper. A $250,000 limit on a platinum card wasn’t uncommon for clients with proven asset portfolios. But the housing crisis of 2008 exposed the fragility of this system. Suddenly, even the most trusted cardholders found their credit card highest credit limits frozen or reduced as banks tightened risk thresholds. The era of unlimited credit had ended. What followed was a recalibration. Banks realized that credit card highest credit limits weren’t just about revenue—they were about risk management. The days of granting credit card highest credit limits based solely on net worth were over. Instead, issuers began factoring in spending habits, cash reserves, and even emotional stability (as gauged by credit bureau data). The result? A more structured approach to credit card highest credit limits, where the highest tiers were reserved for those who could demonstrate both wealth and discipline."The highest credit limits aren’t about how much you can borrow—they’re about how much the bank trusts you to spend without breaking them." — Former American Express relationship manager, 2015
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1958–1965 | BankAmericard and Diners Club introduce early credit card highest credit limits, primarily for business travelers. Limits capped at $1,000–$2,500. |
| 1970–1985 | Credit scoring models emerge, tying credit card highest credit limits to income and debt-to-income ratios. First instances of credit card highest credit limits exceeding $50,000 for elite clients. |
| 1990–2000 | Premium cards (e.g., Amex Platinum) introduce credit card highest credit limits with luxury perks. Limits for top clients reach $100,000+. |
| 2005–2008 | Banks offer credit card highest credit limits with minimal scrutiny, leading to speculative spending. Crisis hits, and credit card highest credit limits are slashed across the board. |
| 2010–Present | Issuers adopt behavioral scoring for credit card highest credit limits. Limits now reflect spending discipline as much as wealth. Black Card limits now reportedly exceed $500,000 for select clients. |
Lessons From the Journey
- Limits aren’t static. A credit card highest credit limit today can vanish tomorrow if spending patterns shift.
- Perks often come with strings. The higher the credit card highest credit limit, the more the issuer expects you to use it—and spend.
- Net worth ≠ spending power. Many ultra-wealthy individuals have credit card highest credit limits far below their liquid assets.
- Psychology plays a role. A $100,000 credit card highest credit limit can make a person feel invincible—until it doesn’t.
- Banks profit from underutilized limits. The more you don’t spend, the less interchange revenue they earn.
- The highest tiers are earned, not given. Credit card highest credit limits in the six figures require years of proven financial responsibility.
Where Things Stand Today
The modern landscape of credit card highest credit limits is defined by two opposing forces: exclusivity and algorithmic precision. On one hand, issuers like Amex and Chase still offer credit card highest credit limits that dwarf those of a decade ago—reportedly, some Black Card holders now see credit card highest credit limits in the $300,000–$1M range, though exact figures are rarely disclosed. These aren’t just borrowing tools; they’re access badges to private banking, concierge services, and even invite-only events. On the other hand, the rise of real-time spending analytics means that even a single late payment can trigger a credit card highest credit limit review within 24 hours. What’s changed is the transparency—or lack thereof. Where once a cardholder might negotiate a credit card highest credit limit increase over the phone, today’s process is often automated and data-driven. Banks now monitor spending velocity, cash flow, and even social media activity to determine whether a credit card highest credit limit increase is justified. The result? A system where credit card highest credit limits are both more accessible to the ultra-wealthy and more restrictive for everyone else. Yet the allure remains. For the right candidate—a high-earning professional with strong credit and liquid assets—a credit card highest credit limit in the six figures isn’t just a financial tool; it’s a symbol of trust. The bank isn’t just lending money; it’s endorsing your lifestyle. But the flip side? The same credit card highest credit limit can become a debt trap if spending habits aren’t aligned with income.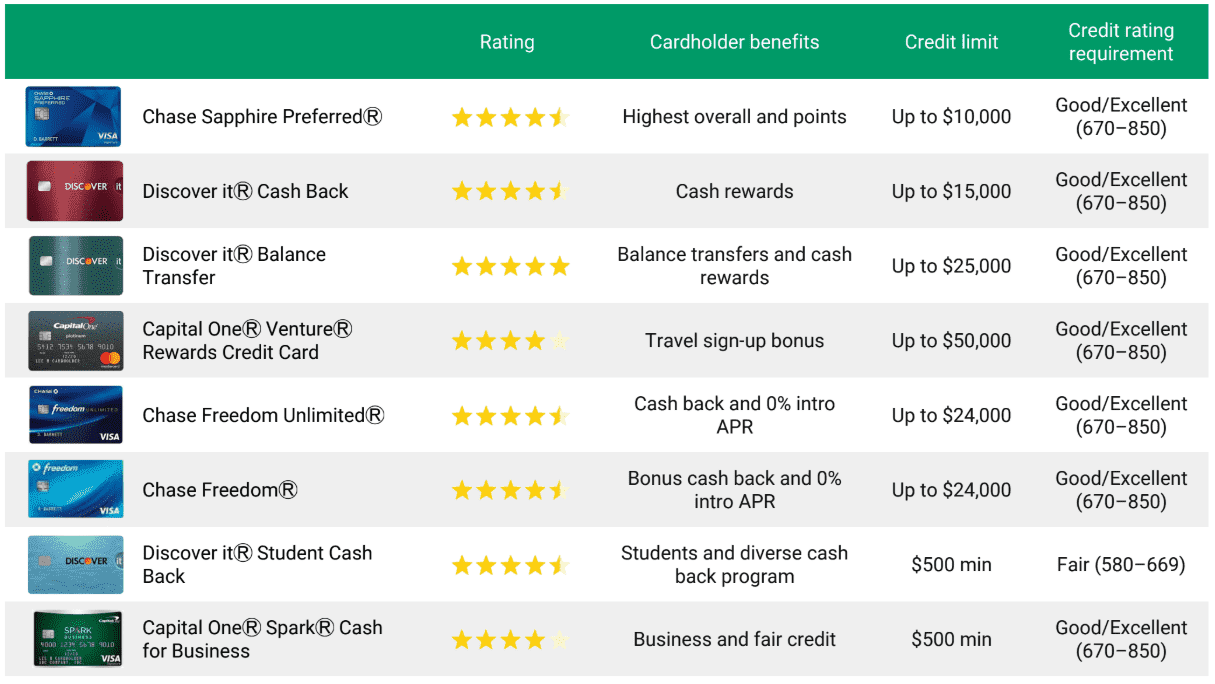
Conclusion
The evolution of credit card highest credit limits reflects broader shifts in finance: from trust-based lending to data-driven risk assessment, from exclusivity to algorithmically enforced tiers. What began as a $500 line for a forgotten wallet has become a multi-million-dollar industry, where the credit card highest credit limit is as much about social signaling as it is about borrowing power. The lesson? Credit card highest credit limits aren’t just numbers—they’re contracts of trust, and like all contracts, they can be broken. For the individual, the takeaway is simple: a high limit isn’t a right—it’s a privilege. And like any privilege, it demands responsibility. The banks that once handed out credit card highest credit limits like candy now scrutinize every transaction. The cardholders who once spent freely now face real-time consequences. The future of credit card highest credit limits won’t be about breaking records—it’ll be about balancing access with accountability.Comprehensive FAQs
Q: What’s the absolute highest credit card limit available today?
A: While exact figures are rarely disclosed, industry estimates suggest that credit card highest credit limits on premium cards (e.g., Amex Centurion) can reach $300,000–$1M+ for ultra-high-net-worth individuals. These limits are typically tied to liquid assets, income, and spending history rather than just credit scores.
Q: Can I request a higher credit limit on my existing card?
A: Yes, but approval depends on your creditworthiness, income, and spending patterns. Issuers may allow online requests for modest increases, while six-figure limits usually require a relationship manager’s approval. A sudden large request without context (e.g., a job change) can trigger a credit limit freeze.
Q: Do higher credit limits always come with better rewards?
A: Not necessarily. While credit card highest credit limits often unlock premium perks (e.g., lounge access, travel credits), the best rewards (e.g., cash-back percentages) are usually tied to spending categories, not limit size. Some issuers even reduce rewards if you max out a high limit, assuming you’re over-leveraged.
Q: What happens if I max out a high credit limit?
A: The consequences vary by issuer. Some may temporarily suspend purchases until you pay down the balance, while others might lower your limit or increase your APR. In extreme cases (e.g., credit card highest credit limits near $100K), a maxed-out card can trigger a relationship manager review, potentially leading to limit reductions or account closure.
Q: Are there cards with no preset credit limit?
A: Yes—charge cards like the Amex Centurion operate on a "pay in full" model with no preset spending cap, though issuers may monitor and adjust based on your financial profile. These cards require strong credit and high income, and late payments are not an option.
Q: How do banks decide who gets the highest credit limits?
A: The criteria include FICO score (typically 750+), income (often $250K+ for six-figure limits), liquid assets, employment stability, and spending history. Issuers also consider relationship length—long-term clients with consistent, disciplined spending are more likely to receive credit card highest credit limits. Some banks even factor in social media activity to gauge risk.
Q: Can a high credit limit hurt my credit score?
A: Indirectly, yes. While a high limit itself doesn’t lower your score, maxing it out can increase your credit utilization ratio (e.g., spending $90K on a $100K limit), which hurts your score. Additionally, hard inquiries for limit increases can cause a temporary dip. The key is maintaining a low utilization rate (ideally below 30%) even with a credit card highest credit limit.
