
7 Things Worth Knowing About the Country with Lowest Debt to GDP
The country with lowest debt to GDP isn’t a single entity but a rotating cast of nations, with rankings shifting yearly based on GDP growth, debt issuance, and economic shocks. What remains constant is the fascination with how these outliers operate—and the lessons (or warnings) they offer. Below are seven key dynamics that define their fiscal profiles, from the structural advantages that keep debt in check to the unintended consequences of such discipline.1. The Role of Natural Resource Windfalls
Countries like Brunei and Qatar frequently appear near the top of lists for the lowest debt-to-GDP ratios, not because of fiscal virtuosity, but because their economies are propped up by hydrocarbon revenues. Brunei’s sovereign wealth fund, the Brunei Investment Agency, holds assets estimated to exceed its GDP multiple times, allowing the government to fund expenditures without borrowing. Similarly, Qatar’s debt-to-GDP ratio hovers around 10-15%—a fraction of global peers—thanks to its gas reserves and sovereign wealth fund. The catch? These ratios can be misleading. Relying on non-renewable resources creates a resource curse: when prices dip, the fiscal cushion evaporates, and debt spikes abruptly. Brunei’s 2015 budget crisis, triggered by falling oil prices, saw its debt-to-GDP ratio surge temporarily, exposing the fragility beneath the surface. The broader lesson is that the country with lowest debt to GDP in resource-rich nations often reflects a temporary advantage rather than structural strength. Without diversification, even the most disciplined fiscal policies become hostage to commodity cycles. Economists warn that the true test of sustainability lies in whether these nations can transition to debt-free growth without their primary revenue streams.2. Monetary Sovereignty and Currency Stability
Some of the lowest debt-to-GDP ratios belong to nations with their own currencies and central banks free from external interference. Switzerland, for instance, maintains a debt-to-GDP ratio below 40%, partly due to its ability to print francs without fear of inflation or capital flight. The Swiss National Bank’s independence allows it to manage debt affordably, while the country’s political stability ensures creditors view its obligations as low-risk. Similarly, Singapore’s debt-to-GDP ratio—consistently below 100%—is underpinned by its own currency, the Singapore dollar, and a sovereign wealth fund that acts as a fiscal buffer. This advantage is not universal. Smaller economies, even those with low debt, often lack currency sovereignty, forcing them to borrow in foreign currencies (like the US dollar) and exposing them to exchange-rate risks. The country with lowest debt to GDP in this category thrives because its monetary policy isn’t constrained by external pressures, allowing it to borrow cheaply and service debt with relative ease.3. The Austerity Paradox: Low Debt, High Costs
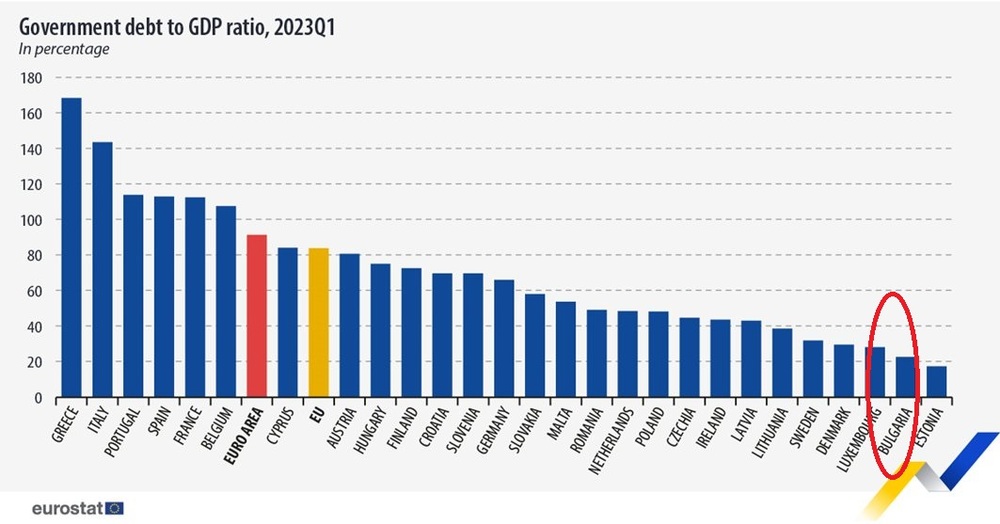
Estonia and Sweden are frequent contenders for the lowest debt-to-GDP titles, but their paths diverge sharply. Estonia’s ratio has hovered around 10-15% in recent years, achieved through brutal austerity measures after its 2008 financial collapse. The trade-off? Public services were slashed, wages stagnated, and social unrest flared. Sweden, by contrast, maintains a similarly low ratio (around 30%) while funding robust welfare systems—thanks to higher taxes and efficient public spending. The contrast illustrates a critical question: Does low debt require sacrifice, or is it a byproduct of smart allocation? The answer varies. Estonia’s approach shows that the country with lowest debt to GDP can emerge from crisis through painful belt-tightening, but the long-term human cost may outweigh the fiscal gains. Sweden’s model suggests that low debt is compatible with prosperity—if the political will exists to tax efficiently and spend wisely.4. Demographic Dividends and Pension Funds
Norway’s debt-to-GDP ratio has remained below 30% for decades, a feat attributed not just to oil revenues but to its Government Pension Fund Global—one of the world’s largest sovereign wealth funds, holding assets worth trillions. The fund’s returns finance public expenditures without borrowing, while Norway’s aging population (a demographic challenge for many) is partially offset by high savings rates and a culture of long-term planning. Japan, too, has flirted with the lowest debt-to-GDP club (peaking near 260% but shrinking as a percentage of GDP due to stagnant growth), thanks to its massive pension reserves and life insurance sector, which recycle savings back into the economy. The demographic angle is crucial: The country with lowest debt to GDP often benefits from a savings surplus—where households and institutions save more than the government borrows. This dynamic is rare and fragile; it requires either a young, high-saving population (like in East Asia) or a mature economy with strong institutional trust (like in Northern Europe).5. Geopolitical Shelter and Capital Flight
Luxembourg’s debt-to-GDP ratio has consistently ranked among the lowest in the world, dipping below 20% in recent years. The secret? It’s not Luxembourg’s domestic economy but its role as a tax haven and financial hub. The country’s banking sector, which dwarfs its GDP, generates massive revenues through fees and capital inflows—funding government spending without recourse to debt. Similarly, the Cayman Islands and other microstates with offshore finance sectors achieve artificially low debt ratios by leveraging foreign capital rather than issuing domestic debt. This model carries risks. The country with lowest debt to GDP in this category is vulnerable to global financial shifts: if capital flees (as during the 2008 crisis), the fiscal advantage vanishes overnight. Luxembourg’s ratio spiked temporarily in 2020 as its banking sector shrank, proving that even the most opaque systems aren’t immune to external shocks."A low debt-to-GDP ratio is like a Swiss watch—beautifully precise until you drop it. The real test is whether the economy can withstand the fall." — Olivier Blanchard, former IMF Chief Economist
6. The Hidden Liabilities: Off-Balance-Sheet Debt
Not all debt appears on a nation’s balance sheet. The country with lowest debt to GDP may still face hidden obligations through pension liabilities, sovereign guarantees, or state-owned enterprise losses. For example, South Korea’s official debt-to-GDP ratio is around 40%, but when factoring in implicit liabilities (like future pension payouts), the figure swells to over 100%. Similarly, China’s local government debt—officially capped but estimated to exceed 100% of GDP—has been a ticking time bomb, despite Beijing’s efforts to keep the national ratio below 60%. The lesson is clear: the country with lowest debt to GDP on paper might still be sitting on a fiscal time bomb. Transparency in accounting is as critical as the ratio itself. Nations that underreport liabilities risk future crises, even if today’s numbers look pristine.7. The Policy Trade-Offs: Growth vs. Debt Control
The country with lowest debt to GDP often faces a growth paradox. Strict fiscal rules can stifle investment in infrastructure or innovation. Germany, for instance, has kept its debt-to-GDP ratio below 70% for years, but critics argue its austerity has limited its ability to compete with neighbors like France, which runs higher deficits to fund green transitions and digital infrastructure. Meanwhile, New Zealand’s debt ratio has fluctuated wildly—dipping below 20% in the 1990s but surging to 50% post-2020—due to policy shifts between free-market liberalism and Keynesian stimulus. The tension between debt discipline and economic dynamism is eternal. The country with lowest debt to GDP must decide: prioritize short-term fiscal health at the cost of long-term growth, or accept higher debt to fuel productivity? The answer depends on whether the nation values stability over ambition—or vice versa.
How These Facts Connect
The country with lowest debt to GDP isn’t a uniform category but a spectrum shaped by geography, history, and governance. Resource wealth can mask structural weaknesses, while monetary sovereignty provides a shield against global volatility. Austerity may be necessary in some contexts but socially destructive in others, and demographic trends can either buoy or sink a nation’s fiscal position. The common thread? Low debt is rarely an accident. It’s the result of deliberate choices—whether to tax heavily, spend efficiently, or rely on external revenues. Yet the data also reveals a fragility beneath the surface. Even the most disciplined economies can be upended by external shocks, accounting tricks, or demographic shifts. The country with lowest debt to GDP today may not hold that title tomorrow if oil prices crash, capital flees, or a new crisis emerges. The real insight lies in understanding how these nations maintain their balance—and whether their playbook is replicable elsewhere.| Factor | Example Nation | Debt-to-GDP Ratio (Recent) | Key Advantage | Major Risk |
|---|---|---|---|---|
| Resource Wealth | Brunei | ~15% | Sovereign wealth fund | Commodity price volatility |
| Monetary Sovereignty | Switzerland | ~38% | Central bank independence | Inflation pressures |
| Austerity-Driven | Estonia | ~12% | Fiscal discipline | Social unrest |
| Offshore Finance | Luxembourg | ~18% | Capital inflows | Global financial instability |
Conclusion
The country with lowest debt to GDP offers more than just a bragging right—it provides a lens into the trade-offs of economic management. The nations that dominate these rankings do so through a mix of luck (natural resources, stable currencies) and policy (austerity, wealth funds, tax efficiency). But the rankings are also a reminder that low debt doesn’t equal economic health. Hidden liabilities, demographic time bombs, and geopolitical exposure can turn a fiscal success story into a cautionary tale. For other countries watching, the takeaway isn’t to mimic a single model but to ask: What kind of low debt do we want? A debt-free nation propped up by austerity may avoid crises, but at what cost to its people? A country with low debt due to offshore finance may attract capital, but only until the next global panic. The country with lowest debt to GDP isn’t the goal—it’s a starting point for a larger conversation about sustainability, equity, and resilience.Comprehensive FAQs
Q: Which country currently holds the record for the lowest debt-to-GDP ratio?
A: As of recent data, Brunei and Qatar frequently appear at the top, with ratios below 15%, thanks to hydrocarbon revenues and sovereign wealth funds. However, rankings fluctuate yearly based on GDP growth and debt issuance. Microstates like Saudi Arabia (when excluding oil-backed debt) or Hong Kong (as a SAR) also occasionally lead due to unique fiscal structures.
Q: Can a country with low debt still face economic problems?
A: Absolutely. The country with lowest debt to GDP may struggle with stagnant growth (Japan), social inequality (Estonia post-austerity), or external shocks (Brunei during oil price collapses). Low debt alone doesn’t guarantee prosperity—it must be paired with productive investment, innovation, and adaptive policies.
Q: How do sovereign wealth funds help reduce debt?
A: Funds like Norway’s or Singapore’s Government Pension Fund generate returns from global investments, which are then used to finance government spending without issuing new debt. This creates a fiscal buffer that allows the country to run surpluses or avoid borrowing, keeping the debt-to-GDP ratio artificially low. The challenge is ensuring the fund’s returns outpace liabilities over time.
Q: Why don’t more countries achieve low debt-to-GDP ratios?
A: Structural barriers include limited tax bases, high social spending needs, low savings rates, or lack of natural resources. Developing nations often face the debt trap: borrowing to grow, but growth never materializes fast enough to outpace debt accumulation. Even advanced economies like the US or Italy, despite high debt, struggle to reduce ratios due to aging populations, rising healthcare costs, and low productivity growth.
Q: Is there a downside to having too low debt?
A: Yes. The country with lowest debt to GDP may underinvest in critical areas like infrastructure, education, or R&D, leading to long-term stagnation. Historically, nations like Germany have faced criticism for over-saving—keeping debt low but failing to stimulate demand during recessions. The sweet spot lies in balancing debt affordability with investment in future growth.
