The Complete Overview of "How Much Net Worth by Age"
Net worth by age isn’t a static target but a moving benchmark tied to economic cycles, policy shifts, and cultural expectations. In the 1980s, a 35-year-old with $250,000 in net worth might have been considered affluent; today, that same figure would place them in the bottom quartile in many U.S. cities. The problem? Most financial advice treats these benchmarks as universal truths, ignoring that a software engineer in San Francisco faces entirely different math than a teacher in rural Mississippi. Even the term "net worth" is misleading—it obscures the fact that liquid assets (cash, stocks) behave differently than illiquid assets (a home, a business), and that debt isn’t always the villain it’s made out to be. The real story behind "how much net worth by age" is about opportunity velocity. A 2022 study by the Urban Institute found that homeownership alone accounts for 70% of the wealth gap between white and Black families. Meanwhile, student debt—now exceeding $1.7 trillion in the U.S.—acts as a wealth drain for younger cohorts. The question isn’t just "How do I grow my net worth?" but "What levers can I pull, and which ones are locked to me?" The answer varies wildly depending on whether you were born into a family that could afford to teach you about tax-loss harvesting or whether your first financial lesson was how to stretch a paycheck.Historical Background and Evolution
The modern obsession with tracking net worth by age traces back to the 1990s, when financial planners began promoting "wealth milestones" as a way to motivate savings. The idea was simple: if you hit $X by age Y, you’d be on track for retirement. But these benchmarks were built on outdated assumptions—namely, that everyone would follow a traditional career path, own a home, and retire at 65. The 2008 financial crisis exposed the fragility of this model. Suddenly, people who’d followed the script found their 401(k)s halved overnight, and the "how much net worth by age" question became a panic button rather than a planning tool. What’s often overlooked is that these benchmarks were never neutral. The "Fidelity Rule"—suggesting your net worth should equal your age multiplied by your annual income—was designed for a specific demographic: white-collar workers with employer-matched retirement plans. It ignored gig workers, freelancers, and those in industries where income volatility is the norm. Even the Net Worth by Age Calculator tools popularized by robo-advisors like Vanguard or Fidelity are built on median data, not averages. That means half the population falls below these targets by definition. The historical evolution of "how much net worth by age" isn’t just about numbers—it’s about who gets to set the rules.Core Mechanisms: How It Works
Net worth growth isn’t linear; it’s exponential when conditions align. The core mechanism is compounding, but not just of investments—of human capital, social capital, and structural advantages. Take real estate: a 2019 Harvard study found that homeowners under 35 saw their net worth 30% higher than renters, even when controlling for income. That’s because a mortgage isn’t just a liability; it’s a forced savings plan with leverage. Meanwhile, someone renting in a high-cost city might have zero illiquid assets to offset inflation. The second mechanism is income velocity. A surgeon’s net worth trajectory will differ from a barista’s not just because of salary, but because the surgeon’s income is stable, tax-advantaged, and often tied to assets (malpractice insurance, medical equipment partnerships). The barista, meanwhile, might see their take-home pay fluctuate with tips, healthcare costs, and the whims of corporate scheduling. This is why "how much net worth by age" discussions often devolve into "what industry are you in?" rather than "how hard are you working?" The system rewards predictable cash flows over hustle.Key Benefits and Crucial Impact
Understanding net worth by age isn’t just about vanity metrics—it’s about financial agency. For example, a 2023 Pew Research report found that households with net worth above $1 million are three times more likely to weather a job loss without dipping into retirement savings. That’s not because they’re smarter; it’s because they have buffers. The ability to say "No" to a toxic job, start a side hustle, or take a career risk is directly tied to net worth. Even small buffers—like having three months’ expenses in cash—can mean the difference between stress and opportunity. The psychological impact is equally stark. A study in the Journal of Financial Therapy found that people with consistent net worth growth report lower levels of financial anxiety, even if their absolute numbers are modest. The perception of "moving forward"—even if it’s just $500 a year—creates a feedback loop of confidence. Conversely, stagnant or declining net worth by age correlates with increased healthcare costs, divorce rates, and mental health declines. The numbers aren’t just spreadsheets; they’re levers for resilience."Wealth isn’t about how much you have; it’s about how much you can do without fear." — Susan Tompor, Detroit Free Press financial columnist
Major Advantages
- Leverage in negotiations. A higher net worth by age translates to bargaining power—whether it’s asking for a raise, negotiating a mortgage rate, or securing a business loan.
- Inflation resistance. Illiquid assets (real estate, collectibles) often outpace inflation, while liquid assets (cash, savings) erode over time.
- Legacy planning. Net worth by age isn’t just about you; it’s about what you can pass down—whether that’s an inheritance, a trust fund, or simply the ability to fund a child’s education.
- Opportunity access. Private schools, co-sponsorships, or even quiet luxury purchases (think: a $200 pair of sunglasses) become feasible when net worth thresholds are met.
- Tax efficiency. Higher net worth unlocks strategies like charitable remainder trusts, municipal bonds, or offshore accounts—tools typically reserved for the wealthy.
Comparative Analysis
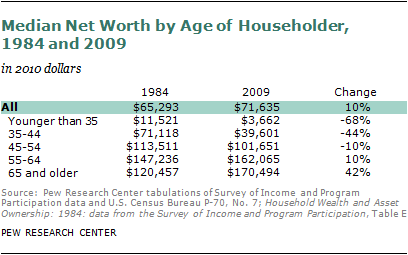
| Metric | U.S. Median Net Worth by Age (2023 Fed Data) |
|---|---|
| Age 25 | $52,000 (but negative for 25% of households due to student debt) |
| Age 35 | $120,000 (white: $180K | Black: $25K | Hispanic: $36K) |
| Age 45 | $250,000 (homeownership accounts for 60% of this figure) |
| Age 55 | $400,000 (top 10%: $1.5M+ | bottom 50%: $50K–$150K) |
| Age 65 | $365,000 (but 40% of retirees rely on Social Security alone) |
Future Trends and Innovations
The next decade will redefine "how much net worth by age" through three major shifts. First, AI-driven financial tools will personalize benchmarks with eerie precision—your net worth target won’t just be based on age, but on your specific DNA, spending habits, and even social media activity. Companies like Betterment and Wealthfront are already using algorithms to adjust portfolios in real time, but the next step is predictive net worth modeling—telling you not just what you have, but what you could have if you pivot careers or invest in a specific asset class. Second, debt will fragment. The student debt crisis has already created a "lost generation" where net worth by age declines in the 30s for many. But new models—like income-share agreements (ISAs) or employer-sponsored education repayment—could reshape the equation. The catch? These programs often come with strings attached (e.g., working for the same company for X years), turning debt into indentured servitude. The question isn’t "Will net worth by age rise?" but "Who will own the levers that control it?" Finally, geographic arbitrage will dominate. Cities like Austin, Nashville, and Raleigh are seeing net worth growth rates 2–3x higher than legacy hubs due to lower costs and remote-work flexibility. Meanwhile, coastal cities are pricing out entire generations. The future of "how much net worth by age" won’t just be about how much you earn, but where you earn it.
Conclusion
The myth of "how much net worth by age" is that it’s a solo endeavor. In reality, it’s a team sport—and the team you’re on is often determined at birth. The numbers tell a story: white families see their net worth grow 16% per year on average, while Black families see just 1.5%. That’s not a failure of personal finance; it’s a failure of systemic design. The goal shouldn’t be to hit arbitrary benchmarks, but to understand the game’s rules and advocate for a fairer board. That said, the data also shows that small, consistent actions compound. A 2021 study found that people who automated savings—even at $50 a month—ended up with 30% higher net worth by age 40 than those who relied on willpower. The key isn’t to obsess over the numbers, but to build systems that work for you, not against you. Whether that’s rentvesting in a high-opportunity city, side-hustle stacking, or negotiating employer retirement matches, the path isn’t one-size-fits-all. But the destination—financial freedom on your own terms—is worth fighting for.Comprehensive FAQs
Q: Is it realistic to have $1M in net worth by age 40?
A: Only for the top 10% of earners. According to the Federal Reserve, 90% of Americans under 40 have less than $100K in net worth. Hitting $1M by 40 typically requires high-income skills (e.g., medicine, tech, law), aggressive asset accumulation (real estate, stocks), or inheritance. Most financial planners suggest aiming for $500K–$750K by 40 as a more achievable "financial independence" target.
Q: Does net worth by age vary by country?
A: Dramatically. In Sweden, the median net worth for a 45-year-old is $250K, while in India, it’s $5K. The U.S. sits in the middle, but with wild regional disparities. For example, a 35-year-old in San Francisco might have $300K, while one in Detroit could have $50K. Factors like tax policy, healthcare costs, and housing markets play a huge role.
Q: Can you build significant net worth without a high-paying job?
A: Yes, but it requires leverage and time. Case studies show freelancers, artists, and entrepreneurs can hit $500K+ by 50 through reinvested profits, asset appreciation, or passive income. The key is cash flow consistency—even $2K/month in profit, reinvested at 8% annually, grows to $500K in 25 years. However, this path is riskier and often involves longer hours or delayed gratification.
Q: How does divorce affect net worth by age?
A: Devastatingly. Studies show that women’s net worth drops by 45% post-divorce, while men’s drops by 23%. The reason? Alimony is often front-loaded, and women are more likely to take the primary residence (which may require refinancing). A 2022 study found that divorced individuals under 50 have, on average, 30% less net worth than their married peers—even when controlling for income.
Q: Is it better to focus on net worth or cash flow?
A: Cash flow wins in the short term; net worth wins in the long term. If you’re under 40, prioritizing cash flow (saving, debt payoff, side income) is critical because liquid assets protect you from emergencies. After 40, net worth growth (via investments, real estate) becomes more important. The ideal balance is 60% cash flow focus before 40, 60% net worth focus after 50.
Q: How does inflation distort "how much net worth by age" benchmarks?
A: Severely. A net worth of $200K in 1990 would be worth $450K today if it kept pace with inflation. But most benchmarks don’t adjust for inflation, leading to false optimism. For example, the "Fidelity Rule" (net worth = age × income) assumes 3% annual growth—but in high-inflation periods (like 2022–2023), you’d need 5–7% growth just to break even. Always inflation-adjust benchmarks when comparing across decades.
Q: Can you "catch up" in net worth by age if you started late?
A: Yes, but it requires extreme discipline. The "catch-up" strategy involves:
- Maxing out 401(k) catch-up contributions ($7,500/year after 50).
- Investing in high-growth assets (e.g., small-cap stocks, real estate).
- Avoiding lifestyle inflation—even if income rises.
Q: What’s the biggest myth about "how much net worth by age"?
A: That it’s purely about effort. The biggest myth is that hard work alone determines net worth by age. In reality, birth year, zip code, and family wealth account for more variance than savings rate. For example, a child of doctors is 10x more likely to become a doctor (and thus earn more) simply due to exposure and networking. The system is rigged for those who already have a leg up—and the data proves it.
