
The Short Answers
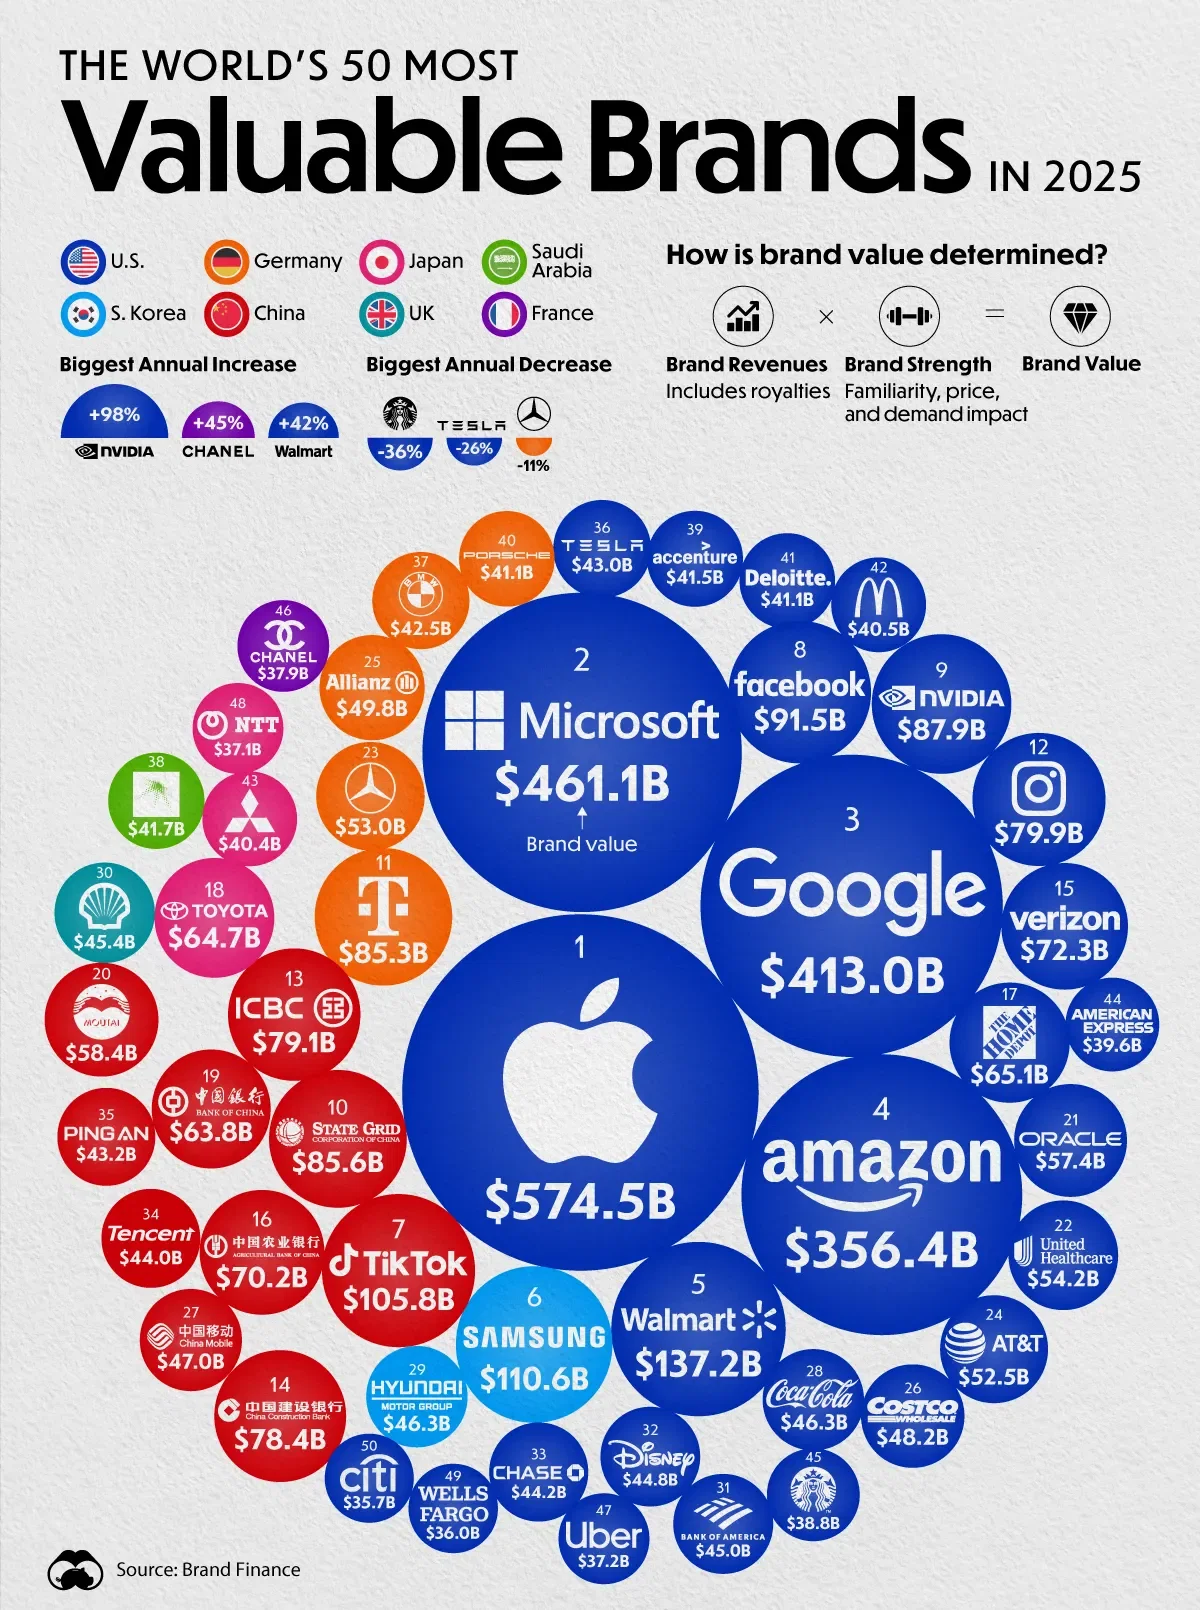
- Apple is the brand with the highest global net worth, with a market cap exceeding $3 trillion.
- Its dominance stems from iPhone profits, services revenue, and aggressive financial management.
- No other brand—tech, luxury, or energy—has closed the valuation gap in over a decade.
- Microsoft and Saudi Aramco are distant second and third, but neither approaches Apple’s scale.
- Brand equity (Apple’s ability to charge premium prices) is a key factor in its outperformance.

Deep Dive: The Full Picture
Apple’s lead in what brand currently has the highest global net worth isn’t just about size—it’s about control. The company doesn’t just sell devices; it owns the pipelines through which users interact with technology. When you factor in the App Store’s 30% cut, Apple’s share of the digital economy rivals that of traditional media conglomerates. This dual revenue stream (hardware + services) creates a flywheel effect: more iPhones sold means more developers pay to reach users, which in turn makes the iPhone ecosystem stickier. Competitors like Samsung or Google can’t replicate this because their software and hardware are often fragmented. The financial engineering behind Apple’s valuation is equally critical. Unlike most tech firms that reinvest aggressively, Apple treats its cash like a war chest. It uses debt strategically—borrowing to buy back shares when markets dip, thereby inflating its per-share value. This contrasts with rivals like Tesla, which burns cash on expansion, or Amazon, which prioritizes growth over shareholder returns. Even in downturns, Apple’s disciplined approach ensures its market cap remains insulated. The result? A brand that doesn’t just lead in valuation but does so with predictable, recession-resistant profits.The Context You Need
To understand why what brand currently has the highest global net worth is Apple—and not, say, a state-owned oil giant or a luxury conglomerate—you need to grasp two things: market capitalization vs. revenue, and the halo effect of brand power. Revenue rankings are dominated by companies like Walmart or Shell, but their valuations reflect asset-heavy businesses (real estate, oil reserves) rather than intellectual property. Apple, by contrast, is valued like a tech growth stock, even as it matures. Its intangible assets—patents, design language, and ecosystem lock-in—are worth more than its factories or inventory. The second context is timing. Apple’s peak valuation coincides with the post-iPhone era, where smartphones became the primary device for work, entertainment, and social interaction. This shifted consumer behavior from one-time purchases to subscription-based loyalty. Apple’s services—from Apple TV+ to Apple Pay—aren’t just ancillary; they’re the glue that binds users to its hardware. When you combine this with China’s manufacturing dominance (where Apple designs but doesn’t own factories), the result is a business model that outsources risk while capturing all the upside.The Mechanics
The mechanics of Apple’s valuation are less about innovation and more about financial alchemy. Take its supply chain, for example: Apple doesn’t own Foxconn, but it dictates terms that ensure margin protection. When component costs rise, Apple absorbs the hit internally rather than passing it to consumers—until it can renegotiate contracts. This discipline extends to R&D. While competitors like Google or Meta spend billions on AI, Apple’s R&D budget (~$20 billion annually) is focused on incremental upgrades that feel revolutionary to users. The result? Products that sell themselves through word-of-mouth, reducing marketing costs. Then there’s the shareholder-friendly structure. Apple’s board prioritizes share buybacks over dividends, a strategy that artificially lifts its stock price by reducing outstanding shares. During the 2020–2022 period, Apple spent $100 billion on buybacks, a move that benefited institutional investors more than retail shareholders. This isn’t philanthropy—it’s a way to keep the stock price elevated, ensuring the company’s valuation stays ahead of peers. Even in downturns, Apple’s ability to defer taxes via offshore cash (a practice under scrutiny but legally permitted) adds another layer of financial insulation.Details That Change the Picture
The narrative of what brand currently has the highest global net worth is often simplified as "Apple = iPhone." But the reality is more nuanced. Consider Apple’s services business, which now accounts for 20% of revenue—a figure that grows as emerging markets adopt digital payments and streaming. In India, for instance, Apple Pay’s adoption is outpacing competitors because it’s tied to the iPhone’s ecosystem. This isn’t just a revenue stream; it’s a moat. No other brand can replicate the combination of hardware, software, and services in a single package. Another detail? Regulation. Apple’s valuation is increasingly tested by antitrust scrutiny. The EU’s Digital Markets Act and U.S. lawsuits over App Store fees threaten to erode its ecosystem profits. If forced to allow third-party app stores or reduce commission rates, Apple’s services revenue could shrink by $10–15 billion annually—enough to dent its market cap. Yet even in this scenario, Apple’s scale ensures it would remain the world’s most valuable brand. The question isn’t whether it will fall; it’s how much."Apple’s valuation isn’t just about the iPhone. It’s about the illusion of scarcity—making users believe they need the latest model, not just a functional phone." — Ben Thompson, Stratechery
| Brand | Estimated Market Cap (2024) |
|---|---|
| Apple | $3 trillion |
| Microsoft | $2.8 trillion |
| Saudi Aramco | $2.2 trillion |
Conclusion
The brand that currently holds the title of what brand currently has the highest global net worth does so not by accident, but by design. Apple’s playbook—combining hardware monopoly, services dominance, and financial discipline—is a blueprint for how to turn a single product (the iPhone) into a global economic force. Even as competitors like Microsoft or Amazon chase its valuation, they lack the ecosystem lock-in that Apple wields. The company’s ability to charge premium prices, suppress competition, and engineer its balance sheet ensures its lead will persist—unless regulatory forces intervene in ways that redefine the rules of the game. Yet for all its dominance, Apple’s valuation is a double-edged sword. The higher the market cap, the more scrutiny it faces from governments and competitors. If antitrust actions succeed in breaking up its ecosystem, or if China’s geopolitical tensions disrupt its supply chain, the $3 trillion figure could shrink. But for now, Apple remains the undisputed king of brand valuation—a title it has earned through a mix of innovation, financial acumen, and an almost religious devotion from its customer base.Comprehensive FAQs
Q: Could Microsoft or Amazon overtake Apple’s valuation?
Unlikely in the near term. Microsoft’s valuation is driven by cloud computing (Azure) and enterprise software, while Amazon’s is tied to e-commerce and AWS—both cyclical businesses. Apple’s hardware-services hybrid model is harder to replicate, and its brand premium ensures it captures a larger share of consumer spending on tech.
Q: How does Apple’s valuation compare to luxury brands like LVMH?
Apple’s market cap dwarfs LVMH’s (~$400 billion). Luxury brands rely on physical goods and brand prestige, while Apple’s value comes from intellectual property, ecosystem control, and recurring revenue. Even if LVMH’s revenue were higher, its valuation would still lag because it lacks Apple’s scalable digital infrastructure.
Q: Does Apple’s stock price accurately reflect its true worth?
Not entirely. Apple’s market cap is inflated by share buybacks and tax deferrals, which artificially boost its per-share value. A more conservative valuation might subtract its offshore cash reserves (~$190 billion) and adjust for regulatory risks, potentially lowering its "true" worth by 10–15%. However, even this adjusted figure would still surpass Microsoft’s.
Q: Why isn’t Tesla in the top 5 most valuable brands?
Tesla’s valuation is volatile because it’s growth-driven, not profit-driven. While its market cap fluctuates between $500 billion and $700 billion, it lacks Apple’s stable cash flows and services revenue. Tesla’s value depends on EV adoption rates and manufacturing efficiency—factors that introduce far more variability than Apple’s ecosystem model.
Q: What would it take for Apple to lose its #1 spot?
Three scenarios: (1) Regulatory breakdown—if antitrust actions force Apple to open its ecosystem, services revenue could drop by $10–15 billion annually. (2) iPhone decline—if China’s market shifts away from Apple or a competitor invents a superior device. (3) Macro shock—a prolonged recession that hits discretionary tech spending harder than essential services. Even then, Apple’s financial cushion would likely keep it ahead of Microsoft.
