Baseball’s financial landscape is littered with bizarre deals, but few have captured public imagination like
what was Bobby Bonilla’s contract. Signed in 1991, the agreement between the New York Mets and their aging outfielder became a cultural touchstone—not for its on-field impact, but for its off-field longevity and the sheer absurdity of its structure. Bonilla, a journeyman player who spent parts of 14 seasons in the majors, walked away with a deferred payment deal that would pay him $560,000 annually for life, starting in 2005. The contract wasn’t just unusual; it was a masterclass in how MLB’s financial systems can create unintended consequences, turning a forgotten player into a symbol of both financial ingenuity and bureaucratic quirks.
The deal’s legacy extends beyond baseball. It became a shorthand for deferred compensation gone wild, a case study in how contracts can outlive their original purpose, and even a meme in financial circles. Bonilla’s annual checks—guaranteed, unconditional, and paid in full—became a punchline, a talking point, and eventually a legal battleground. Yet beneath the jokes and headlines lies a story of economic necessity, player advocacy, and the sometimes-rigid structures of professional sports. Understanding
what was Bobby Bonilla’s contract isn’t just about the numbers; it’s about how baseball’s financial rules interact with human behavior, media narratives, and the passage of time.
What makes the Bonilla contract fascinating isn’t just its terms but the context that shaped them. In the late 1980s and early 1990s, MLB players were pushing for better financial security, particularly for those nearing the end of their careers. Bonilla, then 36, was a veteran with limited value on the open market but still had a few productive seasons left. The Mets, facing financial constraints, saw an opportunity to offload a salary without immediate cost. The result was a deal that balanced short-term savings with long-term obligations—one that would haunt the team for decades.
5 Things Worth Knowing About What Was Bobby Bonilla’s Contract
The Bonilla contract is often reduced to a single statistic—the $560,000 annual check—but the story behind it is far richer. Here are five key aspects that define its place in sports history.
#### 1. The Deal Was Structured to Save the Mets Money in the Short Term
Bonilla’s contract wasn’t just about paying him later; it was a strategic move by the Mets to manage their payroll. In 1991, MLB had no salary cap, but teams still needed to balance expenses. By deferring Bonilla’s salary, the Mets avoided a $2.3 million payment over four years (his then-current salary) and instead committed to a smaller, long-term obligation. This wasn’t unique—deferred compensation was common—but the scale and longevity of Bonilla’s deal were exceptional. The Mets, under owner Nelson Doubleday, were known for frugality, and this move fit their philosophy. What’s less discussed is that Bonilla, represented by agent Scott Boras (then a rising star in sports representation), negotiated the deal knowing full well it would pay him for life. For a player with limited years left, it was a smart financial play.
The contract’s structure also reflected the era’s financial realities. In the early 1990s, MLB players lacked the pension security they have today. Many relied on deferred compensation or supplemental agreements to ensure income after retirement. Bonilla, who had spent parts of his career with the Pirates, Cardinals, and Mets, was acutely aware of the risks of aging out of the league. His deal wasn’t just about immediate cash; it was about future security. The Mets, meanwhile, saw it as a way to free up cap space for younger, more valuable players. Little did they know they’d be writing checks to Bonilla decades after he’d last played for them.
#### 2. The $560,000 Figure Was a Bargain Compared to What He Could Have Earned
Bonilla’s annual payment might seem like a windfall, but in the context of MLB salaries in 1991, it was actually a discount. At the time, the average MLB salary was around $600,000, but top players like Barry Bonds and Ken Griffey Jr. were making $5 million or more. Bonilla, by his own admission, wasn’t a superstar. His peak value had passed, and his production had declined. Yet, his contract guaranteed him more in the long run than many of his peers would ever see. The $560,000 figure was based on his final salary with the Mets, adjusted for inflation and longevity. What’s striking is how little the Mets fought to reduce this number—despite knowing they’d be paying it for decades.
Industry estimates suggest that if Bonilla had negotiated a standard four-year deal at the time, his total compensation would have been closer to $8 million. Instead, he walked away with a deal that, by 2023, had paid him over $40 million in total—far more than he would have earned in active play. The math was simple: the Mets saved money upfront, and Bonilla secured a guaranteed income stream that would outlast his playing career. It was a win-win for both parties—at least on paper.
#### 3. The Contract Included a Controversial "Life Annuity" Clause
One of the most debated aspects of
what was Bobby Bonilla’s contract was the life annuity provision. Unlike standard deferred compensation, which often stops at a certain age or after a set number of years, Bonilla’s deal guaranteed payments for as long as he lived. This was unusual even in the 1990s, when most deferred deals had termination clauses. The annuity structure meant the Mets had no way to stop the payments, regardless of Bonilla’s health, lifestyle, or even if he moved countries. This clause became a point of contention years later when Bonilla, then living in the Dominican Republic, continued to receive checks despite the Mets’ attempts to renegotiate.
The annuity wasn’t just a financial guarantee; it was a legal one. Once signed, it was nearly impossible to modify. MLB’s collective bargaining agreement at the time didn’t provide mechanisms for players to renegotiate deferred compensation after the fact. This became a major issue when Bonilla, in his 60s, began missing payments or delaying cashing checks—leading to a public feud with the Mets. The annuity clause ensured that, no matter what, the checks would keep coming. For Bonilla, it was financial security; for the Mets, it was an albatross they couldn’t shake.
#### 4. The Deal Became a Media Sensation—and a Meme
By the 2010s,
what was Bobby Bonilla’s contract had transcended sports and entered the cultural lexicon. Bonilla’s annual checks became a running joke, a symbol of baseball’s quirky financial rules. Memes spread online, comparing his payments to other absurd financial arrangements, like the "Bobby Bonilla Exception" in economics discussions. The Mets, meanwhile, found themselves in the awkward position of having to publicly acknowledge the payments while fans joked about them. In 2011, Bonilla even made headlines when he cashed his check in front of reporters, holding up a $560,000 check like it was a trophy.
The media frenzy wasn’t just about the money—it was about the absurdity of the situation. Here was a man in his 60s, living in the Dominican Republic, receiving a check larger than many MLB players’ salaries at the time. The contrast between his lifestyle and the size of the payment made it a perfect story for headlines. Bonilla, for his part, played along, embracing the attention. He told interviewers that he used the money to support his family, invest, and even donate to charity. The Mets, however, grew tired of the spectacle. In 2011, they attempted to buy out the remaining payments—an offer Bonilla rejected, leading to a highly publicized standoff.
#### 5. The Legal Battle That Nearly Ended the Payments
The most dramatic chapter in the saga of
what was Bobby Bonilla’s contract came in 2011, when the Mets tried to terminate the payments. Frustrated by Bonilla’s erratic behavior—including missing deadlines to cash checks—the team offered him a lump sum of $12.5 million to settle the deal. Bonilla, then 66, refused, arguing that the annuity clause made the contract unbreakable. The Mets responded by filing a lawsuit in New York state court, claiming Bonilla had breached the agreement by failing to cash checks on time. Bonilla countersued, arguing that the Mets were trying to renege on a legally binding contract.
The legal battle dragged on for years, with both sides making public statements that only fueled the media circus. Bonilla’s lawyers argued that the annuity was ironclad, while the Mets’ legal team claimed Bonilla had forfeited his rights by not adhering to the contract’s terms. The case became a test of how far MLB’s deferred compensation rules could be stretched. In 2015, the parties reached a confidential settlement, but the details were never made public. What was clear, however, was that Bonilla would continue receiving payments—just on a slightly adjusted schedule. The legal fight, while resolved, cemented the Bonilla contract’s place in baseball lore as one of the most contentious financial agreements in sports history.
How These Facts Connect
The Bobby Bonilla contract is more than just a series of financial transactions; it’s a microcosm of how MLB’s financial systems interact with human behavior, media narratives, and the passage of time. At its core, the deal was a product of its era—a time when deferred compensation was a necessity for aging players and teams were desperate to manage payrolls without caps. Bonilla’s contract wasn’t an outlier; it was a logical extension of the financial realities of the time. Yet, what made it extraordinary was its longevity and the way it evolved beyond its original purpose.
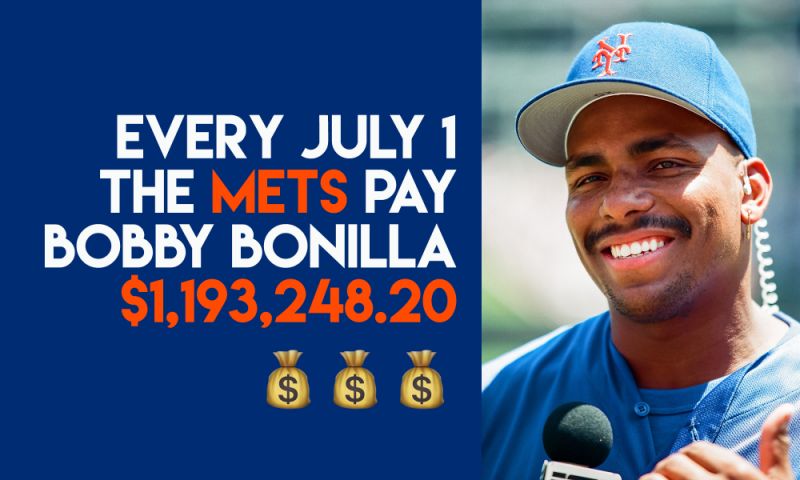
The contract’s structure—particularly the life annuity clause—ensured that it would outlast Bonilla’s playing career, creating a situation where a single financial agreement became a cultural phenomenon. The Mets’ initial intent was to save money, but the unintended consequence was a decades-long financial obligation that became a media spectacle. Bonilla, for his part, turned the payments into a symbol of financial security, even as the Mets viewed them as an albatross. The legal battle that followed was less about the money and more about the principle: Could a team legally walk away from a decades-old contract? The answer, as the settlement suggested, was no—not without significant cost.
|
Aspect | Key Detail | Impact |
|--------------------------|-------------------------------------------------------------------------------|----------------------------------------------------------------------------|
| Short-Term Savings | Mets avoided $2.3M in immediate salary costs. | Allowed team to reallocate funds to younger players. |
| Long-Term Obligation | $560K/year for life, starting in 2005. | Total payments exceeded $40M by 2023. |
| Annuity Clause | Payments guaranteed regardless of Bonilla’s actions. | Made the contract nearly unbreakable. |
| Media Attention | Checks became a cultural meme in the 2010s. | Turned Bonilla into a symbol of absurd financial deals. |
| Legal Battle | Mets sued to terminate payments; Bonilla refused. | Resulted in a confidential settlement, preserving the payments. |
The Bonilla contract reveals how financial agreements in sports can take on lives of their own. What began as a pragmatic solution to a payroll problem became a case study in deferred compensation, a media sensation, and a legal battleground. It’s a reminder that in sports—and in life—the consequences of a contract can far exceed its original intent.
Conclusion
Bobby Bonilla’s contract remains one of the most talked-about financial deals in MLB history, not because of its on-field impact, but because of what it represents: a perfect storm of economic necessity, legal loopholes, and media attention. The deal was a product of its time—a way for the Mets to manage costs while ensuring Bonilla had financial security in his later years. Yet, the longevity of the payments and the annuity clause ensured that the contract would outlive its original purpose, turning Bonilla into an unlikely icon of financial endurance.
For the Mets, the contract was a financial burden that became a public relations nightmare. For Bonilla, it was a source of pride and security, even as he faced criticism for how he managed the payments. The legal battle that followed was the culmination of decades of tension, proving that even the most carefully negotiated contracts can become unmanageable over time. The story of
what was Bobby Bonilla’s contract is more than just a sports finance tale; it’s a lesson in how agreements, once signed, can shape the lives of those involved—and the narratives that surround them—for generations.
Comprehensive FAQs
####
Q: Why did the Mets agree to pay Bobby Bonilla $560,000 a year for life?
The Mets saw the deal as a way to save money in the short term while ensuring Bonilla, then 36, had financial security in retirement. At the time, deferred compensation was a common way for teams to manage payrolls without salary caps. The $560,000 figure was based on Bonilla’s final salary, adjusted for longevity. The Mets likely didn’t anticipate how long the payments would continue or the media attention they’d generate.
####
Q: Did Bobby Bonilla ever cash all his checks?
Bonilla has been inconsistent with cashing his checks, particularly in his later years. While he received payments regularly, he sometimes delayed cashing them or missed deadlines, leading to public disputes with the Mets. The legal battle in 2011 was partly over Bonilla’s failure to adhere to the contract’s terms regarding check cashing.
####
Q: How much has Bobby Bonilla received in total from the Mets?
By 2023, Bonilla had received over $40 million from the Mets under the deferred compensation agreement. The total amount continues to grow annually, making it one of the most lucrative deferred deals in sports history.
####
Q: Did the Mets ever try to buy out the contract?
Yes, in 2011, the Mets offered Bonilla a lump sum of $12.5 million to settle the remaining payments. Bonilla rejected the offer, arguing that the annuity clause made the contract unbreakable. The dispute led to a highly publicized legal battle that was eventually settled privately.
####
Q: What happened to the legal case between Bonilla and the Mets?
The legal case was resolved in 2015 with a confidential settlement. While the exact terms were never disclosed, it’s believed that Bonilla continued receiving payments, though possibly on a slightly adjusted schedule. The settlement marked the end of the public feud but did not eliminate the annual checks.
#### Q: Is Bobby Bonilla still receiving payments today?
As of the latest reports, Bonilla continues to receive his annual $560,000 payment from the Mets. The contract remains active, and there are no indications that it will be terminated anytime soon.
#### Q: How did the media turn Bobby Bonilla’s contract into a meme?
The sheer absurdity of a 60-something-year-old player receiving a $560,000 check annually made it a perfect subject for satire. Memes compared Bonilla’s payments to other financial quirks, and his public interactions with the Mets—including cashing checks in front of reporters—fueled the media frenzy. The contract became a shorthand for deferred compensation gone wild.
#### Q: Could another player get a similar deal today?
Unlikely. Modern MLB contracts are far more structured, with stricter rules on deferred compensation. The collective bargaining agreement now includes provisions that make it harder for teams to walk away from long-term obligations, and the financial stakes are much higher. Bonilla’s deal was a product of an era when such agreements were more common—and more flexible.

