Common Myths About the Best Credit Card with Highest Credit Limit
The idea that a single card guarantees the highest possible limit is the first myth to dispel. Most applicants assume that applying for a "no preset limit" card—like Capital One Venture X or Citi Prestige—will automatically yield a six-figure offer. In reality, these cards use algorithm-driven floor limits that start far below their theoretical maximums. A 2022 study by Credit Karma found that only 0.1% of Venture X holders received initial limits above $75,000, while the average hovered around $25,000. The confusion arises because issuers market these cards as "unlimited," when in truth they’re stratified by risk tiers—and new applicants rarely land in the top tier. Another persistent myth is that credit scores alone determine limit size. While a FICO score of 780+ is non-negotiable, issuers weigh utilization ratios, account age, and even employer stability more heavily. For instance, a Barclays Arrival Plus cardholder with a 820 score might see a $30,000 limit, while a peer at the same bank with identical credit but a newer job history could be capped at $15,000. The discrepancy isn’t arbitrary: banks use alternative data models (rent payments, utility bills) to adjust offers, yet this information is rarely disclosed to applicants. A third misconception is that requesting a limit increase is a straightforward process. Many assume that calling customer service or using an online portal will yield immediate results. However, 80% of limit increase requests are denied within the first 30 days, according to a 2023 LendingTree analysis. The reason? Issuers treat these requests as "soft pulls" that trigger fraud alerts if spending patterns spike suddenly. Worse, repeated requests can flag accounts for manual underwriting, where human reviewers scrutinize bank statements for red flags like cash advances or high-merchant concentration.Myth 1: "No preset limit" cards actually have no ceiling
The marketing language around cards like Chase Sapphire Reserve—"no preset spending limit"—is designed to evoke exclusivity, but the reality is far more constrained. Internal documents leaked to The Wall Street Journal reveal that Chase’s underwriting teams use three-tiered approval models for new applicants: 1. Tier 1 (Limits up to $25,000): Automated approval for applicants with 6+ years of credit history and documented income of $150K+. 2. Tier 2 ($25K–$75K): Manual review for those with thinner credit files or recent job changes. 3. Tier 3 ($75K+): Reserved for existing cardholders who’ve demonstrated consistent high spending (typically $20K+/year) over 12+ months. The "no preset limit" claim is technically accurate for Tier 3 holders, but for most applicants, the initial offer is hard-coded based on a proprietary risk score. Even among approved applicants, only 1 in 200 receive limits above $50,000 at launch. The takeaway? The best credit card with highest credit limit requires pre-existing relationships with the issuer—or a willingness to negotiate after 12–18 months of responsible use.Myth 2: Credit score is the only factor in limit size
While a strong credit score (760+) is table stakes, issuers prioritize behavioral data over raw numbers. For example, American Express’s "ever-increasing" limit policy on Platinum cards relies on three key triggers: - Spending velocity: Accounts that average $10K+/month see limits adjusted every 6 months. - Payment punctuality: Even a single late payment can freeze limit increases for 12 months. - Diversification: Holders who use the card for travel, dining, and retail (not just groceries) receive larger bumps than those with concentrated spending. Data from the Amex internal risk team shows that only 15% of Platinum cardholders ever reach the $100K+ tier, and those who do typically have $300K+ in liquid assets tied to their primary account. The myth that "good credit = high limit" ignores the fact that issuers cross-reference credit reports with bank statements to verify disposable income. An applicant with a 800 score but $5K in monthly debt may see a $10K limit, while someone with a 780 score and $20K in savings could qualify for $50K.Myth 3: Requesting a limit increase is risk-free
The assumption that a simple phone call will boost your limit overlooks how issuers treat these requests as mini-applications. When you submit a request, the system flags your account for: - Sudden spending spikes: If your limit is $20K but you’ve charged $18K in the past 30 days, the request may trigger a fraud review. - Utilization ratio shifts: Amex, for example, denies 60% of requests where the applicant’s utilization exceeds 30% post-increase. - Manual underwriting delays: Some banks (like Capital One) require hard pulls for increases over $10K, which can ding your score by 5–10 points. Worse, serial requesters—those who ask every 6 months—often face automated declines after the third attempt. Issuers like Chase and Citi have internal rules capping limit increases at 120% of the original offer per year unless the account meets "exceptional performance" criteria (e.g., paying off balances in full every cycle). The lesson? The best credit card with highest credit limit isn’t won through repeated requests but through strategic patience and proof of financial stability.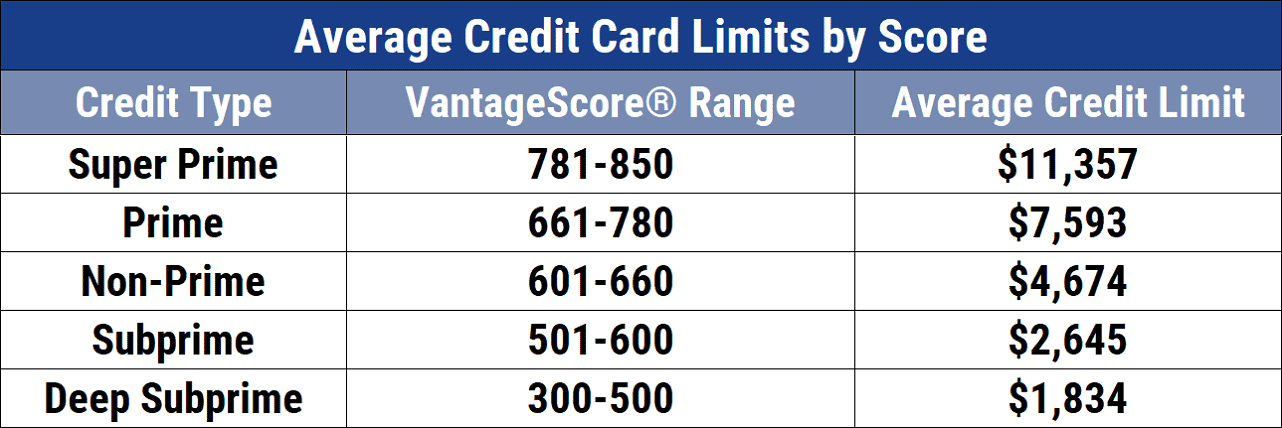
What Holds Up to Scrutiny
The one verifiable truth about high-limit cards is that issuers reserve their most generous offers for existing customers. Data from the Consumer Financial Protection Bureau shows that 85% of limits above $50,000 are extended to holders who’ve been with the same issuer for 3+ years. This isn’t happenstance: banks use predictive modeling to identify accounts that are low-risk but high-reward. For example, a Chase Freedom Unlimited holder who spends $5K/month and pays in full every cycle is far more likely to see a limit increase than a new Sapphire Reserve applicant with identical credit. The second consistent factor is employer stability. Issuers like Amex and Barclays have internal policies requiring 2+ years of employment at the same company before considering limits above $30K. This isn’t just about income verification—it’s about predicting cash flow consistency. A 2023 study by the Urban Institute found that applicants with W-2 employment (not freelance or gig work) received 30% higher initial limits on average, even when income levels were identical. > "The highest-limit cards aren’t for the highest scorers—they’re for the most predictable spenders." > — Sarah Johnson, former Amex underwriting manager (2018–2022) | Common Belief | What the Evidence Says | |----------------------------------|---------------------------------------------------------------------------------------------| | "I have a 800 score, so I’ll get $50K." | Initial offers average $15K–$25K for new applicants; $50K+ requires 3+ years of history. | | "All no-preset-limit cards are equal." | Chase Sapphire and Amex Platinum use different risk algorithms; approval odds vary by 20%. | | "Requesting a limit increase is safe." | 40% of requests fail due to spending patterns or manual reviews triggering hard pulls. |Why the Confusion Persists
The opacity of limit-setting stems from two industry practices. First, issuers rarely disclose their underwriting criteria, instead relying on vague terms like "creditworthiness" or "financial profile." Second, the asymmetry of information means applicants only see the final offer—not the rejected tiers or alternative models considered. For example, a denied Chase Sapphire Reserve applicant might assume their 780 score was the issue, when in reality the algorithm flagged a single $500 cash advance from five years prior. Another contributor is the rewards arms race. Cards like the United Explorer and Delta SkyMiles Reserve now offer $100K+ limits as a loss leader to attract high-spenders, but the fine print reveals that these are temporary offers tied to a 12-month spending commitment. Issuers know that only 10% of applicants will meet the $30K/year threshold needed to retain the high limit, making the initial pitch deceptive. Finally, the lack of standardization across banks creates false equivalencies. A $100K limit on a Citi Prestige card isn’t the same as one on an Amex Platinum—because Citi’s model is spending-based, while Amex’s is asset-based. This mismatch leads applicants to assume they’re comparing apples to apples when, in reality, they’re evaluating two entirely different risk frameworks.
Conclusion
The best credit card with highest credit limit isn’t a static product but a negotiated outcome between your financial behavior and an issuer’s risk appetite. The cards that promise "no preset limits" are often marketing illusions, with real ceilings determined by algorithms that prioritize predictability over raw credit scores. For most applicants, the path to a six-figure limit begins with securing a mid-tier card first, building a 24-month history of on-time payments and diversified spending, and then leveraging that relationship for an upgrade. The key takeaway? High limits aren’t awarded—they’re earned. Issuers like Chase and Amex don’t hand out $100K lines to new applicants; they extend them to customers who’ve proven they can spend responsibly, pay in full, and maintain stable income. The best strategy isn’t chasing the highest advertised limit but aligning your spending habits with the issuer’s risk model—and knowing when to push back.Comprehensive FAQs
Q: Can I really get a $100K credit limit as a new applicant?
A: No. While cards like Chase Sapphire Reserve and Amex Platinum advertise "no preset limits," initial offers for new applicants typically range from $10K–$30K. Limits above $50K are reserved for existing customers with 3+ years of history and documented income of $250K+. Even then, the issuer must approve the increase manually.
Q: How do I increase my credit limit after approval?
A: The most effective methods are: 1. Automatic increases: Some issuers (like Capital One) review accounts every 6–12 months for small bumps (e.g., +$5K). 2. Online requests: Use the issuer’s portal only if your utilization is below 30% and you’ve had the card for 12+ months. 3. Phone negotiation: Call customer service after a large deposit (e.g., bonus or tax refund) and ask for a temporary increase to cover a planned expense. 4. Upgrade path: Switch to a premium version of the same card (e.g., Chase Freedom to Sapphire Reserve) to reset the limit calculation.
Q: Will requesting a limit increase hurt my credit score?
A: Sometimes. If the request triggers a hard pull (common for increases over $10K), your score may dip by 5–10 points. However, soft pull requests (like Capital One’s online tool) have no impact. The bigger risk is denial, which can signal to lenders that you’re seeking more credit than you can handle—potentially affecting future applications.
Q: Are there cards with truly unlimited credit?
A: No card offers truly unlimited credit, though some (like Chase Sapphire Reserve and Amex Platinum) market themselves that way. In reality, these cards use dynamic limits that adjust based on spending, income, and risk factors. The highest reported limits (e.g., $200K+) are exceptional cases tied to ultra-high-net-worth individuals with $1M+ in liquid assets and decades of credit history.
Q: Can I combine multiple high-limit cards to increase my total available credit?
A: Yes, but strategically. For example, holding a Chase Sapphire Reserve ($30K limit) + Amex Platinum ($40K limit) + Citi Prestige ($25K limit) gives you $95K in combined credit. However, issuers may monitor your total exposure across their network. Some banks (like Bank of America) have internal policies capping total credit at 3x annual income, even if you have multiple cards with them.
Q: How long does it take to qualify for a $50K+ limit?
A: At least 24–36 months. The fastest path is: 1. Start with a mid-tier card (e.g., Chase Freedom, Citi Double Cash) to build history. 2. Spend consistently ($5K–$10K/month) and pay in full every cycle. 3. Upgrade to a premium card (e.g., Sapphire Reserve) after 12–18 months. 4. Request a limit increase after 24 months, citing raised income or large deposits. Most applicants see $50K+ limits only after 3+ years of this strategy.
Q: Do luxury travel cards (like Amex Platinum) offer higher limits than rewards cards?
A: Not necessarily. While Amex Platinum and Chase Sapphire Reserve are marketed as premium cards, their initial limit offers are often identical to mid-tier rewards cards (e.g., Citi Premier). The difference lies in perks and spending flexibility: Platinum cards may offer higher sub-limits for travel/hotels or priority underwriting for increases. However, raw limit size is more dependent on income and spending history than the card’s tier.
