
7 Things Worth Knowing About the Average Net Worth of Physicians
The average net worth of physicians isn’t a static figure—it’s a reflection of systemic pressures, personal discipline, and the evolving landscape of healthcare economics. From the crushing weight of student debt to the windfalls of niche specialties, these seven factors redefine what "wealth" means for doctors.1. Medical school debt erodes early-career net worth
The average net worth of physicians in their 30s is often negative. A 2024 analysis by the Association of American Medical Colleges (AAMC) found that 60% of physicians graduate with debt exceeding $200,000, with some specialties—like psychiatry and family medicine—relying heavily on federal loans at rates above 6%. Unlike other professions, physicians enter their peak earning years already in hock, and the repayment timeline can stretch into their 40s. Even high-earning specialties like surgery or dermatology see their net worth growth stunted for the first decade of practice, as loan servicing eats into disposable income. The paradox is that the same specialties with the highest earning potential—orthopedics, ophthalmology, and radiology—also carry the heaviest debt burdens. A 2023 Health Affairs study revealed that orthopedic surgeons, who medianize around $500,000 annually, often take on $300,000+ in loans to fund residency programs with limited stipends. This debt-to-income ratio means it can take 15–20 years for their net worth to turn positive, even with aggressive savings.2. Specialty drives a 10x disparity in wealth accumulation
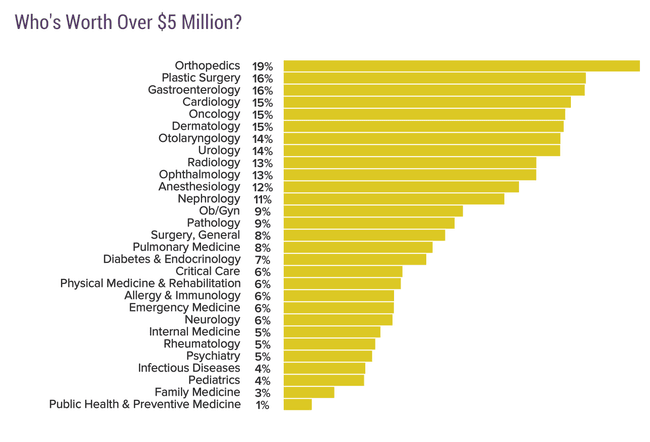
The average net worth of physicians varies by specialty more than by gender or geography. At one extreme, primary care physicians—pediatricians, internists, and family doctors—often see net worth figures below $1 million by age 60, even after decades of practice. At the other end, dermatologists and plastic surgeons frequently report net worths exceeding $3 million by age 50, according to physician wealth surveys. The divide isn’t just about income; it’s about revenue per hour, malpractice risk, and the ability to command premium fees. Specialties with high procedural volumes—like cardiology, orthopedics, and gastroenterology—also benefit from procedure-based billing, which can inflate earnings beyond salary benchmarks. A 2022 Physicians Thrive report estimated that a top-earning dermatologist in a private practice could generate $1.2 million annually in revenue, translating to net worth growth of $150,000–$300,000 per year after expenses. Meanwhile, a hospital-employed general surgeon might see their net worth grow at a fraction of that rate, despite similar hourly wages.3. Location matters more than most assume
The average net worth of physicians in New York or California lags behind that of their peers in Texas or Florida—not because of lower salaries, but due to cost of living, tax burdens, and practice overhead. A 2023 Medical Group Management Association study found that physicians in low-tax states like Tennessee or Arizona accumulate wealth 30–40% faster than those in high-tax states like New Jersey or Massachusetts. The difference isn’t just about take-home pay; it’s about asset protection. In states with high property taxes and malpractice premiums, a physician’s disposable income can shrink by 15–20% before it ever reaches savings. Geographic arbitrage also plays a role. Physicians who relocate to rural or underserved areas often receive signing bonuses, loan repayment incentives, and tax breaks, which can accelerate net worth growth by $500,000–$1 million over a decade. However, the trade-off is frequently lower patient volumes and reimbursement rates, which can offset some of the financial gains.4. Practice ownership unlocks—but also risks—wealth
Physicians who own or co-own practices see their average net worth 2–3x higher than those employed by hospitals or large groups, according to Physicians Practice data. The reason is simple: equity. A solo practitioner or a partner in a multispecialty group owns a tangible asset—real estate, medical equipment, and goodwill—that appreciates over time. A 2023 Becker’s Hospital Review analysis estimated that a well-managed dermatology practice could be valued at $1.5–$3 million, depending on revenue and patient panel size. The flip side is risk. Practice ownership exposes physicians to operational costs, regulatory scrutiny, and malpractice exposure that employed doctors avoid. A single lawsuit or a drop in insurance reimbursements can liquidate years of net worth growth in months. The average net worth of physicians in employed roles grows more steadily but rarely reaches the stratospheric levels of those who take the ownership gamble.5. Investment discipline separates the wealthy from the merely affluent
The average net worth of physicians who actively manage investments outpaces those who rely on savings accounts or employer 401(k)s by 40–50%, per Kitces Financial research. High-net-worth physicians—those with assets exceeding $2 million—typically allocate 60–70% of their investable capital to real estate, private equity, and alternative assets, rather than traditional stock portfolios. The reasoning is twofold: diversification and tax efficiency. Medical malpractice insurance premiums and state income taxes can eat into returns, so assets like real estate (rental properties, medical office buildings) and annuities offer shelter. A common misconception is that physicians simply "save more" than other professionals. In reality, the wealthiest doctors treat their careers as businesses, reinvesting profits into practice expansion, continuing education, and asset acquisition. A 2024 Physicians’ Wealth survey found that 78% of physicians with net worth over $3 million had at least one non-liquid asset (real estate, a secondary practice, or a side business), compared to just 32% of those below $1 million.6. Malpractice and lifestyle inflation eat into long-term gains
The average net worth of physicians is inflated in surveys because it often excludes hidden liabilities. Malpractice insurance premiums for high-risk specialties—obstetrics, surgery, and emergency medicine—can cost $50,000–$150,000 annually, effectively reducing take-home pay by 10–20%. When coupled with lifestyle inflation (private school tuition, luxury real estate, or second homes), the net worth growth rate slows dramatically. A 2023 American Medical Association report noted that physicians in their 40s often see their disposable income stagnate despite rising salaries, as new expenses outpace savings. The psychological cost is often underestimated. Physicians who over-leverage—taking on mortgages, private school loans, or high-maintenance lifestyles—find their net worth flatlining in their 50s, even as peers with conservative spending habits see exponential growth. The average net worth of physicians who delay major purchases (like a primary residence) until their 40s can outpace those who buy early by $1–$2 million by retirement.7. Retirement planning is a moving target
The average net worth of physicians at retirement is not what it used to be. Traditional estimates—based on 20-year career trajectories—no longer apply in an era of early retirement, locum tenens work, and part-time practice. A 2024 Physicians Thrive study found that 40% of physicians retire before age 65, often with lower net worth than expected, due to burnout, changing compensation models, or unexpected health issues. Those who delay retirement past 67 see their net worth accelerate, but only if they’ve structured tax-efficient withdrawals and healthcare cost planning. The shift to defined-contribution retirement plans (like 401(k)s) over traditional pensions has also compressed net worth growth for later-career physicians. Without employer-matched contributions or guaranteed payouts, physicians must self-manage their retirement assets—a task made complex by Medicare premiums, long-term care costs, and inflation. The average net worth of physicians who fail to adjust their portfolios for sequence-of-returns risk can shrink by 30% in retirement, according to BlackRock projections.
How These Facts Connect
The average net worth of physicians isn’t just a reflection of income—it’s a fractal of the profession’s structural tensions. Debt and specialty choice set the initial coordinates, while geography and practice model determine the trajectory. Investment discipline and risk management act as accelerators or brakes, and retirement planning reveals the final reckoning. The wealthiest physicians don’t just earn more; they optimize every lever—from tax-advantaged accounts to asset protection strategies—while mitigating the profession’s unique liabilities. What the data omits is the human cost. A physician with a $5 million net worth may still work 80-hour weeks, fear lawsuits, or struggle with burnout. The average net worth of physicians tells us little about their quality of life—only about their financial resilience. The disconnect between perceived success (high net worth) and actual well-being (stress, debt, burnout) is one of medicine’s most underreported stories.| Factor | Impact on Net Worth | Key Outliers |
|---|---|---|
| Medical School Debt | Delays positive net worth by 10–20 years | Psychiatry, family medicine (high debt, lower earnings) |
| Specialty Selection | 10x disparity between lowest and highest earners | Dermatology vs. primary care |
| Geographic Arbitrage | Low-tax states accelerate wealth by 30–40% | Texas vs. New York |
| Practice Ownership | 2–3x higher net worth, but higher risk | Solo practitioners vs. hospital employees |
Conclusion
The average net worth of physicians is less about what they earn and more about how they deploy it. The profession’s financial landscape is not a level playing field—it’s a series of gambits and trade-offs, where every decision compounds over decades. For early-career doctors, the message is clear: Debt management and specialty choice are the first dominoes. For mid-career physicians, asset diversification and practice structure become critical. And for those nearing retirement, tax-efficient withdrawals and healthcare planning can mean the difference between comfort and crisis. The most striking revelation isn’t the dollar figures themselves, but the silent assumptions they reveal. Medicine’s wealth gap isn’t just about money—it’s about power. Those who control their own practices, optimize their investments, and navigate risk write the rules. The rest follow.Comprehensive FAQs
Q: How does the average net worth of physicians compare to other high-earning professionals?
The average net worth of physicians outpaces that of lawyers, engineers, and executives in their peak earning years (45–55), but lags behind entrepreneurs and tech founders by retirement. A 2023 Federal Reserve Survey of Consumer Finances found that doctors aged 55–64 had a median net worth of $2.3 million, compared to $1.5 million for lawyers and $1.2 million for MBAs. However, physician wealth is more volatile due to malpractice risks and debt burdens.
Q: Can physicians realistically achieve a $5 million net worth before retirement?
Yes, but only in high-earning specialties with aggressive savings and investment strategies. Dermatologists, orthopedic surgeons, and radiologists in private practice frequently hit this mark by age 50–55, while primary care physicians rarely exceed $2 million without side income or inheritance. The key variables are debt payoff speed, practice ownership, and alternative asset allocation (real estate, private equity).
Q: Does being a woman or a person of color affect a physician’s net worth?
Yes, but the impact is indirect. Women physicians earn 20–30% less than male peers in the same specialty, according to JAMA studies, which delays net worth growth by 5–10 years. Physicians of color face additional barriers: lower reimbursement rates in underserved communities, higher malpractice scrutiny, and limited access to high-net-worth networks for investment advice. A 2023 Doximity report found that Black and Hispanic physicians had median net worths 40% lower than white physicians at equivalent career stages.
Q: What’s the biggest mistake physicians make with their money?
Over-leveraging early in their careers. Many physicians take on mortgages, private school loans, or luxury purchases in their 30s, assuming their future earnings will cover the costs. The problem is that malpractice risks, divorce, or market downturns can liquidate years of progress. The second biggest mistake is neglecting tax planning—many physicians pay 30–40% of their income in taxes without structuring trusts, LLCs, or qualified retirement accounts to mitigate liability.
Q: Can locum tenens or part-time work boost a physician’s net worth?
It can, but only if managed strategically. Locum tenens (temporary assignments) allows physicians to test new specialties, earn high fees ($100–$300/hour), and avoid practice overhead. However, taxes and travel costs can erode gains. The most successful locum physicians reinvest earnings into passive income (real estate, digital assets) rather than lifestyle spending. Part-time work—common in academic medicine or consulting—can preserve net worth by reducing burnout while maintaining cash flow.
Q: How do physician wealth strategies differ by career stage?
- Early-career (under 40): Focus on aggressive debt payoff (refinancing loans, PSLF programs) and building emergency funds. Avoid lifestyle inflation.
- Mid-career (40–55): Shift to asset accumulation (real estate, private equity) and practice optimization (ownership, niche specialization). Maximize tax-advantaged accounts (HSAs, 401(k)s).
- Late-career (55+): Prioritize tax-efficient withdrawals, long-term care planning, and legacy structuring (trusts, gifting strategies). Many physicians reduce clinical hours to preserve net worth.
