
The Short Answers
- Median net worth for middle-class households (ages 45–54): ~$165,000 (Fed data), but varies sharply by race, location, and homeownership.
- Homeownership is the single biggest wealth driver—renters’ net worth averages $5,000–$10,000 less than owners.
- Student debt depresses net worth—graduates under 35 see their wealth 20–30% lower than peers without degrees.
- Regional splits: Middle-class families in the Midwest outpace coastal peers by $30,000–$50,000 in net worth.
- Generational gap: Gen Xers (now 45–59) hold $200K+ median net worth, while Millennials (30–44) lag at $120K–$140K.
- Inflation’s hidden cost: The Fed’s net worth figures don’t adjust for rising living expenses—$100K in 2010 buys half the home it did today.
Deep Dive: The Full Picture
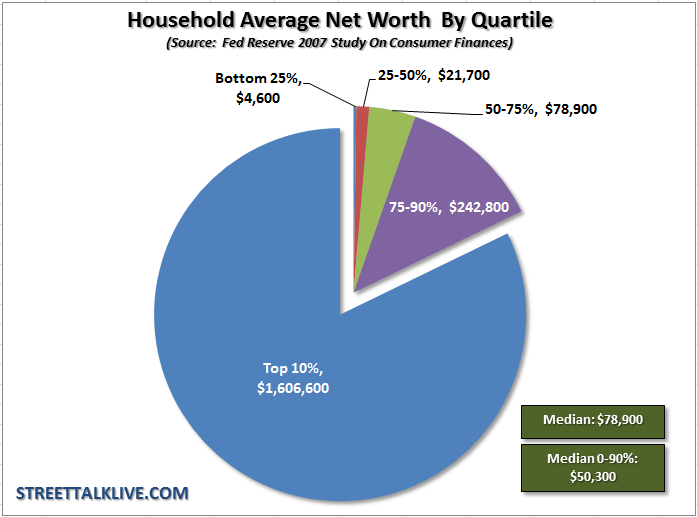
The average net worth of middle-class Americans is a statistical ghost—it exists only as an average, masking the reality that most families fall into one of three buckets: asset-rich but cash-poor, liquid but debt-laden, or stuck in the middle with no safety net. The Federal Reserve’s Survey of Consumer Finances (SCF) paints the broadest picture, but even its data is a Rorschach test. A household in Detroit with a paid-off home and a 401(k) might hit the median, while a couple in San Francisco with a $1.2M house and $200K in student loans for their kids could appear "middle-class" by income but face liquidity crises.
The confusion stems from how middle-class net worth is defined. Income brackets (e.g., $50K–$150K annually) don’t correlate neatly with wealth. A teacher in Ohio with a pension and a modest home could have $300K net worth, while a Silicon Valley engineer earning $250K might owe $150K on a mortgage and student loans, leaving them with $50K in liquid assets. The key variables aren’t just salary or savings—they’re homeownership status, debt leverage, and inherited wealth.
#### The Context You Need
Historically, the middle-class net worth trajectory followed a predictable arc: marry in your mid-20s, buy a home by 30, max out a 401(k) by 40, and retire with a nest egg. But that script has fractured. The Great Recession wiped out $16 trillion in household wealth—a loss that took until 2017 to recover. Then came the pandemic: stimulus checks and remote work inflated savings rates to 14% in 2021, but rising costs and layoffs in tech and media have since halved that buffer. Today, 40% of middle-class Americans report they couldn’t cover a $1,000 emergency without borrowing, per a 2023 Pew survey. The data also ignores regional economic engines. In North Dakota, middle-class net worth is $250K+ thanks to energy jobs and low taxes. In Louisiana, hurricane risks and stagnant wages keep it below $100K. Even within states, disparities are stark: a middle-class family in Raleigh, NC (tech hub) may have twice the wealth of one in Birmingham, AL (manufacturing decline). The Fed’s national averages smooth these edges into irrelevance. ####The Mechanics
Three factors dominate the average net worth of middle-class Americans: 1. Homeownership as a wealth multiplier. A homeowner’s net worth is 36x higher than a renter’s, per Urban Institute research. The equity in a $300K home (after mortgage) can dwarf a renter’s $5K in savings + $20K in retirement accounts. 2. Student debt as a wealth drain. The average class of 2023 graduate leaves school with $37K in loans, which suppresses homebuying and retirement savings. A 2022 Brookings study found Millennials with student debt have 20% lower net worth than peers without degrees. 3. Retirement account growth. The median 401(k) balance for middle-class households is $100K–$120K, but only 50% of workers contribute enough to meet basic retirement needs. Social Security replaces just 40% of pre-retirement income for average earners, leaving gaps that stretch savings thin. The math gets uglier when you factor in healthcare costs. A middle-class family spends $28,000 annually on healthcare by retirement—$10K more than in 2010—eating into net worth faster than inflation. The result? A middle class that’s wealthier on paper but poorer in resilience.Details That Change the Picture
The average net worth of middle-class Americans is a race-based story. White households hold $188K median net worth; Black households, $36K; Hispanic households, $72K. That gap isn’t just about income—it’s about inherited wealth, redlining history, and asset appreciation. A Black family’s home may appreciate at half the rate of a white neighbor’s due to neighborhood investment disparities. Even when incomes are identical, Black middle-class families save $500 less per month on average, per a 2023 Federal Reserve study.
Age matters just as much. Gen Xers (45–59)—now the peak earning years—hold $200K+ median net worth, thanks to the 1990s tech boom and 2000s housing market. Millennials (30–44), saddled with student debt and stagnant wages, sit at $120K–$140K. The Silent Generation (70+) leads with $250K+, but their wealth is concentrated in homes and pensions—assets less liquid for younger generations.
"The middle class isn’t disappearing—it’s just getting squeezed between the haves and the have-nots. And the have-nots are winning the wealth race because the system is rigged to favor those who already have assets." — Rachel Schneider, economist at the Urban Institute
| Factor | Impact on Net Worth |
|---|---|
| Homeownership | +$150K–$300K vs. renting |
| Student debt | −$20K–$50K (suppressed savings) |
| Retirement savings | +$100K (if maxed out) or −$50K (if underfunded) |
| Healthcare costs | −$50K–$100K by retirement |

Conclusion
The average net worth of middle-class Americans tells two stories: one of statistical recovery (asset prices are up!) and one of economic precarity (but can they sell those assets without crisis?). The data shows progress—median net worth has doubled since 2010—but ignores the liquidity trap many families face. A $200K home doesn’t help if you’re underwater on the mortgage or can’t afford repairs. The middle class today is wealthier in homes and stocks but poorer in emergency cash and retirement security.
The real question isn’t whether the middle class is shrinking—it’s whether it’s functioning. A family with $150K net worth but $50K in credit card debt and a $400K mortgage isn’t middle-class in any meaningful sense. Policy shifts (student debt relief, affordable housing) could reshape this picture—but without them, the average net worth of middle-class Americans remains a fragile illusion.
Comprehensive FAQs
#### Q: How does the average net worth of middle-class Americans compare to other countries?
The U.S. middle class leads in absolute net worth but lags in equity. The median American middle-class household has $165K, while Germans sit at $120K and Canadians at $150K. However, wealth inequality is far worse in the U.S.—the top 10% hold 67% of national wealth, vs. 35% in Germany.
####Q: Does homeownership still matter for middle-class wealth in 2024?
Absolutely. Homeowners’ net worth is 40x higher than renters’ on average. Even in high-cost cities, a $500K home with $200K equity can outweigh a renter’s $10K in savings + $30K in retirement. The catch? Mortgage rates above 7% make buying harder, and home values are stagnant in 60% of U.S. markets.
####Q: How much does student debt reduce middle-class net worth?
$20K–$50K on average. A graduate with $40K in loans may save $300/month less than a peer without debt, cutting their net worth by $100K+ over a lifetime. The effect is worse for Black and Hispanic borrowers, who default at 2x the rate of white borrowers.
####Q: Are Millennials catching up to Gen X in net worth?
No—not yet. Gen Xers (45–59) have $200K+ median net worth; Millennials (30–44) are at $120K–$140K. The gap widens because Millennials entered the workforce during the 2008 crash and faced stagnant wages + student debt. By 50, they’ll need $500K+ in net worth to retire comfortably—$100K more than Gen X did at the same age.
####Q: How does healthcare cost affect middle-class net worth?
$50K–$100K by retirement. A middle-class family spends $28K/year on healthcare by age 65—$10K more than in 2010. High-deductible plans and rising prescription costs force families to dip into retirement savings or take on debt, reducing net worth by 15–20%.
####Q: What’s the biggest misconception about middle-class net worth?
That it’s uniform. The median ($165K) hides the reality that 40% of middle-class families have less than $50K in net worth. A teacher in Chicago and a sales rep in Dallas may both earn $70K, but their net worth could differ by $150K due to housing costs, debt, and local tax policies.
####Q: Can policy changes fix the middle-class net worth gap?
Partially. Student debt relief could add $10K–$30K to Millennials’ net worth. Affordable housing policies (like down payment assistance) could boost homeownership rates by 10–15%, lifting net worth for millions. But without wage growth and healthcare reform, the gaps will persist. The top 1%’s net worth grew 25% since 2020—while the middle class saw just 5% growth.
####Q: What’s the outlook for middle-class net worth in 5 years?
Stagnant to declining for many. If interest rates stay high, home values could drop 5–10% in key markets, slashing equity. Stock market volatility and pension cuts (like in California) will erode retirement savings. The only bright spots: AI-driven wage growth in tech hubs and policy shifts on student debt. But without structural changes, the average net worth of middle-class Americans may flatline or shrink for the first time in decades.
