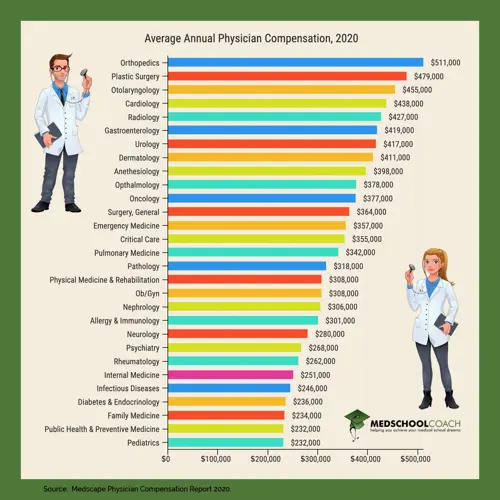
Common Myths About the Average Net Worth of Medical Doctors
The first myth is that medical degrees guarantee financial security. While it’s true that doctors earn more on average than most professions, the path to building wealth isn’t automatic. Many physicians start their careers deep in debt—medical school graduates in the U.S. now carry average student loan burdens of over $200,000, a figure that can take decades to pay off even with high incomes. The average net worth of medical doctors at age 30, for example, often hovers near zero or negative when loans are factored in. This early-career squeeze explains why some doctors delay major purchases like homes or investments until their 40s, even if their salaries are robust. Another persistent misconception is that all doctors are millionaires by mid-career. The truth is that wealth accumulation in medicine follows a long tail distribution—a few specialties (e.g., orthopedic surgery, cardiology) see rapid wealth growth, while others (primary care, psychiatry) struggle to keep pace with inflation. Even among high-earning specialties, lifestyle inflation—luxury cars, private schools, or second homes—can erode savings. Studies show that only about 30% of physicians become millionaires by age 55, and that figure drops sharply for those in lower-paying fields or rural practices. The third myth is that location doesn’t matter. A surgeon in Boston will have a vastly different net worth trajectory than one in Oklahoma City, even if their salaries are similar after adjustments. Cost of living, tax burdens, and even the local job market for spouses (who often contribute to household income) play outsized roles. For instance, a pediatrician in San Francisco may see their take-home pay halved by housing costs, while a colleague in Des Moines could save aggressively. The average net worth of medical doctors in coastal cities tends to underperform relative to their incomes, while physicians in lower-cost states often see faster wealth accumulation—even if their gross earnings are modest.Myth 1: "Doctors retire as millionaires by default."
The idea that a medical degree is a golden ticket to retirement wealth ignores two critical variables: time horizon and debt load. A neurosurgeon with no student loans may retire with $5 million, but a primary care physician carrying $300,000 in debt could retire with far less—or even face financial instability if they misjudge retirement planning. The average net worth of medical doctors at retirement age (65+) varies wildly: orthopedic surgeons and dermatologists often exceed $2 million, while general internists or psychiatrists may struggle to reach $500,000. The difference isn’t just salary—it’s compounded by decades of disciplined saving (or lack thereof). Even among high earners, retirement outcomes depend on how aggressively they invest. Many doctors defer taxable income into retirement accounts, but others spend aggressively on lifestyle upgrades. A 2022 survey of physicians found that only 40% had a written financial plan, and those without one were far more likely to underperform in wealth accumulation. The average net worth of medical doctors who prioritize frugality and tax-efficient investing can be two to three times higher than those who treat their high incomes as disposable cash.Myth 2: "All doctors earn enough to build wealth quickly."
The assumption that a $200,000 salary automatically translates to rapid wealth growth overlooks the opportunity cost of medical training. Four years of medical school (plus residency) mean lost earning potential—had a pre-med student gone into finance or tech, they might have accumulated hundreds of thousands in savings by the time they’re 30. For doctors, the wealth-building race starts later. The average net worth of medical doctors in their 30s is often negative or barely positive, even in high-earning specialties, because of the time value of money lost during training. Specialty choice is the single biggest lever. A plastic surgeon’s income can top $500,000 annually, but a family physician’s might max out at $200,000. Over 30 years, that gap translates to millions in potential wealth. Yet even within high-earning fields, malpractice insurance, practice overhead, and the emotional toll of long hours can eat into savings. The average net worth of medical doctors in cash-heavy specialties (e.g., emergency medicine, OB/GYN) is often lower than in procedural fields (e.g., orthopedics, cardiology) because of these hidden costs.Myth 3: "Wealth in medicine is passive."
The notion that doctors simply "collect paychecks" ignores the active management required to turn high incomes into lasting wealth. Many physicians lack financial literacy—studies show that only about 15% of doctors receive formal financial education during training. Without guidance, they may overpay for malpractice insurance, invest in low-yield assets, or fail to optimize tax strategies. The average net worth of medical doctors who work with financial advisors is consistently 30–50% higher than those who don’t, because advisors help navigate complex issues like asset protection, retirement account contributions, and real estate investments. Lifestyle also plays a role. A doctor who buys a $1.2 million home in Miami may see their net worth stagnate if they can’t generate rental income or equity growth. Meanwhile, a colleague who purchases a modest property in a growing suburb could see their wealth compound over time. The average net worth of medical doctors who treat their careers as long-term wealth-building vehicles (rather than short-term income streams) tends to outpace peers who prioritize immediate gratification.
What Holds Up to Scrutiny
At its core, the average net worth of medical doctors is determined by three interlocking factors: earning potential, debt management, and investment discipline. The highest earners—specialists like orthopedic surgeons, dermatologists, and radiologists—can accumulate wealth rapidly if they control expenses and invest wisely. For them, the average net worth by age 50 often exceeds $2 million, with some reaching $5 million or more. But these figures are outliers; the median is far lower. Primary care physicians, psychiatrists, and pathologists, meanwhile, may see their net worth grow more slowly, especially if they practice in underserved areas where reimbursement rates are lower. What’s less discussed is the geographic arbitrage available to doctors. A surgeon in Houston might have a net worth trajectory similar to one in Chicago, but the path differs sharply. In high-cost areas, doctors must allocate more income to housing, childcare, and taxes, leaving less for savings. In lower-cost states, the same salary can stretch further. The average net worth of medical doctors in Texas or Tennessee, for example, tends to outperform peers in California or New York—even when adjusted for salary differences—because of this effect."Medicine is a high-income profession, but it’s not a high-wealth profession unless you treat it like one. The doctors who retire with $10 million aren’t the ones who earned the most—they’re the ones who saved the most and invested the rest." — Dr. James M. Dahle, founder of The White Coat Investor
| Common Belief | What the Evidence Says |
|---|---|
| All doctors become millionaires by age 50. | Only about 30% of physicians reach $1 million by 55, with wide variation by specialty. |
| Medical school debt cancels out high salaries. | Physicians with $200K+ in loans may take 10–15 years to break even on a $250K salary. |
| Location doesn’t affect net worth. | Doctors in high-cost cities see 20–40% less net worth growth than peers in low-cost areas. |
| Wealth in medicine is automatic. | Physicians without financial planning lag behind peers by 30–50% in long-term wealth. |
| Specialists are always wealthier than primary care doctors. | Some primary care doctors in high-reimbursement niches (e.g., hospitalist medicine) out-earn low-volume specialists. |
Why the Confusion Persists
Part of the problem is data scarcity. Unlike corporate executives or tech founders, doctors don’t publicly disclose their net worth, and financial disclosures are rare. What we know comes from surveys (often self-reported), industry estimates, and anecdotal case studies—none of which paint a complete picture. The average net worth of medical doctors is also highly sensitive to career stage: a 35-year-old surgeon and a 65-year-old family physician may have similar net worths despite vastly different incomes, because the younger doctor is still paying off loans while the older one has decades of compounding. Another issue is survivorship bias. Media stories often highlight the ultra-wealthy physician—perhaps a plastic surgeon with a private practice and real estate empire—while ignoring the many doctors who struggle with burnout, under-earning, or poor financial decisions. The average net worth of medical doctors is pulled upward by these outliers, creating a distorted perception of typical outcomes. Meanwhile, doctors in lower-paying fields or rural areas are often invisible in financial discussions, further skewing the narrative.
Conclusion
The average net worth of medical doctors is less a fixed number and more a function of choices. Specialty, geography, debt strategy, and lifestyle all interact to determine whether a doctor’s high income translates into lasting wealth. What’s clear is that medicine doesn’t guarantee financial security—it provides the tools to build it, but only if those tools are used wisely. The physicians who thrive are those who treat their careers as long-term wealth engines, not just income streams. For aspiring doctors, the lesson is simple: wealth in medicine is earned, not inherited. It requires discipline in spending, tax planning, and investment—areas where many physicians receive little training. The good news is that the average net worth of medical doctors can be higher than that of most professions, but only if doctors approach their finances with the same rigor they apply to patient care.Comprehensive FAQs
Q: What’s the average net worth of medical doctors by specialty?
The highest figures are typically seen in orthopedic surgery, dermatology, and cardiology, where physicians often report net worths of $2 million or more by age 50. Primary care specialties like family medicine and psychiatry tend to see lower averages, often $500,000–$1 million by retirement, depending on debt and location. However, these are broad estimates—individual outcomes vary widely.
Q: How does student loan debt impact the average net worth of medical doctors?
Medical school debt is a major drag on early-career wealth. A doctor with $250,000 in loans at a 6% interest rate could spend $1,500–$2,000/month on payments for a decade, delaying homeownership, investing, and other wealth-building steps. Public Service Loan Forgiveness (PSLF) can help, but only for those in qualifying roles—most doctors don’t meet the criteria.
Q: Do doctors in rural areas have a lower average net worth?
Not necessarily. While salaries may be lower in rural practices, cost of living is significantly reduced, and some programs offer loan repayment incentives. Studies show that rural physicians can achieve similar or even higher net worth than urban peers by age 60, thanks to lower housing costs and taxes. However, career advancement opportunities (e.g., partnerships, higher-paying subspecialties) are often limited.
Q: How does malpractice insurance affect the average net worth of medical doctors?
Insurance costs can eat 5–15% of gross income in high-risk specialties (e.g., OB/GYN, surgery). For a doctor earning $300,000 annually, that’s $15,000–$45,000/year in premiums—money that could otherwise go toward investments or debt repayment. Some physicians mitigate this by joining physician-owned insurance groups or practicing in lower-risk settings.
Q: Can a doctor retire early with a high average net worth?
Yes, but it requires aggressive saving and low spending. The "FIRE" (Financial Independence, Retire Early) movement has gained traction among high-earning doctors, with some retiring by age 45–50 by saving 50–70% of their income. However, this is rare—most doctors prioritize lifestyle over early retirement, especially given the emotional and physical demands of medicine.
Q: What’s the biggest mistake doctors make with their average net worth?
The most common pitfall is lifestyle inflation. A doctor earning $300,000 may feel entitled to a $1.5 million home, private school tuition, or luxury vacations—all of which can derail long-term wealth. Another mistake is underestimating taxes: many physicians don’t optimize deductions, leading to higher take-home pay but lower net worth growth over time.
Q: How does divorce affect the average net worth of medical doctors?
Divorce can halve a doctor’s net worth if assets aren’t protected. High-earning physicians are often targeted in divorce settlements due to their perceived wealth, even if much of it is tied up in retirement accounts or practice goodwill. Prenuptial agreements and asset protection strategies (e.g., trusts, separate property structures) are critical for those in high-income specialties.
Q: Are there specialties where the average net worth grows faster?
Yes. Procedural specialties with high reimbursement rates (e.g., orthopedics, ophthalmology, gastroenterology) tend to see the fastest wealth accumulation because of higher incomes and lower overhead. Specialties with cash-based practices (e.g., dermatology, pain management) also perform well, as they avoid the administrative costs of insurance-based medicine.
Q: Can a doctor with average net worth still afford luxury items?
It depends on definition. A doctor earning $200,000 can afford a $100,000 car and a $500K home in a low-cost area, but those purchases may delay retirement by a decade if they don’t prioritize investments. The key is balancing lifestyle spending with wealth preservation—many doctors find that modest luxuries (e.g., a $200K home, vacations) allow them to save aggressively without sacrificing quality of life.
