
Common Myths About the Average Net Worth of Centurion Card Holders
The Centurion Card’s aura of mystery has birthed a cottage industry of half-truths. One persistent myth is that all Centurion holders are billionaires. This oversimplification ignores the card’s tiered approval criteria. While billionaires certainly qualify—and often use the card for high-stakes transactions—the majority of holders fall into the $5 million to $50 million range. The card’s minimum spend requirement ($250,000 annually) ensures applicants can demonstrate liquidity, but it doesn’t mandate a nine-figure net worth. A successful entrepreneur with a $15 million portfolio might meet the threshold just as easily as a corporate executive with a $30 million stake. The confusion arises from associating the card’s prestige with a single wealth bracket. In truth, Centurion’s approval is less about absolute net worth and more about financial consistency and spending behavior. Another misconception is that the Centurion Card guarantees wealth accumulation. Some assume the card’s perks—private jet access, luxury travel, concierge services—directly translate to financial growth. While these benefits can enhance a high-net-worth individual’s lifestyle, they don’t create wealth. A Centurion holder’s net worth is determined by their underlying assets: real estate, investments, business equity, or inherited wealth. The card itself is a tool, not a wealth generator. Its value lies in efficiency—streamlining travel, securing hard-to-find experiences, or expediting transactions—but it doesn’t inflate a balance sheet. This distinction is critical. The average net worth of Centurion Card holders doesn’t rise because of the card; it rises because of the pre-existing financial acumen required to obtain it. A third myth suggests that Centurion holders are all self-made millionaires. While the card does attract entrepreneurs and high-achieving professionals, a significant portion of holders inherit wealth or benefit from family offices. The approval process doesn’t distinguish between earned and inherited capital—only that the applicant can demonstrate sustained financial health. A trust-fund beneficiary with a $20 million portfolio might qualify alongside a self-made tech CEO with a $40 million stake. The card’s inclusivity of both paths to wealth complicates any attempt to pinpoint a single average net worth of Centurion Card holders. What unites them is not their origin story but their ability to leverage financial resources in ways that align with Amex’s criteria.Myth 1: Only Billionaires Can Get the Centurion Card
The idea that Centurion is exclusively for billionaires is a holdover from early adopter stories that emphasized high-profile names. While it’s true that some of the most visible Centurion holders are billionaires, the card’s approval criteria are broader. Amex’s Centurion team evaluates applicants based on spending history, credit utilization, and liquidity—not just total assets. A doctor with a $12 million practice, a private equity professional with a $15 million portfolio, or a corporate executive with a $20 million stake could all qualify. The key metric isn’t net worth alone but annual spending power. The card’s minimum requirement of $250,000 in annual spend ensures applicants can cover premium travel, entertainment, and other high-end expenses. This threshold filters for financial stability, not just wealth accumulation. The myth persists because the card’s early marketing emphasized its association with the ultra-wealthy. High-profile cases—such as a tech mogul or a hedge fund manager—dominate public discourse, skewing perceptions. However, Amex’s internal data suggests that the median Centurion holder’s net worth is closer to $10 million than $1 billion. The card’s value proposition isn’t about exclusivity based on absolute wealth but about access to a network and services that cater to high spenders. For many holders, the Centurion Card is a practical tool for managing global expenditures, not a trophy for billionaires. The reality is that while billionaires may dominate the card’s most visible use cases, they represent only a fraction of the total holder base.Myth 2: The Centurion Card Itself Makes You Richer
The notion that the Centurion Card directly increases net worth is a common misconception. The card’s perks—private jet access, luxury hotel upgrades, concierge services—are designed to enhance lifestyle and efficiency, not to generate returns. A Centurion holder’s wealth is determined by their underlying investments, business holdings, or real estate portfolios, not by the card’s features. For example, a private jet charter booked through the card’s concierge service might cost $50,000 for a weekend trip, but that expense doesn’t add to the holder’s net worth. Instead, it reflects discretionary spending from an already substantial portfolio. The confusion arises from the card’s association with high-net-worth individuals who use it to optimize their financial activities. For instance, a Centurion holder might use the card to secure better terms on business-class travel or to access exclusive investment opportunities through Amex’s private banking division. However, these advantages are byproducts of the card’s status, not its primary function. The average net worth of Centurion Card holders doesn’t rise because of the card; it rises because those individuals already possess the financial acumen to maximize its benefits. The card is a multiplier for existing wealth, not a wealth-creation engine. For most holders, its value lies in time savings and convenience, not in appreciating assets.Myth 3: Centurion Holders Are All Self-Made Millionaires
The assumption that Centurion holders are predominantly self-made overlooks the role of inherited wealth and family offices in the approval process. While the card does attract entrepreneurs, executives, and high-achieving professionals, a significant portion of holders come from multi-generational wealth. A trust-fund heir with a $20 million portfolio might meet the card’s spending requirements just as easily as a self-made tech CEO with a $40 million stake. The approval process doesn’t distinguish between earned and inherited capital—only that the applicant can demonstrate consistent financial health and high spending. This myth is reinforced by the card’s marketing, which often highlights self-made success stories in business and finance. However, Amex’s internal data suggests that inherited wealth plays a role for a portion of Centurion holders. For example, a family office managing a $50 million endowment might use the card to facilitate global transactions, even if the primary earner is a younger generation. The card’s inclusivity of both self-made and inherited wealth complicates any attempt to define a single average net worth of Centurion Card holders. What matters is not the origin of the wealth but the ability to deploy it in ways that align with Amex’s criteria. The reality is that Centurion’s holder base is a mix of earned and inherited affluence, making broad generalizations about their financial backgrounds inaccurate.
What Holds Up to Scrutiny
At its core, the average net worth of Centurion Card holders is less about a fixed number and more about financial behavior. Amex’s approval process prioritizes spending patterns, credit history, and liquidity over absolute net worth. This means that while some holders may have portfolios in the $5 million to $20 million range, others could be worth $100 million or more. The card’s value isn’t in its spending limit (which is effectively unlimited) but in its access to a curated network. Holders gain entry to private jet programs, luxury travel perks, and concierge services that streamline high-end transactions. These benefits are particularly valuable for those who travel frequently, entertain clients, or manage global assets. What’s verifiable is that Centurion holders consistently demonstrate high levels of financial activity. The card’s minimum spend requirement of $250,000 annually ensures that applicants can cover premium expenses without strain. This threshold acts as a de facto wealth filter, as most individuals below the $5 million net worth mark wouldn’t meet it. However, the upper limit is far less defined. A hedge fund manager with a $50 million portfolio might use the card for high-stakes transactions, while a corporate executive with a $15 million stake might rely on it for lifestyle perks. The average net worth of Centurion Card holders thus exists as a range rather than a single figure, reflecting the diversity of financial profiles that qualify for the card. The card’s true utility lies in its operational efficiency. For a business owner, it might mean faster approval for large purchases or priority access to high-end vendors. For a private investor, it could translate to expedited travel for meetings or discreet concierge assistance in securing hard-to-find assets. These advantages don’t directly increase net worth but reduce friction in managing it. The average net worth of Centurion Card holders isn’t a static metric—it’s a reflection of how those individuals deploy their financial resources, with the card serving as a catalyst for efficiency."The Centurion Card isn’t about the money you have—it’s about the money you move. The right holders use it to operate at a level where most people can’t even see the levers." — Former Amex Centurion approval officer (anonymous)
| Common Belief | What the Evidence Says |
|---|---|
| All Centurion holders are billionaires. | The majority fall between $5 million and $50 million, with outliers skewing perceptions. |
| The card itself makes you richer. | It enhances lifestyle and efficiency but doesn’t generate wealth. |
| Centurion holders are all self-made. | Inherited wealth plays a role for a portion of holders. |
| The average net worth is a fixed number. | It’s a range due to diverse financial profiles. |
| Approval is based on net worth alone. | Spending behavior and liquidity are equally critical. |
Why the Confusion Persists
The average net worth of Centurion Card holders remains elusive because Amex operates in controlled secrecy. Unlike public companies that disclose financial metrics, Amex doesn’t release data on its most exclusive cardholders. This lack of transparency allows myths to flourish, as industry insiders and financial commentators fill the void with anecdotal evidence and speculation. The card’s association with high-profile names—tech CEOs, hedge fund managers, and celebrities—further distorts perceptions, as these individuals represent the visible tip of the iceberg. The reality is that the majority of Centurion holders operate in private spheres, where their wealth isn’t subject to public scrutiny. Another factor is the halo effect of the card’s prestige. Because Centurion is marketed as the pinnacle of credit cards, it’s easy to assume that all holders occupy the same financial tier. In truth, the card’s approval process is flexible enough to accommodate a range of wealth levels, as long as applicants meet the spending and credit criteria. This variability means that discussions about the average net worth of Centurion Card holders often overgeneralize. What’s clear is that the card serves as a gateway to a network, not a uniform wealth bracket. The confusion persists because the perception of exclusivity outweighs the reality of diversity among holders.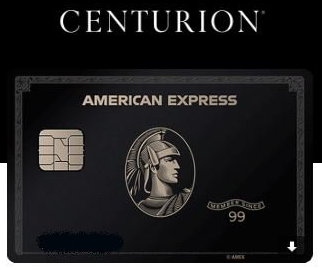
Conclusion
The average net worth of Centurion Card holders is less about a single number and more about financial behavior and access. While some holders may be billionaires, the majority likely fall into the $5 million to $50 million range, with outliers stretching far beyond. The card’s value lies not in its ability to generate wealth but in its role as a tool for high-net-worth individuals to operate efficiently. Whether it’s securing private jet charters, expediting international transactions, or gaining entry to exclusive networks, the Centurion Card is a multiplier for existing affluence, not a creator of it. What’s certain is that the card’s approval process is rigorous and selective, designed to filter for those who can demonstrate sustained financial health and high spending. The average net worth of Centurion Card holders isn’t a fixed metric but a reflection of the diversity of profiles that meet Amex’s criteria. For those who qualify, the card isn’t just plastic—it’s a key to a world of operational advantages that most people never encounter. The myths surrounding its holders persist because the card itself is shrouded in mystery, but the reality is far more nuanced than the headlines suggest.Comprehensive FAQs
Q: What is the exact average net worth of Centurion Card holders?
A: There is no official average because Amex doesn’t disclose holder demographics. Industry estimates suggest a range of $5 million to $50 million, with outliers at both ends. The card’s approval is based on spending behavior, not net worth alone.
Q: Can someone with a $2 million net worth get approved for the Centurion Card?
A: Unlikely. The card requires $250,000 in annual spend, which most $2 million net worth individuals wouldn’t meet. Approval hinges on liquidity and spending patterns, not just total assets.
Q: Do Centurion Card holders pay interest?
A: No. The Centurion Card has no preset spending limit or interest charges. It’s a charge card, meaning the full balance is due monthly. Late payments result in account closure.
Q: How many people have the Centurion Card?
A: Amex has never disclosed exact numbers, but estimates place the holder count in the low tens of thousands globally. The card is invitation-only, with no public application process.
Q: Is the Centurion Card worth it for high-net-worth individuals?
A: For those who qualify, yes—but not for the reasons most assume. The card’s value lies in access to private jets, concierge services, and global networks, not in rewards points. It’s a tool for efficiency, not a wealth-building product.
Q: Can a Centurion Card holder’s net worth decrease and still keep the card?
A: Possibly, but not indefinitely. Amex monitors spending and credit health. A significant drop in annual spend could lead to account review or cancellation, especially if the holder no longer meets the $250,000 minimum.
Q: Are there any famous Centurion Card holders?
A: Some high-profile names have been reported to hold the card, including tech executives, athletes, and entertainers. However, Amex doesn’t publicly confirm holder identities to protect privacy.
Q: How does the Centurion Card compare to other elite cards like the Amex Platinum?
A: The Platinum Card is mass-market elite, with perks like lounge access and hotel credits. The Centurion Card offers private jet access, global concierge, and no spending limits—but approval is far more restrictive and based on proven high spending.
Q: Can you apply for the Centurion Card directly?
A: No. The card is invitation-only, with no public application process. Approval comes from Amex’s Centurion team after evaluating spending history, creditworthiness, and lifestyle expenditures.
Q: Does having the Centurion Card improve your credit score?
A: Not directly. The card doesn’t report to credit bureaus like traditional cards. However, responsible use (paying balances in full) can indirectly support credit health by demonstrating financial discipline.
