The first time the phrase
"average age to pay off mortgage" entered mainstream financial conversations was in the late 1990s, when economists noticed a subtle but steady creep upward. Back then, most homeowners in developed economies cleared their loans by their early 50s—often before retirement. The numbers were tidy, almost predictable. But by the 2010s, something had shifted. A 55-year-old paying off a mortgage wasn’t just unusual; it was becoming the new normal. The reasons were buried in decades of economic policy, demographic change, and a housing market that no longer played by the old rules.
Today, the
"average age to pay off mortgage" isn’t just a statistical footnote—it’s a symptom of deeper financial stress. In some cities, borrowers now face the prospect of retiring with a mortgage still hanging over them, thanks to longer loan terms, higher property prices, and stagnant wages. The shift reflects a generation squeezed between student debt, rising living costs, and homes that feel increasingly out of reach. Yet for others, the delay isn’t a crisis but a calculated strategy—stretching payments to afford bigger properties or invest elsewhere. The line between necessity and choice has blurred, and the numbers tell a story of an economy that rewards patience but punishes those who can’t afford it.
Where It All Began
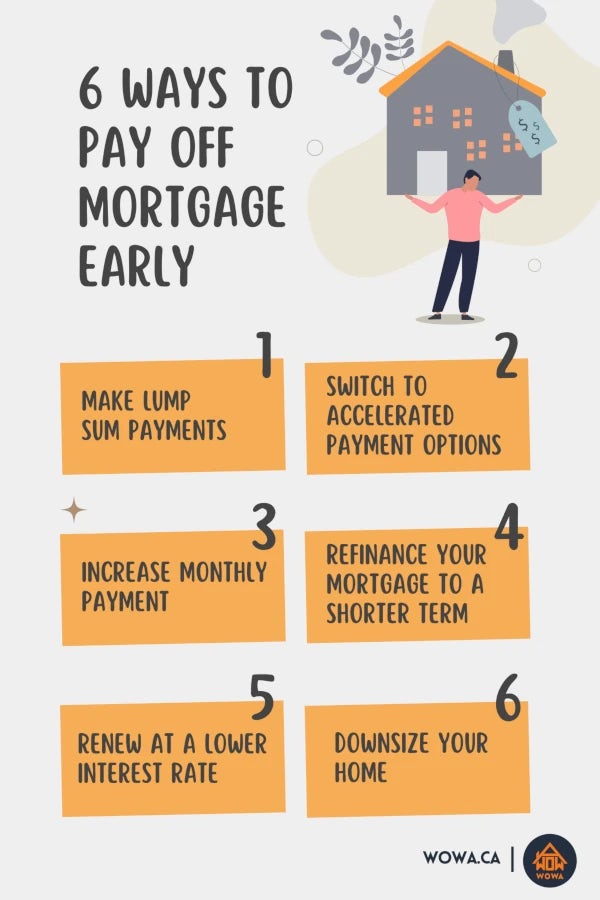
The post-World War II era set the template for what would later be mythologized as the
"golden age of homeownership." In the 1950s and 60s, fixed-rate mortgages with 20- to 25-year terms were standard. A family could buy a home, put down 10-20% upfront, and expect to own it outright by their late 40s or early 50s. The "average age to pay off mortgage" then hovered around 52, according to early Federal Reserve data. Banks trusted borrowers, and borrowers trusted the system. Interest rates were low by historical standards, and wages grew alongside home values. For the first time in modern history, homeownership felt like a reliable path to generational wealth.
But beneath the surface, cracks were forming. By the 1970s, inflation and oil crises sent interest rates soaring. The
"average age to pay off mortgage" began to stretch—first to the mid-50s, then toward 60 for some. Adjustable-rate mortgages became popular, offering lower initial payments but leaving borrowers vulnerable to rate hikes. The financialization of housing had begun. Lenders started treating mortgages less as long-term commitments and more as short-term assets to securitize and sell. The stage was set for a system where the "average age to pay off mortgage" would no longer be a matter of personal discipline but of structural economics.
The Early Signs
The 1980s brought two pivotal changes that would reshape the landscape. First, deregulation under Reagan and Thatcher loosened lending standards, allowing borrowers to take on larger loans. Second, the rise of the 30-year fixed-rate mortgage—once a rarity—became the default. These shifts didn’t just extend loan terms; they redefined what
"paying off a mortgage" even meant. Where previous generations might have aimed to clear their loan in 20 years, the new norm was 30. The psychological impact was immediate: a mortgage wasn’t just a debt to be repaid; it was a financial tool to be optimized.
Then came the 1990s housing boom, fueled by low rates and speculative buying. For a brief moment, it seemed the
"average age to pay off mortgage" might stabilize. But the boom masked a growing divide. Urban professionals in high-cost cities faced longer payoff timelines, while suburban families with steady incomes still cleared loans by their mid-50s. The gap between haves and have-nots in homeownership was widening, and the numbers reflected it. By the turn of the millennium, the "average age to pay off mortgage" in the U.S. had climbed to 56, with some studies suggesting it was higher in coastal metros.
The Turning Point
The 2008 financial crisis didn’t just crash housing markets—it
permanently altered the trajectory of mortgage payoff timelines. Banks, now wary of risk, tightened lending standards, pushing borrowers toward longer terms to qualify for loans. Meanwhile, home prices stagnated or fell in many regions, leaving equity-building at a standstill. The "average age to pay off mortgage" became a casualty of a system that prioritized risk aversion over homeownership stability.
For younger borrowers entering the market post-crisis, the math was brutal. Stagnant wages, student debt, and higher down payment requirements meant that even those who bought homes in their 30s faced the prospect of paying into their late 50s—or never at all. The crisis didn’t just delay payoffs; it
redefined what it meant to "own" a home. Many found themselves house-rich but cash-poor, unable to tap equity for retirement or emergencies.
>
"The mortgage isn’t just a loan anymore—it’s a lifestyle choice with financial consequences."
> —
Kathy Bostjancic, Chief Economist at Oxford Economics (2015)
The Build-Up, Year by Year
| Period | Key Developments |
|------------------|-----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|
| 1950s–1960s | 20–25-year fixed-rate mortgages standard. "Average age to pay off mortgage" around 52. High down payments (10–20%) and stable wages accelerated equity growth. |
| 1970s–1980s | Inflation spikes push rates to 10–18%. Adjustable-rate mortgages rise; "average age to pay off mortgage" extends to mid-50s. Deregulation allows longer loan terms (30-year mortgages become mainstream). |
| 1990s | Housing boom; "average age to pay off mortgage" stabilizes at 56 in many markets. Subprime lending emerges, but urban professionals still face longer timelines due to higher home prices. |
| 2000s | Dot-com bust and 2008 crisis force lenders to tighten terms. "Average age to pay off mortgage" climbs to late 50s as loan terms extend and equity growth stalls. Many borrowers trapped in negative equity. |
| 2010s–Present| Low rates post-crisis encourage longer loan terms (40-year mortgages emerge). "Average age to pay off mortgage" now 60+ in high-cost cities; younger buyers sidelined by student debt and high prices. |
Lessons From the Journey
- Loan terms matter more than ever. A 30-year mortgage today isn’t just 30 years—it’s a financial anchor that can stretch into retirement if rates rise or incomes stagnate.
- Location dictates destiny. In San Francisco or London, the "average age to pay off mortgage" is a decade longer than in Midwest or rural markets due to price-to-income ratios.
- Debt isn’t just mortgages. Student loans and credit card debt now delay homeownership, pushing the "average age to pay off mortgage" even higher for younger generations.
- Policy shifts have lasting effects. From deregulation in the 1980s to post-crisis lending rules, government actions—not just personal finance—shape when borrowers clear their loans.
- The "ownership society" is fading. For millennials, homeownership may no longer guarantee financial freedom. The "average age to pay off mortgage" is just one symptom of a broader affordability crisis.
Where Things Stand Today
As of 2024, the "average age to pay off mortgage" in the U.S. is estimated to be around 62, with significant regional variation. In cities like New York or Los Angeles, borrowers now face the possibility of retiring with a mortgage still active, thanks to home prices that have outpaced wage growth for decades. Meanwhile, in Sun Belt states, the "average age to pay off mortgage" remains closer to the late 50s, reflecting more affordable housing markets.
The trend isn’t uniform. Some borrowers leverage longer loan terms to buy bigger homes or invest in rental properties, turning the mortgage into a strategic tool rather than a burden. Others, particularly younger buyers, are opting for shorter terms—15-year mortgages—to avoid the trap of lifelong debt. But for many, the choice isn’t theirs to make. Stagnant wages, high down payments, and competitive markets leave little room for negotiation. The "average age to pay off mortgage" has become less about personal finance and more about economic survival.
Conclusion
The evolution of the "average age to pay off mortgage" is more than a statistical trend—it’s a mirror reflecting broader shifts in wealth, policy, and opportunity. What was once a milestone (owning a home outright) has become, for many, a financial endurance test. The numbers tell a story of an economy that rewards patience but punishes those who can’t afford it. For older generations, the message is clear: plan for a mortgage well into retirement. For younger buyers, the reality is harsher: homeownership may no longer guarantee financial freedom.
The question now isn’t just
when borrowers will pay off their mortgages, but whether the system will ever allow them to. As loan terms extend and home prices climb, the "average age to pay off mortgage" may keep rising—not because borrowers are failing, but because the deck is stacked against them.
Comprehensive FAQs
#### Q: Why has the "average age to pay off mortgage" increased so dramatically?
A: The shift stems from longer loan terms (30-year mortgages became standard in the 1980s), higher home prices outpacing wage growth, and tighter lending standards post-2008. Younger buyers also enter the market with student debt, delaying homeownership and stretching payoff timelines further.
#### Q: Does paying off a mortgage earlier always make financial sense?
A: Not necessarily. While eliminating debt faster can save on interest, opportunity cost matters. Some borrowers benefit more from investing the extra cash or using home equity for other goals. A 15-year mortgage may not suit everyone’s cash flow.
#### Q: Are there regions where the "average age to pay off mortgage" is still reasonable?
A: Yes. In lower-cost states (e.g., Midwest, South) or smaller cities, borrowers often clear mortgages by their late 50s. High-cost metros like San Francisco or London, however, push the "average age to pay off mortgage" into the 60s or beyond.
#### Q: How does student debt affect mortgage payoff timelines?
A: Student loans delay homeownership for many millennials, forcing them to rent longer or buy smaller homes. Even after purchasing, higher monthly debt obligations can extend the "average age to pay off mortgage" by 5–10 years.
#### Q: Can refinancing help reduce the "average age to pay off mortgage"?
A: Potentially. Refinancing to a shorter term (15-year) or lower rate can cut interest costs, but it requires higher monthly payments. Borrowers must weigh affordability against long-term savings. Post-2020 refinancing booms showed mixed results—some saved thousands, others faced higher rates later.
#### Q: What’s the future of mortgage payoff timelines?
A: If home prices keep rising faster than wages and interest rates stay elevated, the "average age to pay off mortgage" could climb further. Some analysts predict 40-year mortgages will become more common, blurring the line between homeownership and lifelong debt. Policy changes—like down payment assistance or rent control—could alter the trend, but structural issues remain.

