
Where It All Began
The 401k as we know it didn’t exist when the first Baby Boomers entered the workforce. Before 1978, retirement savings relied on pensions, which were slowly disappearing even then. The Tax Reform Act of that year created the 401k, but it was a niche tool—mostly used by high earners or those with access to employer matches. For the average worker, retirement planning was an afterthought. If you were lucky, your company offered a defined-benefit plan. If not, you saved in IRAs or hoped Social Security would stretch far enough. The early 1990s marked a turning point. Employer 401k participation surged as companies shifted from pensions to defined-contribution plans. By 1995, about 40% of private-sector workers had a 401k. But the rules were different then: contribution limits were lower ($10,500 in 2001, up from $7,000 in 1990), and many workers didn’t realize how much they’d need to save. The average 401k balance of a 50-year-old in 1995 was a fraction of what it is today—often under $50,000, adjusted for inflation. Back then, a $1 million nest egg was a pipe dream for most. Today, it’s still out of reach for many, but the conversation has shifted from "Can I retire?" to "Will I have enough?"The Early Signs
The first red flags appeared in the late 1990s. The dot-com crash exposed how volatile stock-based 401k balances could be. Workers who had aggressively invested in tech stocks saw their accounts plummet overnight. Meanwhile, those who had stayed in conservative funds missed the rebound. The lesson? Diversification mattered more than chasing returns. Then came 2008. The Great Recession wiped out trillions in retirement savings, and for those in their 40s and 50s, the damage was permanent. Many never recovered their pre-crash balances, and some were forced to delay retirement entirely. The aftermath of 2008 also revealed another truth: the average 401k balance of a 50-year-old wasn’t just about market performance—it was about behavior. Studies from the Employee Benefit Research Institute (EBRI) showed that workers who contributed consistently, even small amounts, ended up with significantly higher balances by mid-career. Those who skipped contributions during downturns or took loans from their 401ks never fully caught up. The data suggested that inertia was the biggest enemy of retirement security.The Turning Point
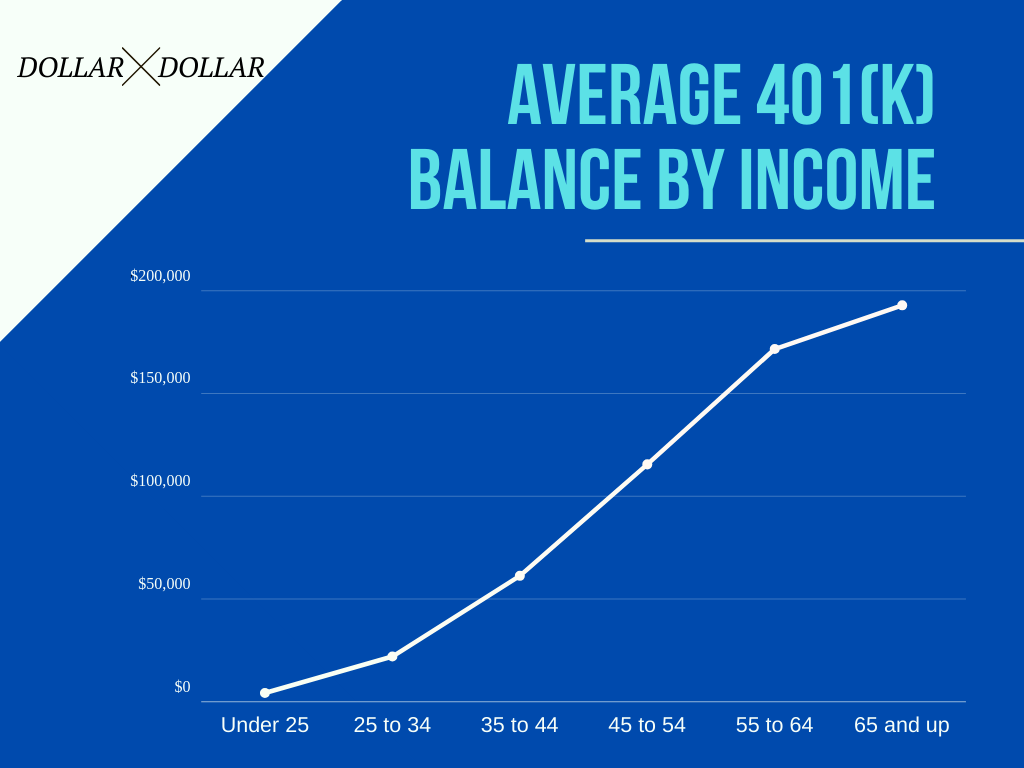
The Affordable Care Act of 2010 didn’t just expand healthcare—it included provisions that nudged more workers into 401ks. Automatic enrollment became more common, and default contribution rates crept upward. By 2015, over half of large employers offered automatic enrollment, meaning workers were signed up for 401ks unless they opted out. This small shift had a massive impact: participation rates climbed, and the median 401k balance for 50-year-olds began to rise more steadily. But the real inflection point came in 2015, when the IRS raised contribution limits to $18,000 for employees (up from $17,500). For those earning enough, it meant the ability to save nearly $50,000 annually in a 401k plus IRA—if they were disciplined. The turning point wasn’t just legislative—it was cultural. Financial literacy programs, robo-advisors, and apps like Betterment made it easier to manage 401k allocations. Suddenly, a 50-year-old with a modest salary could run projections and see how small changes—like increasing contributions by 1%—could add tens of thousands by retirement. The average 401k balance of a 50-year-old in 2020 reflected this shift: EBRI reported that the median balance for workers aged 50-59 was $165,000, up from $120,000 in 2010. But the numbers also hid a stark divide. The top 10% of 50-year-olds had balances over $500,000, while the bottom 10% had less than $10,000."You don’t get to 50 and suddenly realize you need to save. It’s the daily choices—the times you say no to lifestyle inflation, the years you contribute even when you’re not getting raises—that add up. The market can crash, but your habits determine whether you recover." — Jane Bryant Quinn, personal finance columnist and author of How to Make Your Money Last
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1990–2000 | 401ks become the default retirement plan for private-sector workers. Contribution limits rise to $10,500. The dot-com bubble inflates some balances, but the crash in 2000–2002 leaves many underwater. Workers in their 40s and 50s realize they can’t rely on pensions. |
| 2001–2010 | The Great Recession devastates 401k balances, with some losing 30–40% of their savings. Congress passes the Pension Protection Act (2006), making automatic enrollment more widespread. The average 401k balance of a 50-year-old stagnates or declines for those hit hardest. |
| 2011–2020 | Contribution limits increase to $18,000 (2015). Employers begin offering Roth 401k options. The stock market’s long bull run boosts balances, but wage stagnation means many can’t contribute more. The median balance for 50-year-olds climbs to $165,000, but disparities widen. |
| 2021–Present | COVID-19 causes temporary market volatility, but recovery is swift. The SECURE Act (2019) raises RMD ages to 72, giving older workers more flexibility. Inflation and rising living costs pressure 50-year-olds to save more, but many struggle with student debt or caregiving expenses. |
Lessons From the Journey
- Time is your greatest ally—but it’s not infinite. A 30-year-old has 30 years of compounding; a 50-year-old has 15. The average 401k balance of a 50-year-old reflects this reality: those who started late are still playing catch-up.
- Employer matches are free money. Missing out on even a 3% match means leaving thousands on the table over decades.
- Market downturns are temporary, but behavioral mistakes are permanent. Selling in a panic or taking loans from your 401k can derail retirement plans.
- Inflation is the silent enemy. A $1 million balance in 1990 is worth about $2 million today—but most 50-year-olds haven’t adjusted their savings goals accordingly.
- Healthcare costs are the wild card. Fidelity estimates a 65-year-old couple needs $315,000 for medical expenses alone. Many 50-year-olds haven’t factored this into their 401k balance projections.
- Social Security isn’t enough. The average benefit is around $1,700/month, but most retirees need $4,000–$5,000/month to maintain their lifestyle.
Where Things Stand Today
As of 2023, the average 401k balance for someone turning 50 is estimated at around $250,000, according to Fidelity Investments. But this number is misleading. The median balance—where half have more, half have less—is closer to $165,000. The gap between the two figures highlights how skewed retirement savings are. The top 20% of 50-year-olds have balances exceeding $500,000, while the bottom 20% have less than $50,000. This isn’t just about income; it’s about access. Workers in high-cost cities, gig economy jobs, or industries with no 401k offerings are at a disadvantage. The current state of retirement readiness is a mixed bag. On one hand, more workers are saving than ever before. Automatic enrollment has pushed participation rates above 80% in large companies. On the other, the rising cost of living—housing, healthcare, education—means that the average 401k balance of a 50-year-old may not stretch as far as previous generations assumed. The rule of thumb that you need 70–80% of your pre-retirement income to retire comfortably now feels optimistic for many. Add in longevity—life expectancies are rising—and the math gets tighter. For those who haven’t saved enough, the options are grim: work longer, downsize dramatically, or rely on family.
Conclusion
The story of the average 401k balance of a 50-year-old is one of incremental progress and persistent inequality. What was once a luxury—having any retirement savings at all—has become the expectation. But the numbers tell a more complicated truth: most Americans are saving, but not enough, and not in the right way. The good news? It’s never too late to adjust. Increasing contributions by even $200 a month at 50 can add $50,000 by 65. Switching to a low-cost target-date fund can shave years off your savings timeline. The bad news? The system is rigged against those who start late or face financial shocks. The conversation around retirement has evolved from "Will I have enough?" to "How do I make what I have last?" For the 50-year-old with a $150,000 balance, the focus shifts to withdrawal strategies, part-time work, and healthcare planning. For those with $500,000, it’s about tax efficiency and legacy planning. The average 401k balance of a 50-year-old isn’t just a number—it’s a starting point for a conversation that should have begun decades earlier.Comprehensive FAQs
Q: What’s the difference between the average and median 401k balance for a 50-year-old?
The average 401k balance of a 50-year-old (mean) is skewed higher by a small number of high earners with large balances. The median balance—where half have more, half have less—is a better measure of typical savings. For example, the average might be $250,000, but the median could be $165,000, meaning most 50-year-olds have less than $250,000.
Q: How does a 401k loan affect my retirement savings?
Taking a loan from your 401k reduces your balance and means you’re paying interest back to yourself. However, if you leave your job, the loan may become due immediately, and if unpaid, it’s treated as a withdrawal—subject to taxes and penalties. Worse, the money you borrowed isn’t invested, so you miss out on potential growth. For a 50-year-old, this can significantly cut into their 401k balance at retirement.
Q: Should I roll over my 401k if I change jobs?
Yes, in most cases. Leaving a 401k with a former employer means you lose control over investments and fees. Rolling it into an IRA or your new employer’s 401k keeps your savings consolidated and accessible. If your former employer’s plan has high fees or poor investment options, rolling over is especially important. However, if you have a large balance and want to delay RMDs, leaving it in the old 401k might be an option.
Q: How much should a 50-year-old have in their 401k to retire comfortably?
Financial advisors often cite the "25x rule": you need 25 times your annual retirement expenses saved by age 65. For someone needing $60,000/year, that’s $1.5 million. However, this is a rough estimate. The average 401k balance of a 50-year-old is far below this, so most will need to supplement with Social Security, part-time work, or other income sources. A better target for many is to aim for $1 million or more by 65, adjusted for your specific lifestyle.
Q: Can I contribute to a 401k after I retire?
Yes, but only if you’re still working. Once you stop working, you can no longer contribute to a 401k. However, you can contribute to an IRA (traditional or Roth) or a Health Savings Account (HSA) if you have a high-deductible health plan. For those who retire early, strategies like the "Rule of 55" (allowing penalty-free withdrawals from a 401k after age 55) or part-time consulting can help bridge gaps.
Q: What happens to my 401k if I die before retirement?
If you die before age 70.5, your beneficiaries can roll over your 401k into an IRA or inherit it directly. If you die after 70.5, required minimum distributions (RMDs) must be taken by your beneficiaries. The average 401k balance of a 50-year-old at death can be passed tax-free to heirs if structured correctly (e.g., as a stretch IRA). Without proper planning, beneficiaries may face large tax bills or forced withdrawals.
Q: How does inflation affect my 401k balance over time?
Inflation erodes purchasing power. A $1 million 401k balance in 2023 may only buy what $700,000 bought in 1990. For a 50-year-old, this means their savings may not stretch as far in retirement. To combat this, consider investing a portion of your 401k in assets that historically outpace inflation, like stocks. However, this also increases risk. A balanced approach—such as a target-date fund—can help manage this trade-off.
