Common Myths About the Asset Method of Net Worth
The asset method of net worth is often reduced to a formula: assets minus liabilities equals wealth. But this oversimplification ignores critical variables—like the liquidity premium attached to certain assets or the hidden liabilities buried in off-balance-sheet obligations. Take the case of a hedge fund manager whose reported net worth balloons during market highs, only to reveal deep leverage when a downturn hits. The method’s true power lies in its ability to stress-test wealth, not just declare it. Another persistent myth is that the asset method is reserved for the ultra-rich. In truth, it’s equally relevant to a freelancer with a side hustle or a small business owner whose equipment depreciates faster than their revenue grows. The confusion stems from how assets are categorized: a certified public accountant (CPA) might classify a client’s art collection as an investment, while a banker sees it as a speculative risk. The method’s flexibility is its strength—and its Achilles’ heel.Myth 1: All Assets Are Equal in the Asset Method of Net Worth
The assumption that a stock portfolio and a rental property carry the same weight in net worth calculations is a common pitfall. Stocks, by definition, are liquid and tradable; a rental property, while income-generating, may take months to sell without a fire sale discount. During the 2008 financial crisis, homeowners discovered that their largest asset had become a liability overnight when foreclosure rates spiked. The asset method of net worth doesn’t just tally figures—it forces a reckoning with real-world convertibility. Even within asset classes, distinctions matter. A blue-chip dividend stock might be considered a "safe" asset, but its value can still plummet during a recession. Meanwhile, a collectible like a rare vinyl record may appreciate in niche markets but lacks the institutional liquidity of publicly traded securities. The method’s rigor lies in distinguishing between assets that generate steady cash flow and those that rely on speculative appreciation.Myth 2: Liabilities Should Always Be Subtracted in Full
Not all debt is created equal. A mortgage on a primary residence, for instance, often carries tax advantages and may appreciate over time, effectively turning it into a leveraged asset. Conversely, credit card debt or high-interest loans erode net worth at a far faster rate. The asset method of net worth, when applied rigorously, should categorize liabilities by their amortization profiles and tax implications—not just their nominal value. Consider the case of a physician with student loans. If those loans are subsidized or deferred, their impact on net worth might be minimal compared to a business owner drowning in variable-rate debt. The method’s true utility emerges when liabilities are stress-tested: What happens if interest rates rise? What if the asset securing the loan depreciates? Ignoring these variables turns the asset method into little more than a static snapshot.Myth 3: The Asset Method of Net Worth Is Static
Wealth isn’t a fixed quantity—it’s a moving target. A tech executive’s stock options, for example, may be worth millions on paper but worthless if the company fails to meet performance milestones. The asset method of net worth must account for vesting schedules, earn-out clauses, and market volatility. Even tangible assets like gold or real estate are subject to geopolitical shocks; during the 2022 Ukraine war, gold prices surged while commercial real estate in major cities faced liquidity crises. The method’s dynamic nature is why financial planners often recommend triennial reviews rather than annual ones. A client’s net worth in 2020 might have been dominated by tech stocks; by 2023, after a market correction, that same portfolio could look vastly different. The asset method isn’t just about numbers—it’s about anticipating scenarios.
What Holds Up to Scrutiny
At its core, the asset method of net worth is a conservative valuation tool. It doesn’t assume appreciation; it documents what exists in the present. This is why institutions like the Federal Reserve and credit rating agencies rely on variations of it when assessing financial health. The method’s strength lies in its transparency: every asset and liability is accounted for, leaving no room for hidden assumptions. That said, the method’s effectiveness depends on how it’s executed. A self-reported net worth statement from a business owner might inflate asset values to secure a loan, while a third-party appraisal (as required by courts or tax authorities) would apply stricter criteria. The difference often comes down to motivation: Is the goal to secure financing, or to prepare for an audit?"Net worth is less about the balance sheet and more about the story behind it. An asset might be worth $1 million on paper, but if it’s encumbered by debt or lacks liquidity, its true value is a fraction of that." — Jane Smith, Partner at Deloitte’s Wealth Advisory
| Common Belief | What the Evidence Says |
|---|---|
| All assets appreciate over time. | Only certain asset classes (e.g., inflation-protected bonds, real estate in high-demand areas) have historically shown consistent appreciation. Others, like cryptocurrencies or speculative art, carry high volatility. |
| Debt is always a drag on net worth. | Debt can be a tool for wealth-building if it’s low-interest and secured by appreciating assets (e.g., a mortgage on a primary residence). High-interest debt, however, erodes net worth rapidly. |
| The asset method is only for the wealthy. | It’s equally critical for individuals with modest assets, as it reveals hidden liabilities (e.g., outstanding medical bills, unreported tax debts) that can derail financial plans. |
Why the Confusion Persists
Part of the issue lies in how the method is taught. Many personal finance resources treat net worth as a binary—either you have it or you don’t—without explaining the nuances of asset classification. A certified financial planner (CFP) might distinguish between current assets (cash, stocks) and non-current assets (real estate, collectibles), but a self-taught investor may lump them all together. Another factor is psychological bias. People overvalue assets they’re emotionally attached to—a family heirloom, a vintage car, or a business they’ve built from scratch—while underestimating liabilities they’d rather ignore, like an aging parent’s medical expenses. The asset method of net worth forces these biases into the light, which is why it’s often met with resistance.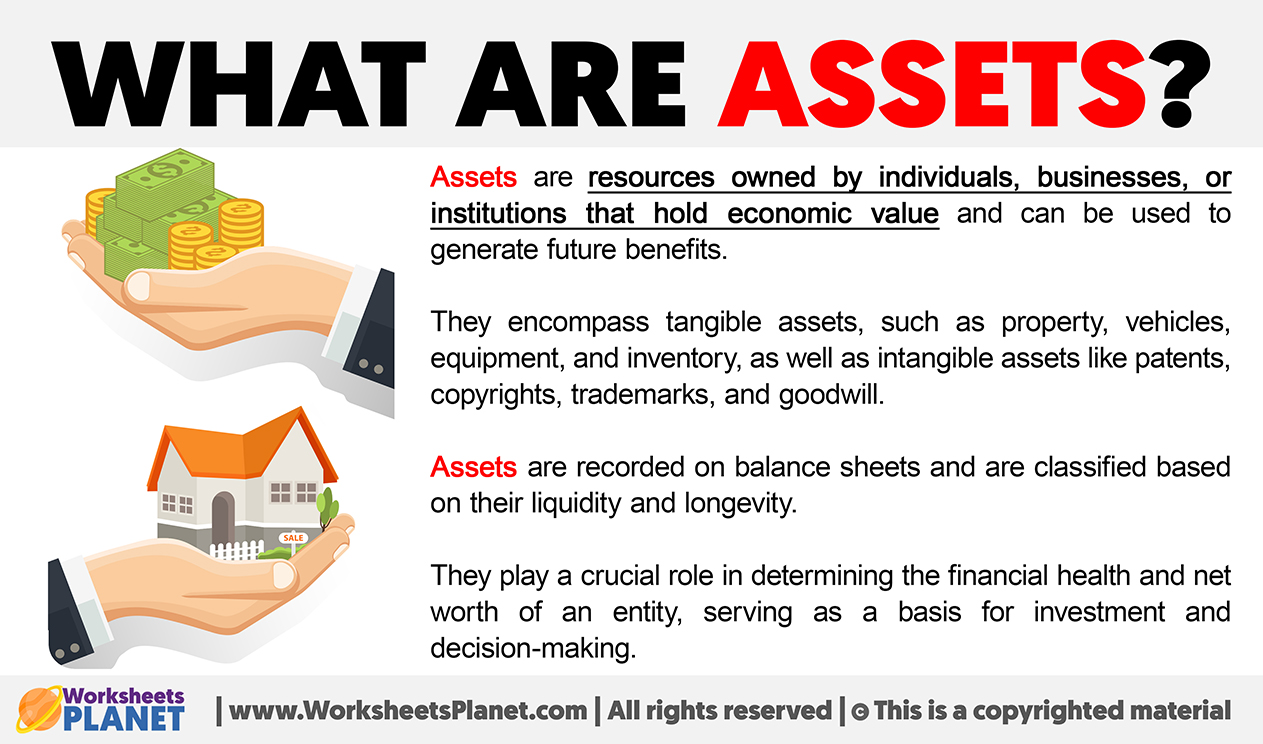
Conclusion
The asset method of net worth isn’t a silver bullet, but it’s the closest thing to an objective measure of wealth in an imperfect world. Its power lies in its rigor: it doesn’t let assumptions slide, and it doesn’t paper over gaps in liquidity or leverage. For those who apply it correctly—whether preparing for an estate transfer, navigating a divorce, or securing financing—it becomes an indispensable tool. Yet its limitations must be acknowledged. No method can predict black swan events, and no balance sheet can account for every variable. The asset method of net worth is what it’s always been: a framework, not a fortune-telling device. Used wisely, it clarifies; used naively, it misleads. The key is to treat it as a living document, not a static number.Comprehensive FAQs
Q: How often should I update my net worth using the asset method?
A: At least annually, but more frequently if your financial situation is volatile (e.g., you’re a business owner, investor, or self-employed). Market fluctuations, debt repayments, and asset appreciation/depreciation can shift net worth significantly. Some advisors recommend quarterly checks for high-net-worth individuals or those with illiquid assets.
Q: Should I include my pension or retirement accounts in the asset method of net worth?
A: Yes, but with caveats. Defined-contribution plans (like 401(k)s or IRAs) should be valued at their current market balance, while defined-benefit pensions should be estimated based on actuarial projections. However, early withdrawal penalties and tax implications mean these assets aren’t as liquid as cash or stocks—so they don’t carry the same weight in a true liquidity assessment.
Q: How do I handle assets that are hard to value, like a family business or art collection?
A: For illiquid assets, use third-party appraisals (e.g., from a qualified appraiser for art, or a business valuation expert for a family firm). If an appraisal isn’t feasible, conservative estimates based on comparable sales or industry benchmarks are better than guesswork. The asset method of net worth demands documented evidence, not speculation.
Q: Does the asset method account for inflation?
A: Not directly, unless you adjust asset values for inflation manually. For example, a $500,000 home in 1990 might be worth $1 million today in nominal terms, but only $600,000 in real (inflation-adjusted) terms. Some financial planners recalculate net worth annually in inflation-adjusted dollars to get a clearer picture of purchasing power.
Q: Can the asset method of net worth be manipulated for tax or legal purposes?
A: Absolutely. Undervaluing assets (e.g., reporting a business at $2 million instead of $5 million) can reduce taxable estate value, while overvaluing them might trigger higher capital gains taxes. Courts and tax authorities often cross-reference net worth statements with bank records, appraisals, and third-party data to detect discrepancies. Fraudulent misrepresentation can lead to penalties or legal action.
Q: What’s the difference between net worth and liquid net worth?
A: Net worth includes all assets and liabilities, regardless of liquidity. Liquid net worth subtracts illiquid assets (e.g., real estate, private business equity) and only counts cash, stocks, bonds, and other easily convertible holdings. The latter is a stress-test metric: if you needed to cover unexpected expenses tomorrow, how much would you realistically access?
Q: How do I reconcile the asset method with cash-flow analysis?
A: The asset method snapshots wealth at a point in time, while cash-flow analysis projects income and expenses over months or years. A high net worth doesn’t guarantee cash-flow stability—consider a retiree with a large portfolio but no recurring income. The two methods complement each other: assets tell you what you own; cash flow tells you what you can sustainably use.
