
The Short Answers
- Bernie Madoff’s $65 billion scheme was the largest in history, running for decades before his 2008 arrest.
- Sarah Palin’s PFC scandal involved a $73 million Ponzi scheme where state funds were misused for personal gains.
- Robert Allen Stanford’s $7 billion fraud targeted wealthy investors with fake hedge fund returns.
- Tom Petters’ $3.65 billion scheme used fake invoices to fund payouts, collapsing in 2008.
- Herbalife’s multi-level marketing model has been accused of Ponzi-like structures, though it’s legally debated.
- Ponzi schemes often target retirees and high-net-worth individuals seeking "safe" returns.
Deep Dive: The Full Picture
The most notorious Ponzi schemes share a DNA: they exploit fear and desire. Fear of missing out (FOMO) on returns, fear of economic instability, and the desire for effortless wealth. Madoff’s operation, for instance, didn’t just sell investments—it sold security. In the 2000s, as markets volatility spiked, his firm became a haven for those who couldn’t stomach risk. The irony? His returns were too consistent, a hallmark of fraud. Stanford’s scheme, meanwhile, dressed itself in the garb of legitimacy: a bank, a hedge fund, a charity. When the FBI finally cracked it, the fraud had already bled into legitimate financial institutions. What separates these schemes from garden-variety fraud is their scale and longevity. Madoff’s operation lasted 20 years, surviving market crashes and regulatory scrutiny. Stanford’s fraud spanned two decades, with payouts continuing even as the scheme’s foundations crumbled. The key to their endurance? Layered deception. Madoff used fake trade confirmations. Stanford fabricated bank statements. Petters forged invoices from non-existent companies. Each layer bought time—until the math became impossible to hide.The Context You Need
The most egregious Ponzi schemes didn’t emerge in a vacuum. They exploited regulatory gaps, cultural blind spots, and psychological triggers. In the 1990s, as the SEC’s resources stretched thin, Madoff’s firm flew under the radar despite his lack of transparency. By the time auditors finally questioned his books, the scheme had grown too large to fail quietly. Similarly, Palin’s PFC scandal thrived in Alaska’s political climate, where state funds were treated as a personal piggy bank by officials who saw oversight as an inconvenience. Economic conditions play a role too. The most successful Ponzi schemes often bloom during uncertainty. Stanford’s fraud accelerated after the 2001 dot-com crash, when investors craved stability. Madoff’s operation peaked in the 2008 financial crisis, when his "hedge" became a lifeline. The schemes don’t just reflect greed—they reflect systemic trust. Investors assume regulators are watching, auditors are competent, and markets are self-correcting. When those assumptions fail, the damage is catastrophic.The Mechanics
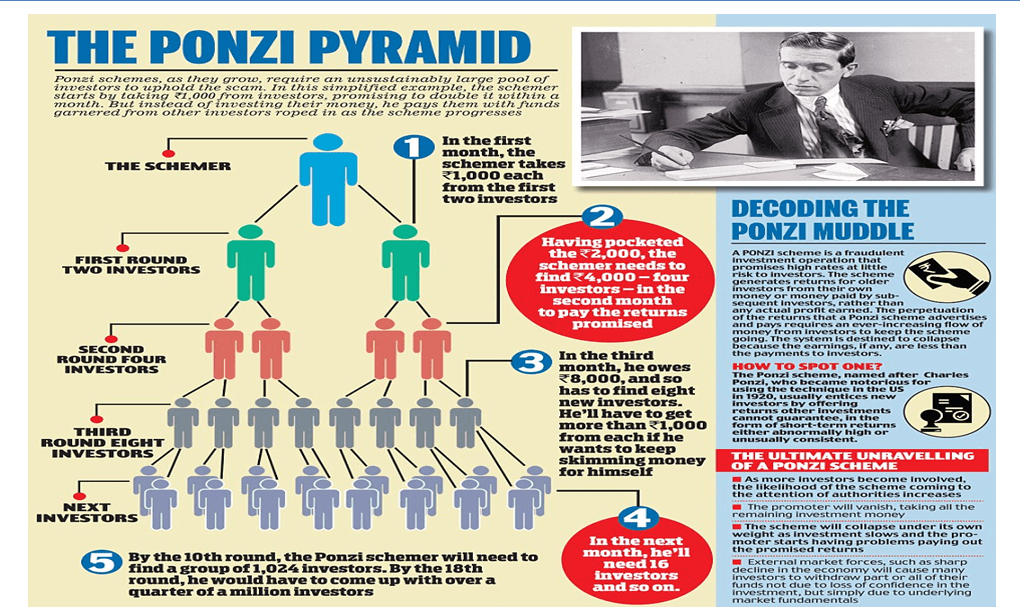
At their core, the most infamous Ponzi schemes follow a predictable script: investor A’s money funds investor B’s payout, which funds investor C’s payout, and so on. The only variable is how long the chain can stretch before the system implodes. Madoff’s method was surgical: he’d take new deposits, pay out a portion to early investors (to maintain the illusion of legitimacy), and pocket the rest. The scheme’s sustainability depended on a steady influx of capital—until the 2008 crisis triggered mass withdrawals, exposing the fraud. What makes these schemes so insidious is their asymmetry of information. Victims rarely see the full ledger. Stanford’s investors, for example, were shown fabricated account statements that matched their expectations—until they weren’t. Petters’ scheme relied on forged invoices from shell companies, making it appear as though his business was thriving. The fraudsters’ greatest tool? Plausible deniability. No single document proved the scheme was a lie—until it was too late.Details That Change the Picture
The human cost of the most devastating Ponzi schemes is often overshadowed by the financial figures. Madoff’s victims included pension funds, universities, and charities—some of which never recovered. Stanford’s fraud left retirees in the Caribbean with worthless certificates. Palin’s PFC scandal forced Alaska to repay millions in misused funds, straining its budget. These weren’t just financial crimes; they were acts of betrayal against people who trusted the system. The schemes also reveal how regulatory capture enables fraud. Madoff’s firm was audited by two Big Four accounting firms—yet neither flagged the inconsistencies. Stanford’s operation had SEC approval for years. The problem isn’t just bad actors; it’s systemic failures. When regulators prioritize appearances over substance, fraudsters exploit the gaps. The most persistent Ponzi schemes aren’t stopped by laws—they’re stopped when the money runs out."The most dangerous Ponzi schemes aren’t the ones that collapse quickly. They’re the ones that last long enough to make people believe the system is working—until it isn’t." — Former SEC Enforcement Director, speaking on Madoff’s fraud
| Scheme | Key Feature |
|---|---|
| Bernie Madoff | Used fake trade confirmations; lasted 20 years; victims included celebrities and institutions. |
| Robert Allen Stanford | Combined hedge fund fraud with a bank; targeted wealthy investors; collapsed in 2009. |
| Tom Petters | Used forged invoices; $3.65 billion lost; involved fake electronics companies. |
| Sarah Palin’s PFC | State funds misused; $73 million in fraud; political connections shielded it for years. |
| Herbalife (controversial) | Multi-level marketing structure; SEC accused it of Ponzi-like payouts; legally debated. |
Conclusion
The most legendary Ponzi schemes aren’t just footnotes in financial history—they’re warnings. They show how easily trust can be weaponized, how regulatory oversight can be bypassed, and how human psychology can turn a lie into an empire. The victims aren’t just the investors who lost money; they’re the auditors who missed the red flags, the regulators who looked the other way, and the culture that rewards short-term gains over integrity. The lessons are clear: transparency isn’t optional, skepticism isn’t cynicism, and no return is worth the risk of a scheme that can’t be verified. The most audacious Ponzi schemes succeed because they exploit doubt—doubt in markets, doubt in institutions, doubt in the people who should have stopped them. The next one is already being built. The question is whether history will repeat itself.Comprehensive FAQs
Q: How do Ponzi schemes differ from pyramid schemes?
A: Ponzi schemes promise returns based on fake investments, while pyramid schemes rely on recruiting new members to pay existing ones. Both are fraudulent, but Ponzi schemes often disguise themselves as legitimate businesses.
Q: Can a Ponzi scheme ever be legal?
A: No. By definition, Ponzi schemes involve fraud. However, some multi-level marketing (MLM) models have faced legal challenges for operating like Ponzi schemes—though courts often distinguish them based on product sales.
Q: Why do people keep falling for Ponzi schemes?
A: Greed, fear of missing out, and overconfidence in "guaranteed" returns. Many victims assume regulators or auditors would catch the fraud—until it’s too late.
Q: What red flags should investors watch for?
A: Consistently high returns with little risk, lack of transparency, pressure to recruit others, and complex fee structures. If an investment sounds too good to be true, it probably is.
Q: How do regulators fail to stop Ponzi schemes?
A: Underfunded agencies, regulatory capture, and reliance on self-reporting. Many fraudsters operate in gray areas until the scheme collapses under its own weight.
Q: Are there modern Ponzi schemes still active today?
A: Yes. Cryptocurrency scams, fake hedge funds, and unregulated investment platforms continue to emerge. The most sophisticated schemes now use blockchain and digital assets to obscure their tracks.
Q: What happens to the perpetrators?
A: Prison sentences are common—Madoff received 150 years, Stanford 110 years—but restitution is often impossible. Many victims never see their money back.
