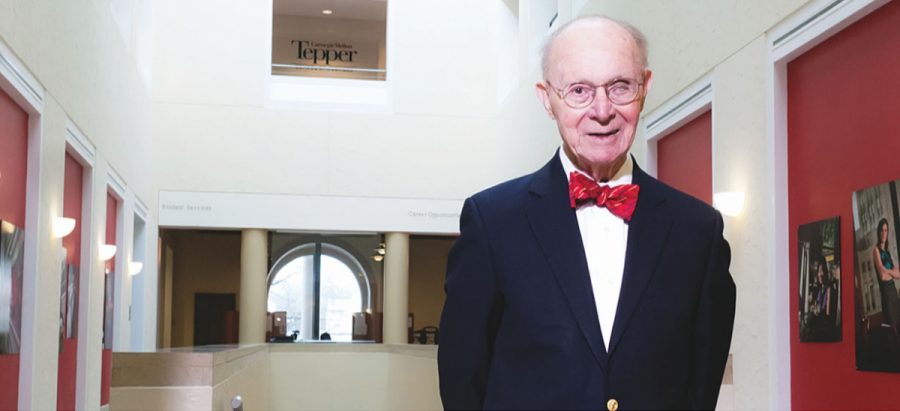
The Complete Overview of Alan Meltzer
Alan Meltzer’s career is a study in how economic ideas can reshape institutions from within. His trajectory began in the post-war academic world, where he challenged the dominant paradigms of the time. At the University of Chicago under Milton Friedman, he absorbed the monetarist school’s emphasis on the money supply as the primary driver of inflation—a radical departure from the Keynesian focus on aggregate demand. This intellectual foundation would later inform his critiques of the Fed’s loose monetary policies during the 1970s, which he argued fueled the worst inflation in modern U.S. history. His 1981 paper "The Demand for Money: Some Theoretical and Empirical Issues" became a touchstone for researchers questioning the stability of velocity-based monetary targeting, a concept the Fed would later abandon in favor of interest rate adjustments. By the 1990s, Alan Meltzer had transitioned from theory to direct engagement with policy. Appointed to the President’s Council of Economic Advisers under Ronald Reagan, he helped craft fiscal policies that emphasized restraint—a stance that would define his later work. His most influential role came in 2000, when he was named to the Federal Advisory Council, a position that gave him unprecedented access to the Fed’s inner workings. There, he advocated for stricter inflation controls and greater transparency in monetary policy decisions. His dissenting votes during periods of aggressive easing—particularly in the 2000s—often foreshadowed the very crises that would later validate his skepticism. The financial meltdown of 2008, for instance, saw his earlier warnings about asset bubbles and regulatory gaps validated in dramatic fashion. What distinguished Alan Meltzer from his peers was his refusal to compartmentalize economics into silos. He treated monetary policy as inseparable from fiscal discipline, arguing that central banks could not compensate for reckless government spending indefinitely. This holistic approach was evident in his 2007 history of the Fed, where he traced the institution’s evolution from a lender of last resort to a de facto manager of financial markets. The book’s publication was not merely academic; it arrived at a moment when the Fed’s balance sheet was expanding at an unprecedented rate, and Meltzer’s historical analysis served as a cautionary tale about the dangers of moral hazard. His later years were marked by a shift toward institutional critique. In essays and interviews, he frequently returned to the theme of central bank independence, arguing that while autonomy was necessary, it could not shield policymakers from the political pressures of the moment. His 2014 paper "The Case for a Rules-Based Monetary Policy" called for a return to fixed monetary growth targets, a proposal that gained traction among those disillusioned with the Fed’s post-crisis interventions. Even as his health declined, his influence endured through the networks he had nurtured—economists, regulators, and policymakers who carried forward his emphasis on principle over expediency.Historical Background and Evolution
The origins of Alan Meltzer’s influence lie in the intellectual ferment of mid-20th-century economics. Trained at the University of Chicago during Friedman’s ascendancy, he absorbed the monetarist critique of activist fiscal policy—a perspective that clashed sharply with the New Deal-era consensus. His early work focused on the instability of velocity, a concept that would later become central to his arguments against discretionary monetary policy. By the 1960s, as stagflation began to grip the U.S., Meltzer’s research on inflation dynamics positioned him as a leading voice in the emerging monetarist movement. His 1969 paper "Money and Inflation: A Re-examination" challenged the prevailing view that inflation was purely a demand-side phenomenon, instead highlighting the role of money supply expansion in eroding purchasing power. The 1970s marked a turning point. As inflation in the U.S. reached double digits, Meltzer’s warnings about the Fed’s accommodative stance gained urgency. His 1977 book Monetary Policy argued that the central bank’s repeated attempts to "fine-tune" the economy had only deepened the cycle of boom and bust. This period also saw him engage directly with policymakers, including Paul Volcker, who would later implement the tight monetary policies Meltzer had advocated. The Volcker disinflation of the early 1980s—though painful—validated Meltzer’s long-held belief that credibility in monetary policy required sacrifice. His role in shaping this era’s economic narrative was not as a lone dissenter but as a bridge between academic theory and practical governance. The transition from the 1980s to the 1990s saw Alan Meltzer expand his focus beyond inflation to include financial regulation and the role of central banks in market stability. His work on bank runs and lender-of-last-resort functions reflected a growing concern about systemic risk—a theme that would dominate his later writings. By the time he joined the Federal Advisory Council in 2000, he had already spent decades refining his views on the dangers of moral hazard, where bailouts encouraged risk-taking without consequences. His dissenting votes during the Greenspan era were not mere academic quibbles; they were grounded in a deep understanding of how financial systems reward short-term speculation over long-term stability. Perhaps his most enduring contribution came in the form of his 2007 history of the Fed. The book was not just a chronological account but a dissection of how institutional design shapes outcomes. Meltzer’s analysis of the Fed’s response to the Great Depression, for instance, highlighted how emergency lending powers had been weaponized to rescue failing institutions—an approach he argued had set a precedent for future crises. The timing of the book’s release was no accident; it arrived as the housing bubble was reaching its peak, and its warnings about regulatory arbitrage and asset price distortions were prescient. In retrospect, the book served as both a historical lesson and a warning about the limits of central bank intervention.Core Mechanisms: How It Works
At its core, Alan Meltzer’s approach to economics was built on three interconnected principles: monetary discipline, institutional transparency, and the primacy of rules over discretion. His monetarist leanings dictated that the money supply should grow at a predictable, steady rate, insulating the economy from the whims of short-term political pressures. This was not a call for rigid orthodoxy but for a framework that reduced the scope for policymaker error—a lesson he drew from the Fed’s repeated failures to anchor inflation expectations during the 1970s. His advocacy for a rules-based system, such as a nominal GDP target, was an attempt to replace the Fed’s ad-hoc responses with a mechanism that could be audited and debated publicly. The second pillar of his methodology was transparency. Meltzer believed that central banks had a duty to communicate their strategies clearly, not just to markets but to the public at large. His critiques of the Fed’s opaque decision-making processes were rooted in the idea that accountability was the antidote to hubris. When he dissented from policy votes, he did so with detailed explanations, forcing his colleagues to confront the assumptions underlying their decisions. This emphasis on intellectual rigor extended to his historical work, where he meticulously documented how the Fed’s actions had either stabilized or destabilized financial markets over time. Finally, Meltzer’s framework was inherently comparative. He frequently contrasted the Fed’s approach with that of other central banks, such as the Bank of England or the European Central Bank, to illustrate how institutional design influenced outcomes. His analysis of the ECB’s response to the eurozone crisis, for instance, highlighted how political fragmentation could undermine monetary policy effectiveness—a dynamic he had observed in the Fed’s dealings with regional banks. This comparative lens allowed him to identify best practices while exposing vulnerabilities in existing systems. His work on lender-of-last-resort functions, for example, demonstrated how the Fed’s emergency lending powers had evolved from a crisis tool into a permanent feature of financial market dependency. What made his mechanisms distinctive was their emphasis on long-term consequences over short-term fixes. While other economists focused on stabilizing output or employment in the near term, Meltzer’s concern was with the structural integrity of the financial system. His warnings about the dangers of "too big to fail" were not just about moral hazard; they were about preserving the conditions that allowed markets to function without constant government intervention. This focus on systemic resilience distinguished his work from both Keynesian stimulus advocates and free-market purists, positioning him as a pragmatist who valued stability over ideology.Key Benefits and Crucial Impact
The impact of Alan Meltzer’s ideas is most visible in the areas where his warnings were heeded—or ignored. His insistence on monetary discipline during the 1970s, for example, aligned with the eventual shift toward inflation targeting in the 1990s. Countries that adopted such frameworks, like Canada and New Zealand, saw lower and more stable inflation rates—a direct outcome of the principles he had championed for decades. Even the Fed’s eventual adoption of inflation targeting in 2012 can be traced back to the intellectual groundwork laid by Meltzer and his monetarist colleagues. His argument that credibility required consistency became a cornerstone of modern central banking doctrine. Yet his influence extended beyond monetary policy. Meltzer’s work on financial regulation anticipated many of the reforms that followed the 2008 crisis, including stricter capital requirements and the dismantling of the "too big to fail" doctrine. His 2007 history of the Fed, with its detailed account of how emergency lending had distorted market behavior, served as a manual for policymakers seeking to avoid repeating past mistakes. The Dodd-Frank Act’s provisions on systemic risk oversight, for instance, reflected many of the concerns Meltzer had raised about the Fed’s role as a backstop for private-sector excess. In this sense, his impact was not just theoretical but actively shaped the regulatory landscape of the 21st century. The broader benefit of his contributions lies in the intellectual humility they demanded. Meltzer’s insistence on rules over discretion was not a rejection of human judgment but a recognition of its limits. His historical analyses demonstrated how even well-intentioned policymakers could be led astray by short-term pressures, a lesson that resonated long after his retirement. By framing monetary policy as a matter of institutional design rather than individual heroics, he elevated the discourse beyond personality-driven narratives to focus on structural solutions. This approach has been particularly influential in emerging markets, where central banks grappling with inflation and currency crises have turned to Meltzer’s work for guidance on how to balance stability with growth. > "The central bank’s job is not to save the economy from its own mistakes but to ensure that those mistakes do not become systemic." —Alan Meltzer, 2014 This quote encapsulates the essence of his impact: a belief that financial governance should be about preventing crises rather than managing their fallout. His emphasis on transparency and accountability has become a standard in modern central banking, with institutions now required to justify their actions in ways that would have been unthinkable during his early career. Even critics of his monetarist views acknowledge that his insistence on clear communication and predictable policy frameworks has made central banks more responsive to public scrutiny—a development with lasting implications for democratic governance.Major Advantages
- Preventive over reactive policy: Meltzer’s focus on rules-based systems reduced the likelihood of policy errors by limiting discretionary interventions. This approach minimized the risk of asset bubbles and financial instability, as seen in the pre-2008 era.
- Enhanced credibility: His advocacy for transparent monetary frameworks strengthened public trust in central banks, a critical factor in maintaining inflation expectations and financial market stability.
- Institutional resilience: By emphasizing systemic risk management, his work contributed to reforms that reduced the frequency and severity of banking crises, as evidenced by post-2008 regulatory changes.
- Long-term orientation: Unlike short-term stimulus measures, Meltzer’s policies prioritized sustainable growth over temporary fixes, aligning with the needs of businesses and households for predictable economic conditions.
- Global influence: His ideas have been adopted by central banks worldwide, particularly in regions prone to inflation volatility, where his monetarist principles have provided a roadmap for stability.

Comparative Analysis
| Alan Meltzer’s Approach | Alternate Economic Models |
|---|---|
| Rules-based monetary policy (e.g., nominal GDP targeting) | Discretionary policy (e.g., Fed’s ad-hoc interest rate adjustments) |
| Emphasis on transparency and accountability | Opaque decision-making (e.g., ECB’s early crisis responses) |
| Focus on systemic risk and moral hazard | Short-term stimulus prioritization (e.g., post-2008 QE) |
| Historical institutional analysis | Theoretical macroeconomic modeling (e.g., DSGE models) |
Future Trends and Innovations
The principles championed by Alan Meltzer remain relevant in an era where central banks are grappling with new challenges—digital currencies, climate-related financial risks, and the persistent specter of inflation. His insistence on monetary discipline could take on new urgency as central banks navigate the complexities of a post-pandemic world, where fiscal and monetary policies have blurred in unprecedented ways. The rise of central bank digital currencies (CBDCs), for instance, presents a test case for his ideas on transparency and accountability. If CBDCs are designed without clear rules governing their issuance, they risk repeating the mistakes of the past—where discretionary policy led to instability. Another frontier is the intersection of monetary policy and environmental sustainability. Meltzer’s focus on long-term stability could inform discussions about how central banks should incorporate climate risks into their mandates. His historical approach would likely emphasize the need for clear, measurable targets—such as carbon-adjusted monetary policy—to avoid the pitfalls of politicized green finance initiatives. The challenge will be balancing these new objectives with the core principles of price stability and financial integrity that defined his career. In this sense, the future of central banking may well hinge on whether policymakers can reconcile Meltzer’s legacy with the demands of a rapidly changing global economy.
Conclusion
Alan Meltzer’s career was defined by an unyielding commitment to economic principles that transcended political cycles. His work was not about advocating for a particular ideology but about ensuring that institutions adhered to rules that prevented short-term gains from undermining long-term stability. In an era where central banks are increasingly expected to address social and environmental challenges, his emphasis on discipline and transparency offers a necessary counterbalance to the temptations of interventionism. The lesson of his life’s work is that financial governance succeeds not when policymakers act boldly in the moment, but when they design systems that limit the scope for error in the first place. His influence will endure not because he offered easy answers but because he demanded rigor—a quality that grows scarcer as the complexity of global finance increases. The next generation of economists and policymakers would do well to revisit his writings, not as relics of a bygone era, but as blueprints for navigating the uncertainties ahead. In a world where financial crises are inevitable, the question is whether institutions will learn from history—or repeat it.Comprehensive FAQs
Q: What was Alan Meltzer’s most significant contribution to economics?
A: His most enduring contribution was advocating for rules-based monetary policy as a safeguard against inflation and financial instability. His work on the Federal Reserve’s history and his critiques of discretionary policy shaped modern central banking, particularly in the areas of transparency and accountability.
Q: How did Alan Meltzer influence the Federal Reserve?
A: As a member of the Federal Advisory Council, he frequently dissented from policy votes, arguing for stricter inflation controls and greater transparency. His historical analyses, particularly his 2007 book on the Fed, influenced reforms aimed at preventing systemic risk and moral hazard.
Q: Was Alan Meltzer a monetarist?
A: Yes, he was a leading figure in the monetarist school, which emphasized the role of the money supply in driving inflation. His early research challenged Keynesian orthodoxy and laid the groundwork for inflation-targeting policies adopted by many central banks.
Q: Did Alan Meltzer predict the 2008 financial crisis?
A: While he didn’t predict the exact timing, his warnings about asset bubbles, regulatory arbitrage, and the dangers of moral hazard in his 2007 book on the Fed were widely seen as prescient. His critiques of the Fed’s loose monetary policies aligned with the eventual collapse.
Q: What is the "Meltzer Rule" referred to in economic circles?
A: There isn’t an official "Meltzer Rule," but his advocacy for fixed monetary growth targets and stricter inflation controls is often informally associated with his name. His proposals for rules-based systems influenced debates on central bank independence and policy transparency.
Q: How did Alan Meltzer view fiscal policy compared to monetary policy?
A: He believed fiscal policy should be constrained to avoid crowding out private investment, while monetary policy should focus on price stability. His skepticism of government intervention extended to both areas, emphasizing that neither should be used as a tool for short-term political gains.
Q: Are there any modern economists who follow Alan Meltzer’s approach?
A: Yes, many contemporary economists and policymakers, particularly those advocating for inflation targeting and rules-based monetary systems, cite his work. His ideas remain influential in central banks and think tanks focused on financial stability and institutional reform.
Q: What is Alan Meltzer’s legacy in financial regulation?
A: His warnings about systemic risk and moral hazard directly informed post-2008 reforms, including stricter capital requirements and the dismantling of "too big to fail." His historical analyses of the Fed’s emergency lending powers provided a framework for modern regulatory oversight.
