
Breaking Down the Numbers
The accredited investor net worth definition is rooted in the Securities Act of 1933, but its modern form was codified in Regulation D and later refined under the JOBS Act of 2012. The baseline remains clear: an individual must either hold net assets of at least $1 million (excluding primary residence) or demonstrate income of $200,000 or more in each of the two most recent years (or $300,000 jointly). Yet the devil lies in the details—what counts as "net worth," how joint filings are calculated, and whether certain assets (like qualified retirement plans) are included. The confusion often stems from how institutions interpret these rules. For instance, a family office managing a portfolio worth $1.2 million might still exclude a $500,000 primary residence, pushing the net worth below the threshold. Similarly, a physician with $250,000 in annual income might qualify individually but fail as part of a joint filing if their spouse’s earnings dip below $50,000. These nuances mean the accredited investor net worth definition isn’t a one-size-fits-all metric—it’s a moving target shaped by personal circumstances.The Verified Baseline
The SEC’s official definition leaves no ambiguity on the core requirement: net worth must exceed $1 million, calculated as total assets minus total liabilities, with the primary residence explicitly excluded. This exclusion is critical—without it, a homeowner with a $1.5 million property but $500,000 in mortgage debt could still fall short. The income-based alternative ($200,000 individual/$300,000 joint) must be sustained for two consecutive years, with no reliance on future projections. What’s often overlooked is the joint filing rule. Couples must meet the $300,000 income threshold together, not individually. This means a dual-income household earning $250,000 each would qualify, but a single earner with $300,000 and a non-working spouse would not. The SEC’s rationale? To ensure investors have demonstrated financial stability beyond temporary spikes. These rules are non-negotiable—they’re enforced by FINRA and state securities regulators alike.What the Estimates Suggest
Industry estimates suggest that roughly 12-15% of U.S. households meet the accredited investor net worth definition, though the figure varies sharply by geography and demographic. In high-cost cities like San Francisco or New York, the bar is functionally higher due to housing expenses, while in lower-cost regions, the same net worth might include a larger primary residence—potentially disqualifying the owner. Some financial planners argue that the $1 million threshold is now closer to $1.2-$1.3 million in real terms, accounting for inflation since 2013. Alternative pathways—such as holding a Series 7 license, CFA charter, or institutional affiliation—have gained traction, particularly in Europe where wealth management firms often rely on professional designations over pure net worth. The SEC’s 2020 expansion to include "knowledgeable employees" of private funds further complicates the picture. Yet these exceptions remain niche; the majority of accredited investors still qualify through traditional wealth metrics. The accredited investor net worth definition, in short, is both a floor and a ceiling—it’s what you need to enter, but also what you must maintain to stay.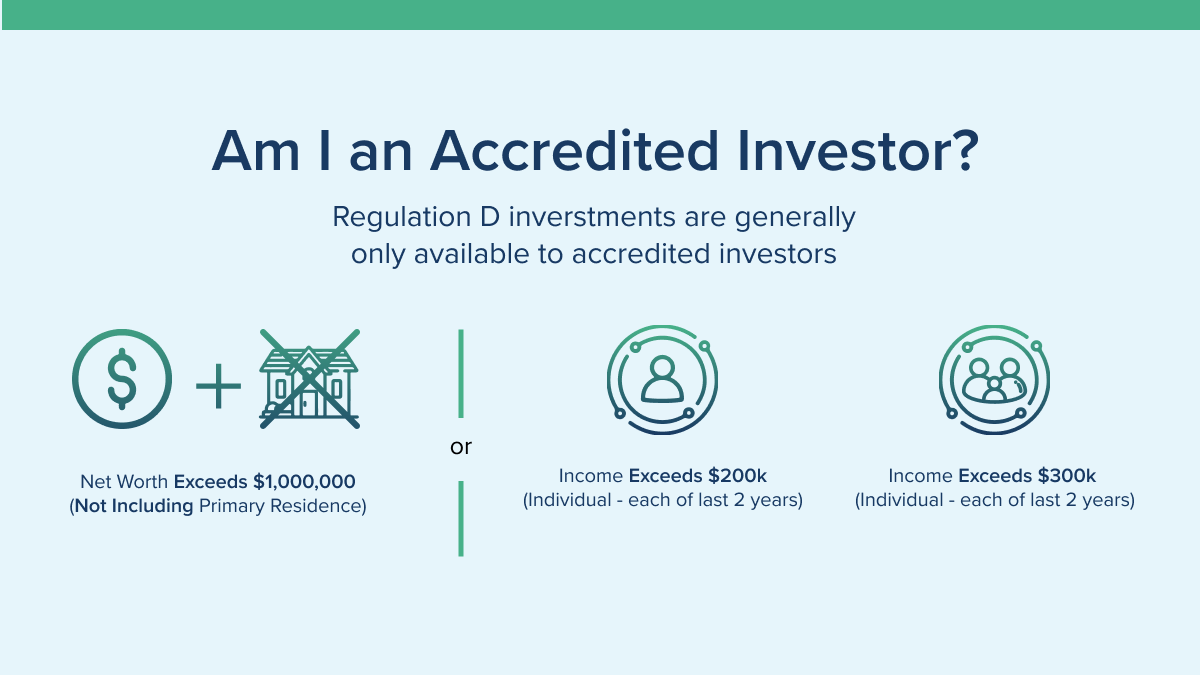
Case Study: A Closer Look
Consider the case of a mid-career tech executive in Austin, Texas, whose compensation package includes stock options, a $1.1 million net worth (excluding a $600,000 home), and $220,000 in annual income. On paper, they meet the income threshold but fall short on net worth—until they exercise a portion of their vested options, pushing their liquid assets above $1 million. This scenario highlights how timing and asset liquidity can determine qualification, even when the underlying financial picture is strong. The executive’s story also underscores the role of primary residence exclusion. Had their home been valued at $800,000 instead of $600,000, they’d still qualify—demonstrating how real estate markets can inadvertently create or eliminate accredited investor status. For fund managers reviewing applications, this means verifying not just balance sheets but also the volatility of assets like crypto or private equity stakes, which may not translate to liquidity when needed."Net worth isn’t static—it’s a snapshot in time. What qualifies you today might not tomorrow, and vice versa. That’s why we ask for two years of tax returns, not just a balance sheet." — Compliance officer at a mid-market private equity firm
| Factor | Estimated Impact on Qualification |
|---|---|
| Primary Residence Valuation | Excluding it can swing qualification by $500K–$1M+; in high-cost markets, this may push net worth below the threshold. |
| Stock Options/Vested Equity | Unvested options don’t count; exercising them may require recalculating net worth mid-year, creating temporary eligibility gaps. |
| Joint Filing Discrepancies | Spousal income below $50K can disqualify a joint filer earning $300K+; some firms overlook this in practice, leading to enforcement risks. |
What This Means Going Forward
The accredited investor net worth definition is under quiet pressure from two fronts. First, regulatory scrutiny is tightening around "accredited" labels, particularly after high-profile fraud cases where investors were misled about their eligibility. The SEC’s 2023 enforcement actions suggest a crackdown on firms that loosely interpret thresholds. Second, global disparities are forcing a reckoning—while the U.S. clings to a $1 million floor, jurisdictions like Singapore and the UAE use income multiples (e.g., 3x median income) that adjust dynamically. For individuals, the takeaway is clear: qualification isn’t a one-time achievement. It demands ongoing documentation, strategic asset management, and an understanding of how liabilities (like student loans or business debts) can reset eligibility overnight. The accredited investor net worth definition isn’t just about crossing a line—it’s about maintaining a posture of financial resilience that regulators and fund managers can trust.
Conclusion
The accredited investor net worth definition is more than a numerical hurdle—it’s a reflection of how capital access is structured in modern finance. For those who meet it, the rewards are substantial: early-stage investments, exclusive fund opportunities, and a seat at the table where deals are made. But the process of qualifying is fraught with pitfalls, from the exclusion of primary residences to the two-year income requirement’s rigidity. The system favors those who can navigate its complexities, often reinforcing existing wealth disparities. As the definition evolves—whether through SEC updates, inflation adjustments, or alternative pathways—the core question remains: Who gets to play, and at what cost? The answer lies not just in the numbers, but in the institutions that enforce them and the individuals who must adapt to survive within them.Comprehensive FAQs
Q: Can I qualify as an accredited investor if my net worth is $1 million but my spouse’s is below $500,000?
A: No. The SEC requires joint net worth of at least $1 million for married couples filing together. If your spouse’s assets push the combined total below $1 million (excluding primary residence), you do not qualify under the net worth pathway. You’d need to meet the $300,000 joint income requirement instead.
Q: Do retirement accounts (like 401(k)s or IRAs) count toward the $1 million net worth threshold?
A: Yes, qualified retirement accounts are included in net worth calculations. However, if the funds are locked in a pension or employer-sponsored plan with restricted access, some fund managers may scrutinize liquidity—though the SEC’s definition does not exclude them outright.
Q: What happens if my net worth dips below $1 million mid-year? Do I lose accredited status immediately?
A: There’s no real-time enforcement, but funds and issuers may reverify eligibility before new investments. If your net worth falls below $1 million at any point, you’d need to rely on the income-based alternative (if applicable) or reapply for future opportunities. Some platforms proactively notify investors of threshold changes.
Q: Can a trust or LLC count toward my accredited investor net worth?
A: Only if you have direct ownership and control of the assets. The SEC’s definition applies to individuals, not entities. For example, if you’re the sole beneficiary of a revocable trust holding $1 million, that may count—but if the trust is irrevocable or held by a third party, it typically doesn’t qualify you.
Q: Are there non-financial ways to become an accredited investor, like through education or experience?
A: Yes. The SEC’s 2020 updates allow individuals with:
- A Series 7, Series 65, or Series 82 license (financial professional designations),
- A CFA charter or similar professional credential, or
- Institutional affiliations (e.g., employees of private funds, family offices).
Q: How often should I update my accredited investor status with funds or platforms?
A: At least annually, though some high-net-worth platforms require quarterly or bi-annual re-verification, especially if your portfolio includes volatile assets (crypto, private equity). A sudden drop in net worth—due to market swings or new liabilities—could trigger a re-evaluation mid-cycle.
Q: What’s the difference between the U.S. and European definitions of accredited investor?
A: The U.S. relies on static wealth/income thresholds ($1M net worth or $200K income). Europe varies by country:
- UK: £100K+ net worth or £160K+ annual income (FCA rules).
- Germany: €100K+ net worth or €100K+ annual income (BaFin).
- Singapore: S$200K+ net worth or S$300K+ annual income (MAS).
