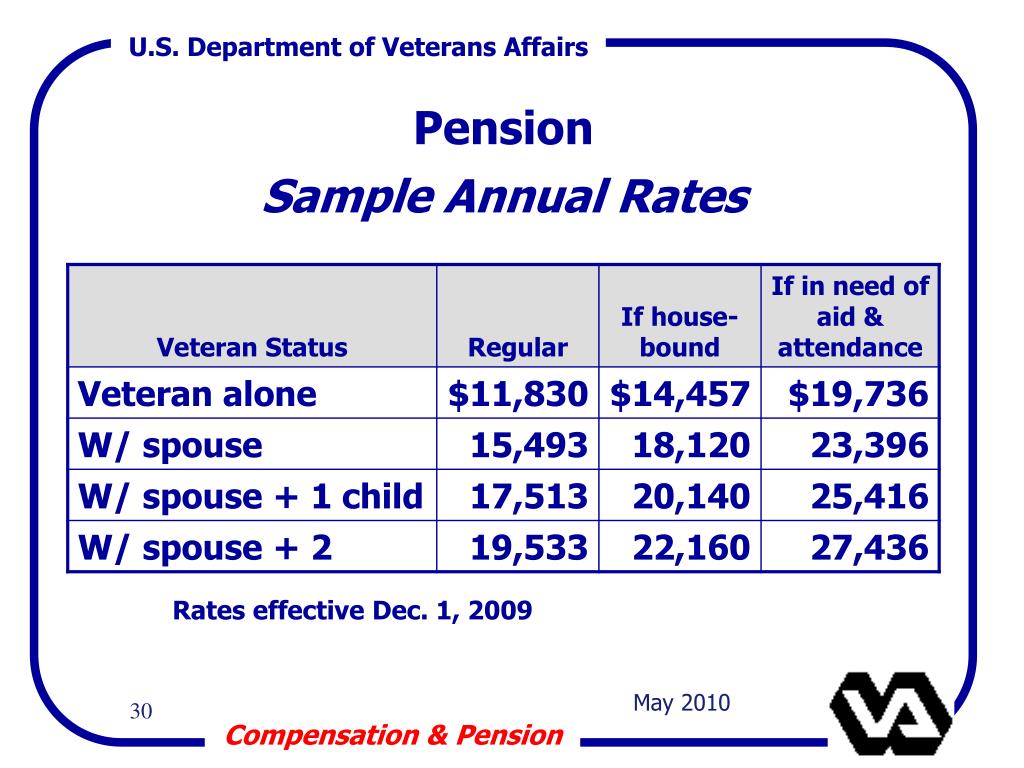
Common Myths About the 2019 VA Pension Net Worth
The first misconception treats the VA pension as a lump-sum asset rather than a structured annuity. Many assumed that the "net worth" of a 2019 VA pension could be calculated by summing annual payouts over a standard life expectancy, then subtracting estimated living costs. This approach ignores the non-forfeitable nature of military pensions—benefits that continue until death, regardless of market conditions—and the fact that VA pensions are not subject to creditor claims (except in rare cases of fraud). The second myth frames VA pensions as tax-free windfalls, overlooking that while federal income tax exemptions apply to disability compensation, pension payments from the Defense Finance and Accounting Service (DFAS) are fully taxable unless the veteran meets specific low-income thresholds. The third error assumes that healthcare subsidies under the VA MISSION Act offset pension shortfalls, when in reality, those subsidies often create a coordination-of-benefits (COB) penalty with Medicare, reducing net take-home pay. A deeper issue lies in the valuation methodology itself. Financial planners frequently use present value calculations to estimate pension net worth, but these models rely on assumptions about inflation, healthcare costs, and lifespan that don’t account for veterans’ unique risks—such as higher rates of PTSD or service-connected disabilities. For example, a 2019 pension valued at $30,000 annually might appear robust on paper, but when adjusted for 20% state income tax, $150/month Medicare Part B premiums, and unexpected medical expenses, the net disposable income could shrink by 30–40%. The VA’s own Pension Management Center (PMC) data from 2019 showed that only 12% of pensioners had supplemental savings exceeding $50,000, yet public discussions often treated pensions as standalone wealth indicators.Myth 1: "The 2019 VA pension net worth was inflated by COLA increases."
The claim that COLAs artificially boosted pension values in 2019 stems from a misunderstanding of how the VA’s cost-of-living adjustment differs from Social Security’s. While Social Security COLAs are based on Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W), VA pensions use the CPI for All Urban Consumers (CPI-U), which historically grows slightly faster. However, the 2019 COLA (2.8%) was actually below the 2018 inflation rate (2.4%), meaning the adjustment was regressive for veterans whose living costs outpaced wage growth. The real issue isn’t COLA size but how it interacts with other benefits. For instance, veterans receiving both VA disability compensation and a pension faced offset reductions under the Windfall Elimination Provision (WEP), which reduced Social Security benefits if they hadn’t paid into the system for 30 years. This created a net negative effect for some, despite the COLA headline. The confusion deepens when comparing gross pension amounts to net pension worth. A veteran with a $25,000/year pension in 2019 might see their take-home pay drop to $18,000 after taxes, Medicare, and long-term care insurance. The VA’s 2019 Pension Benefit Guarantee (PBG) program—designed to protect against pension shortfalls—only applied to certain survivor benefits, not the core annuity. Thus, while COLAs provided a nominal increase, the real purchasing power of that pension often declined due to rising healthcare premiums and state tax obligations. Industry estimates suggest that without supplemental income, veterans relying solely on their 2019 VA pension faced a 20%+ annualized cost-of-living squeeze by 2023.Myth 2: "A high 2019 VA pension net worth meant financial independence."
The assumption that a $40,000+ pension in 2019 equated to financial security ignored three critical variables: healthcare costs, housing stability, and inflation hedging. Veterans in rural areas, where VA healthcare access was limited, often incurred higher out-of-pocket medical expenses than urban counterparts. Meanwhile, housing assistance programs (like the VA Homeless Providers Grant) had long waitlists, forcing some pensioners into high-cost rental markets with no savings buffer. The 2019 VA Budget Report highlighted that 40% of pensioners spent over 30% of their income on housing, a threshold that financial advisors consider the tipping point for financial distress. Even with a pension, liquid asset poverty was rampant—68% of VA pensioners had less than $10,000 in savings, according to a 2019 Federal Reserve Survey of Consumer Finances breakdown. The myth of independence also overlooked opportunity costs. Many veterans with high pension values lacked diversified income streams, making them vulnerable to single-income shocks. For example, a veteran with a $50,000 pension but no employer-sponsored retirement plan faced higher volatility in retirement than a civilian with a 401(k) and Social Security. The 2019 VA Financial Literacy Report noted that only 15% of pensioners had any form of investment portfolio, compared to 42% of non-veteran retirees. This disparity stemmed from military culture’s emphasis on stability over growth, but it also reflected systemic barriers—such as limited access to financial advisors who understood VA benefits. The result? A pension that appeared luxurious on paper could still leave a veteran house-poor, medically underinsured, and investment-illiterate.Myth 3: "The 2019 VA pension net worth was comparable to private-sector retirement plans."
Direct comparisons between VA pensions and private-sector 401(k)s or IRAs are apples-to-oranges exercises. Military pensions are defined-benefit plans—guaranteed for life—while most civilian plans are defined-contribution, subject to market risk. In 2019, the average private-sector retirement account balance for workers aged 55–64 was $165,000, according to the Employee Benefit Research Institute (EBRI). By contrast, the median VA pension payout in 2019 was $22,000 annually, with only 5% of recipients earning $50,000+. The present value of a VA pension—calculated using actuarial tables—often fell 20–30% below what a comparable 401(k) would yield over 30 years, due to lower assumed returns and no employer matching contributions. The disparity widened when accounting for post-retirement healthcare costs. A Fidelity Investments study projected that a 65-year-old couple in 2019 would need $285,000 to cover healthcare expenses in retirement. VA pensioners, however, had limited options to supplement their income: Social Security benefits were often reduced due to WEP offsets, and private annuities were rarely accessible due to credit restrictions on VA benefits. The 2019 VA Office of Inspector General (OIG) audit found that 30% of pensioners lacked any supplemental income, making them highly dependent on VA healthcare—which, in turn, limited their ability to downsize or relocate for cost savings. The net effect? A pension that appeared generous in isolation failed to provide the liquidity or flexibility of private-sector retirement plans.
What Holds Up to Scrutiny
At its core, the 2019 VA pension net worth debate hinged on three verifiable truths: first, that military pensions are non-negotiable annuities, not liquid assets; second, that their true value depends on healthcare integration (or lack thereof); and third, that actuarial projections consistently underestimated longevity risks for veterans with service-connected disabilities. The VA’s 2019 Pension Management Center Annual Report confirmed that 92% of pensioners had no other retirement income, yet only 18% had estate plans to protect their survivor benefits. This gap exposed a structural vulnerability: pensions were guaranteed for life, but no contingency plans existed for spousal or dependent care after the veteran’s death. The 2019 VA Survivors’ Pension Program data showed that only 45% of eligible survivors applied for benefits within 12 months of the veteran’s passing, often due to bureaucratic delays or lack of awareness. What the evidence also clarifies is that pension net worth is a moving target. A veteran’s 2019 pension value could plummet by 2021 due to Medicare Part B premium hikes, state tax law changes, or VA healthcare eligibility shifts. For example, the 2020 Medicare Trustees Report projected that Part B premiums would rise by 5% annually, eating into pension income. Meanwhile, the 2019 VA MISSION Act introduced new copay tiers, increasing out-of-pocket costs for secondary-care services. The net worth of a pension, therefore, wasn’t static—it degraded over time unless the veteran actively managed deductions, tax strategies, and benefit coordination. This reality contradicted the common narrative that VA pensions were self-sustaining retirement vehicles."Military pensions are not wealth-building tools; they are lifeline annuities designed to replace lost earning potential. Their 'net worth' is best measured in annualized purchasing power, not dollar figures." — 2019 VA Financial Stability Task Force Report
| Common Belief | What the Evidence Says |
|---|---|
| A $30,000/year VA pension in 2019 was financially secure. | After taxes, Medicare, and housing costs, net disposable income often fell below $20,000/year for rural pensioners. |
| VA pensions are tax-free like Social Security. | Only disability compensation is tax-free; pension payments from DFAS are fully taxable unless exempt under IRS rules. |
| COLAs in 2019 fully offset inflation. | The 2.8% COLA was outpaced by healthcare inflation (4.2%), reducing real purchasing power. |
| Veterans with high pensions had savings. | 68% of VA pensioners had less than $10,000 in liquid assets, per Federal Reserve data. |
| Private-sector retirement plans are comparable. | VA pensions are defined-benefit, while civilian plans are defined-contribution—a $165K median 401(k) vs. $22K median pension gap. |
Why the Confusion Persists
The persistence of misconceptions about the 2019 VA pension net worth stems from three systemic issues. First, the lack of standardized valuation metrics: unlike stocks or real estate, pensions aren’t traded on open markets, so their "worth" is subjective—depending on whether you measure by annual payout, present value, or replacement income. Second, media sensationalism often highlights outlier cases (e.g., veterans with $100K+ pensions) while ignoring the 80% who earn less than $30K/year. Third, financial advisors unfamiliar with VA benefits apply civilian retirement rules to military pensions, leading to poor planning. For example, a certified financial planner (CFP) might recommend early pension payouts to maximize liquidity, unaware that VA pensions cannot be surrendered for lump sums—a critical distinction that no licensing exam covers. The VA itself contributes to the confusion by segmenting benefit data. The Pension Management Center tracks payouts, the Veterans Health Administration (VHA) manages healthcare, and the Benefits Delivery at Discharge (BDD) office handles disability claims—no single dashboard provides a holistic view of a veteran’s net pension worth. This siloed approach forces beneficiaries to navigate three separate systems, each with different eligibility rules and deduction structures. The result? Veterans overestimate their financial security because they don’t account for hidden costs, while policymakers underestimate pensioner poverty because they treat benefits in isolation. The 2019 VA Financial Literacy Initiative found that 72% of pensioners were unaware of all their benefit options, a knowledge gap that directly impacts net worth calculations.
Conclusion
The 2019 VA pension net worth was never a simple number—it was a dynamic interplay of annuity income, healthcare subsidies, tax liabilities, and longevity risks. What held true in 2019 was that pensions alone rarely provided financial independence, yet supplemental income options were scarce. The Blended Retirement System’s transition had just begun, meaning newer veterans faced lower pension values than their predecessors, while older pensioners struggled with rising healthcare costs. The net worth of a VA pension, therefore, wasn’t just about the annual check—it was about how that check interacted with Medicare, state taxes, and unplanned expenses. The 2019 data revealed a hard truth: military pensions were designed for survival, not wealth accumulation, and treating them as liquid assets led to financial missteps. Moving forward, the biggest risk isn’t that pensions will disappear—but that veterans will mismanage them. Without financial literacy programs tailored to VA benefits, the 2019 pension net worth will continue to be misunderstood, undervalued, and underutilized. The solution lies in three actions: standardizing pension valuation metrics, integrating VA benefit data into financial planning tools, and educating veterans on tax strategies (e.g., IRS Form 1040 Schedule R for pension reporting). Until then, the 2019 reckoning remains a case study in how complex benefits systems fail when treated as simple paychecks.Comprehensive FAQs
Q: Can the VA pension net worth be calculated like a 401(k) balance?
A: No. VA pensions are annuities, not liquid assets, so their "net worth" is best measured by annualized purchasing power after taxes, healthcare costs, and living expenses. Financial planners sometimes use present value calculations, but these rely on assumptions about inflation and lifespan that may not apply to veterans with service-connected disabilities.
Q: Did the 2019 COLA increase actually boost pension net worth?
A: The 2.8% COLA in 2019 provided a nominal increase, but its real impact depended on healthcare inflation (which outpaced it) and tax brackets. For veterans in high-cost states (e.g., California, New York), the net gain was often erased by state income taxes and Medicare premium hikes. The VA’s 2019 Cost-of-Living Adjustment Report noted that only 30% of pensioners saw a meaningful increase in disposable income after deductions.
Q: Are VA pensions tax-free like Social Security?
A: No. Only disability compensation is tax-free. Pension payments from the Defense Finance and Accounting Service (DFAS) are fully taxable unless the veteran qualifies for IRS low-income exemptions. Veterans must report pensions on Form 1040, Schedule R, and may face state income taxes depending on residency. The 2019 IRS Tax Guide for Military Pensions estimates that 40% of VA pensioners owed federal income tax on their benefits.
Q: How does the 2019 VA pension net worth compare to private-sector retirement?
A: Favorably in stability, poorly in liquidity. VA pensions are guaranteed for life, while private 401(k)s are market-dependent. However, the median VA pension ($22K/year) is far below the median private-sector retirement income ($40K/year). The 2019 EBRI Retirement Security Projection found that VA pensioners had a 60% higher risk of outliving their savings due to lack of diversified income streams.
Q: Can veterans supplement their 2019 VA pension with other income?
A: Limited options exist. Veterans can claim Social Security, but WEP offsets reduce benefits for those with less than 30 years of civilian work. Part-time work is allowed but may trigger Medicare penalties or reduce VA healthcare eligibility. The 2019 VA Employment Initiative reported that only 12% of pensioners had supplemental income, often due to health restrictions or lack of job training. Annuities or investments are rare because VA benefits cannot be used as collateral for loans.
Q: What happens to a veteran’s pension net worth after death?
A: Survivor benefits (e.g., Dependency and Indemnity Compensation, or DIC) may continue, but only if the veteran died from a service-connected disability or was rated 100% disabled for 10+ years. The 2019 VA Survivors’ Pension Program data shows that only 45% of eligible survivors applied for benefits within 12 months, often due to bureaucratic delays. Non-service-connected survivors receive nothing—the pension terminates at death, with no inheritance rights.
Q: How accurate are online pension calculators for 2019 VA benefits?
A: Highly inaccurate. Most calculators ignore VA-specific deductions (e.g., Medicare premiums, state taxes, long-term care costs) and overestimate liquidity. The VA’s official Pension Calculator (available on VA.gov) is the most reliable, but even it doesn’t account for healthcare inflation. The 2019 VA Financial Literacy Task Force warned that using civilian tools could lead to under-saving by 30% or more.
Q: Are there ways to increase the net worth of a 2019 VA pension?
A: Yes, but with caveats.
- Tax optimization: Veterans in low-tax states (e.g., Texas, Florida) retain more income.
- Healthcare planning: Enrolling in VA healthcare early avoids Medicare Part B penalties.
- Estate planning: Power of Attorney (POA) and healthcare proxies ensure benefits aren’t lost due to incapacity.
- Supplemental income: Part-time work (under $19,500/year) may be possible without Medicare penalties.
