
5 Things Worth Knowing About the 2010 Wealth Data
The Federal Reserve’s 2010 data on household net worth isn’t just a historical footnote; it’s a snapshot of how wealth distribution operates in practice. Five key insights emerge when dissecting which age group topped the charts that year—and why their dominance wasn’t accidental.1. The Unexpected Age Group: 65–74 Led the Pack
Conventional narratives about wealth accumulation often center on the 55–64 cohort, the group presumed to have maximized careers, mortgages, and investments. Yet the median net worth of 2010 was highest of family households for which age group? The answer, according to the Survey of Consumer Finances, was 65–74-year-olds. This defied expectations because it suggested that the peak of wealth isn’t tied to peak earning years, but rather to the culmination of decades-long asset appreciation—particularly in real estate and retirement accounts. The disparity becomes clearer when comparing this group to younger households. While Gen Xers (then in their 40s) were still grappling with student debt, childcare costs, and stagnant wages, the 65–74 demographic had already navigated the housing market’s post-1980s boom, benefiting from lower interest rates and rising home values. Their net worth wasn’t just higher; it was more resilient to economic downturns, as fixed assets like homes and pensions provided stability that liquid investments couldn’t match.2. Homeownership Was the Decisive Factor
The wealth gap between age groups in 2010 can be traced to a single variable: homeownership rates. By the time the 65–74 cohort reached retirement age, they had spent 30–40 years building equity in primary residences—often purchased at prices that, when adjusted for inflation, were a fraction of today’s costs. For example, the median home price in 1980 was around $74,000; by 2010, that same home would be worth roughly $180,000 (adjusted for inflation), assuming no renovations. Multiply that by decades of mortgage payments and appreciation, and the compounding effect becomes obvious. Younger cohorts, meanwhile, faced a different landscape. The 2008 financial crisis had just wiped out trillions in household wealth, and the subsequent recovery favored those who could afford to buy homes in the pre-2006 bubble. Renters and first-time buyers in 2010 were entering a market where prices were rebounding but wages weren’t keeping pace. The median net worth of 2010 was highest of family households for which age group because the older group had already locked in their largest asset class—homes—before the crash, while younger buyers were playing catch-up in a more volatile environment.3. Retirement Accounts and Pension Windfalls
Beyond real estate, the 65–74 age group benefited from two other financial tailwinds: defined-benefit pensions and the growth of 401(k)s. Many in this cohort had worked during the 1970s and 1980s, when employer-sponsored pensions were still common. By 2010, those pensions had matured, providing steady income streams that didn’t fluctuate with market conditions. Meanwhile, the 401(k) system, which had taken off in the 1990s, allowed them to ride out bull markets in stocks and bonds over decades—something younger workers hadn’t yet experienced. The contrast with younger generations is stark. Millennials entering the workforce in 2010 had little time to benefit from the 2009–2019 bull market, and many were saddled with student loans that ate into their ability to save. The median net worth of 2010 was highest of family households for which age group because the older cohort had decades to let compound interest work in their favor, while younger households were still in the "saving phase" of their financial lives.4. The Role of Inheritance and Family Transfers
Wealth isn’t just earned; it’s often inherited. By 2010, the 65–74 age group had spent years receiving intergenerational transfers—whether through direct inheritances, gifts, or simply living in homes paid off by parents. Studies suggest that wealth transfers account for roughly 20% of the net worth of households headed by someone 65 or older. For younger cohorts, this pipeline was just opening up, and the amounts were typically smaller due to lower asset bases in prior generations. This dynamic explains why the wealth gap between age groups is so pronounced. The median net worth of 2010 was highest of family households for which age group because the older cohort had already benefited from decades of asset accumulation and the transfer of wealth from earlier generations. Younger households, by contrast, were still in the process of building their own estates—if they had the time and resources to do so.5. Policy and Market Timing Created the Divide
The 2010 wealth distribution wasn’t random; it was shaped by policy decisions and market timing. The older cohort had bought homes during periods of low interest rates (e.g., the early 1980s), refinanced during the 1990s boom, and retired just as the Great Recession ended—allowing their portfolios to rebound quickly. Younger households, meanwhile, faced higher interest rates in the 1980s (if they bought then), the dot-com bust, and the 2008 crash, all of which delayed their wealth-building timelines. Tax policies also played a role. The Capital Gains Tax had been lowered in the 1980s and 1990s, benefiting those who sold appreciated assets like homes or stocks. Meanwhile, younger buyers in 2010 faced higher property taxes, capital gains taxes, and student debt burdens that eroded their ability to accumulate wealth at the same rate. The median net worth of 2010 was highest of family households for which age group because the older group had navigated a tax and regulatory environment that favored asset holders, while younger cohorts were still climbing the ladder in a less forgiving system.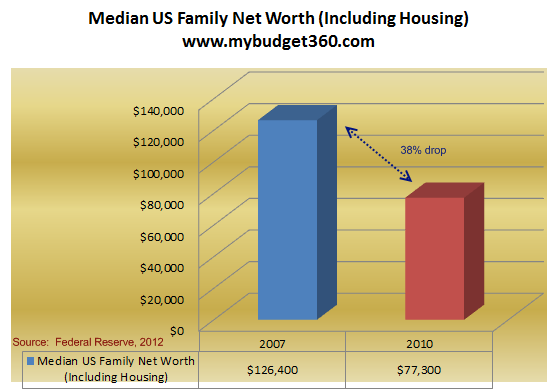
How These Facts Connect
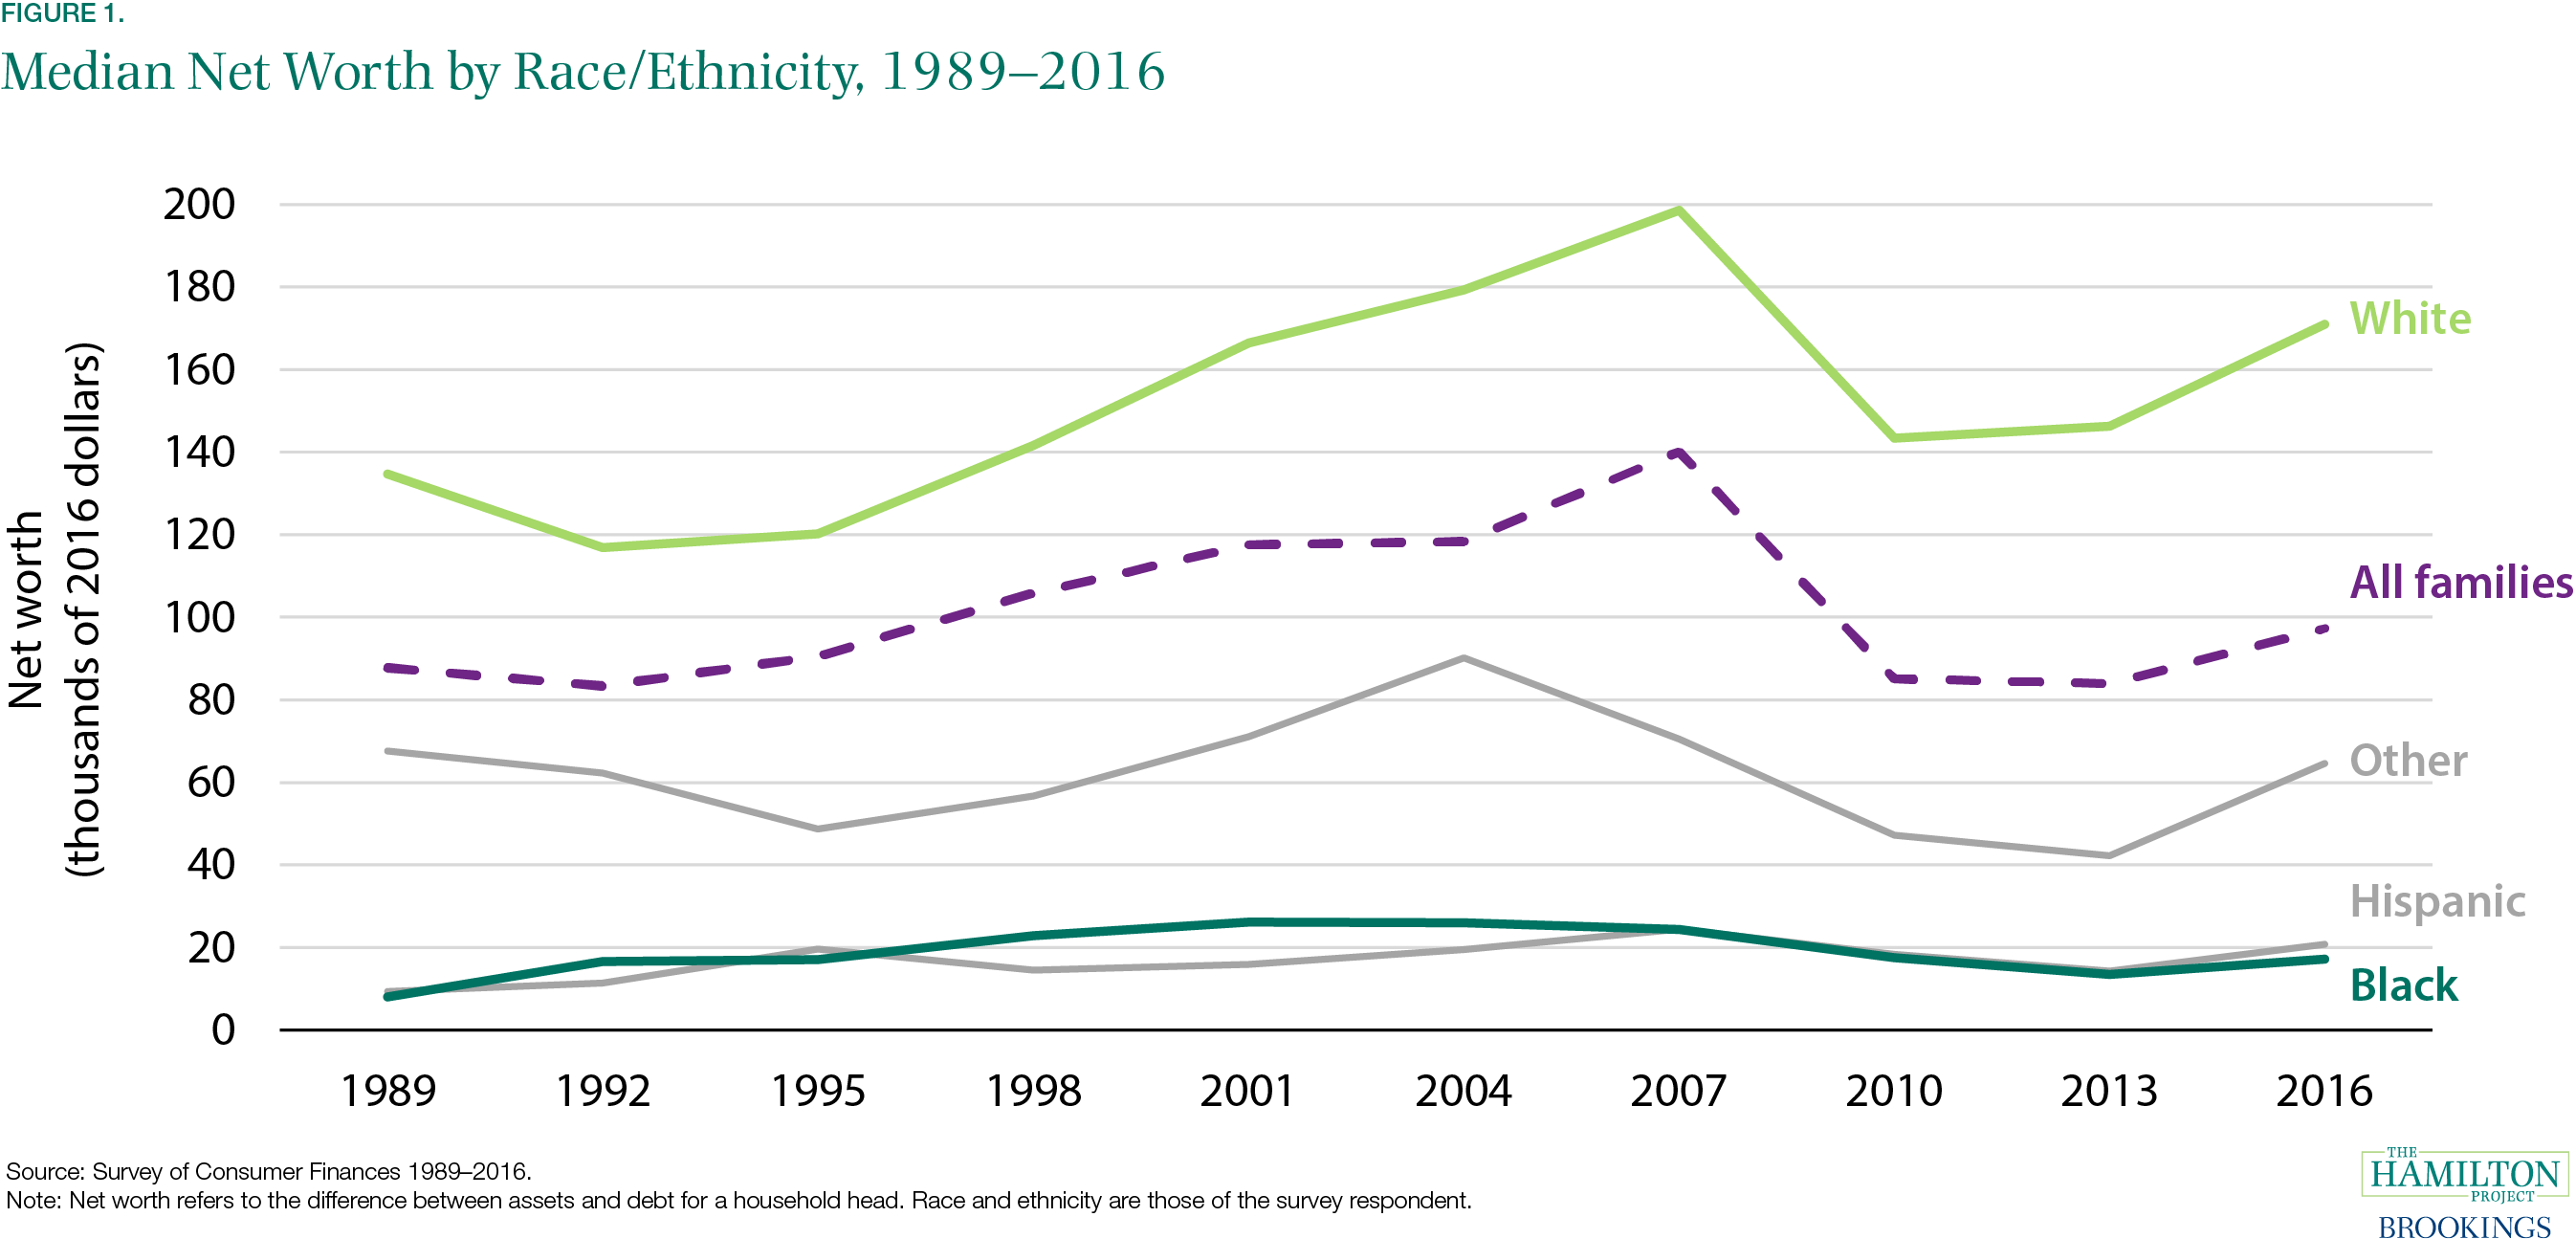
The data from 2010 isn’t just a curiosity—it’s a microcosm of how wealth inequality operates across generations. The dominance of the 65–74 age group in median net worth reveals a system where timing, policy, and asset class exposure determine who rises to the top. Homeownership, retirement accounts, and inheritance aren’t just personal financial strategies; they’re structural advantages that compound over decades. Younger generations, by contrast, enter the game with fewer of these levers at their disposal, whether due to higher costs of living, student debt, or a housing market that no longer rewards long-term equity building in the same way. The table below compares the key drivers of wealth accumulation for the top-performing age group in 2010 versus younger cohorts:| Factor | 65–74 Age Group (2010) | Younger Cohorts (2010) |
|---|---|---|
| Homeownership Rate | ~80% (purchased in low-rate eras) | ~65% (higher prices, student debt) |
| Retirement Accounts | Decades of compounding in 401(k)s/pensions | Early-stage savings, market volatility |
| Inheritance/Transfers | Peak receipt years (parents’ estates) | Emerging transfer recipients |
| Market Timing | Bought low (1980s), sold high (2000s) | Entered post-2008 recovery |
Conclusion
The question of which age group held the highest median net worth in 2010 isn’t just an academic exercise; it’s a mirror held up to the mechanisms of wealth accumulation in America. The answer—65–74-year-olds—challenges the notion that financial success is purely a function of hard work or merit. Instead, it highlights how policy, luck, and timing intersect to create winners and losers in the wealth game. For younger generations, this data serves as both a warning and a call to action: the system is rigged in favor of those who came before, but that doesn’t mean the rules can’t be rewritten. The lesson isn’t to despair, but to recognize that wealth building is a marathon, not a sprint—and that the finish line looks different depending on when you started. The median net worth of 2010 was highest of family households for which age group because history, not just hustle, had stacked the deck in their favor. For those who follow, the challenge is to find new ways to play the game—or change the rules entirely.Comprehensive FAQs
Q: Why does the 65–74 age group have the highest median net worth in 2010?
A: This group benefited from decades of home equity growth, defined-benefit pensions, and lower interest rates when they bought property. They also entered retirement just as the market rebounded from the 2008 crash, while younger cohorts faced higher costs and student debt.
Q: How does this compare to more recent data (e.g., 2020 or 2022)?
A: By 2020, the 65+ cohort’s net worth had grown further due to stock market gains and home price appreciation, but younger groups (Gen X, older millennials) saw faster growth in liquid assets like stocks. The gap persists, but the composition of wealth has shifted—older groups hold more real estate, younger groups more financial assets.
Q: Does this mean older people are always wealthier?
A: Not necessarily. While median net worth peaks in the 65–74 range, the wealthiest 1% often includes younger high-earners (e.g., tech founders). However, median figures reflect the typical household, where older age correlates with more accumulated assets over time.
Q: How does student debt affect younger households’ net worth?
A: Student debt depresses net worth for younger cohorts by reducing their ability to save for homes or investments. In 2010, millennials carried an average of $25,000 in student loans (adjusted for inflation), which delayed homeownership—a key wealth-building tool for older generations.
Q: Can younger generations catch up?
A: It’s possible but requires strategic moves: prioritizing homeownership early, maximizing retirement contributions, and leveraging side income. However, structural barriers—housing costs, wage stagnation—make it harder than in past decades when older cohorts had more affordable entry points.
Q: Where can I find the original 2010 Federal Reserve data?
A: The Survey of Consumer Finances (SCF) for 2010 is publicly available via the Federal Reserve’s Economic Research page. The report breaks down net worth by age, race, and income, offering granular insights into wealth distribution.
