7 Things Worth Knowing About the 2001 Median Net Worth of White Families
The 2001 median net worth of white families was more than a cold statistic—it was a snapshot of an economy on the cusp of transformation. To grasp its implications, we must examine the forces that shaped it: the legacy of past discriminatory policies, the role of homeownership as a wealth multiplier, and the early signs of the financial instability that would later explode in 2008. These seven insights reveal why 2001 was a pivotal year in the story of American wealth.1. The Homeownership Advantage Was Already Fraying
In 2001, homeownership remained the single largest driver of wealth for white families, accounting for nearly 60% of their median net worth. The 2001 median net worth of white families was heavily concentrated in real estate, a trend that would later backfire when housing prices collapsed. By this time, the Community Reinvestment Act—passed in 1977—had begun to encourage banks to lend in low-income neighborhoods, but the benefits had yet to fully trickle down. White families, meanwhile, continued to benefit from intergenerational wealth transfers, including inherited properties and parental financial support, which amplified their homeownership rates. The problem? The housing market in 2001 was already showing signs of speculative excess. Subprime lending was on the rise, but the median net worth of white families in 2001 was still insulated from the worst of it—at least for the time being. Many white households had built equity over decades, while Black and Latino families, often shut out of prime lending pools, relied more heavily on renting. This disparity would later fuel the foreclosure crisis, as white families with substantial home equity weathered the storm better than their minority counterparts.2. Stock Market Volatility Hit White Families Harder Than They Admitted
The dot-com bubble’s collapse in 2000–2001 sent shockwaves through portfolios, but its impact on the 2001 median net worth of white families was uneven. While many white families had 401(k)s or retirement accounts tied to the stock market, fewer had the liquidity to weather the downturn. The median net worth of white families in 2001 included a significant portion in financial assets—around 25% of their total wealth—but for those without diversified investments, the losses were brutal. Meanwhile, Black and Latino families, who had historically been excluded from stock ownership, were less exposed to market volatility. This disparity highlights a critical truth: wealth isn’t just about income—it’s about asset accumulation and risk tolerance. White families in 2001 had more exposure to volatile markets, yet their overall net worth remained higher because they started from a stronger position. The lesson? Wealth begets more wealth, and the 2001 median net worth of white families was a product of decades of systemic advantages.3. The Racial Wealth Gap Was Widening—But Not Everyone Noticed
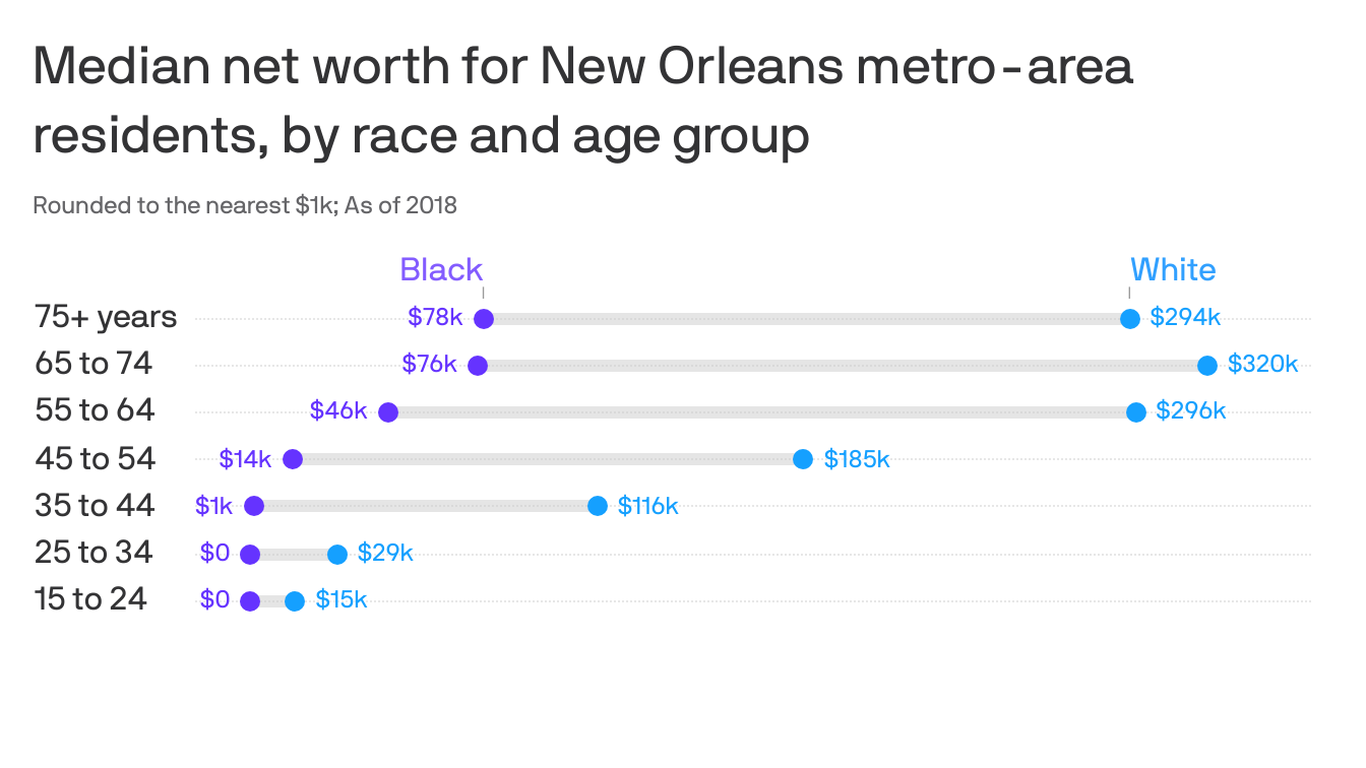
The 2001 median net worth of white families stood at roughly $120,000, while Black families’ median net worth was $17,000 and Latino families’ was $20,000. These numbers, though stark, were not new—they reflected a gap that had persisted since the 1980s. What was different in 2001 was the acceleration of the divide. The early 2000s saw a surge in home values, but minority families were less likely to own homes in the first place. Without access to mortgages, they missed out on the wealth-building power of real estate appreciation."The racial wealth gap isn’t just about income—it’s about the accumulation of assets over generations. By 2001, white families had centuries of unpaid labor, land grants, and discriminatory policies working in their favor. Black and Latino families were still playing catch-up." —Darrick Hamilton, economist and professor at Ohio State UniversityThis gap wasn’t accidental. Redlining, predatory lending, and the lack of federal wealth-building programs like Baby Bonds (which didn’t exist until proposed decades later) ensured that the median net worth of white families would continue to outpace others. The 2001 data was a warning sign—one that policymakers largely ignored until the crisis hit.
4. Student Debt Wasn’t Yet a Crisis—But the Seeds Were Planted
In 2001, student loan debt was a fraction of what it would become, but the 2001 median net worth of white families was already being affected by rising education costs. While white families had higher college attendance rates, they also benefited from inherited wealth and parental support to offset loans. Black and Latino families, with lower median net worths, faced higher debt burdens relative to their incomes—a trend that would explode in the 2010s. The median net worth of white families in 2001 was still largely untouched by student debt, but the early signs were there. As tuition costs rose, white families could more easily absorb the financial burden, while minority families were left with crippling debt and limited career opportunities. This dynamic would later contribute to the racial wealth gap’s expansion, as student loans became another barrier to homeownership and asset accumulation.5. The Gig Economy Didn’t Exist—But Informal Work Was Undermining Wealth
The 2001 median net worth of white families was built on traditional employment structures: steady wages, pensions, and full-time jobs. For many white families, this stability translated into homeownership and retirement savings. Meanwhile, Black and Latino families were more likely to rely on informal work, gig labor, or part-time jobs—none of which contributed to long-term wealth accumulation. The lack of employer-sponsored benefits (like 401(k) matches or health insurance) meant that minority families had fewer avenues to build wealth. The median net worth of white families in 2001 reflected this advantage: they had access to financial tools that minority families did not. This disparity would only grow as the economy shifted toward gig work in the 2010s, leaving marginalized groups further behind.6. Government Policies Were Both Helping and Hindering
The 2001 median net worth of white families was indirectly boosted by policies like the Economic Growth and Tax Relief Reconciliation Act of 2001, which cut capital gains taxes. This benefited wealthier households—disproportionately white—by allowing them to retain more of their investment earnings. Meanwhile, programs like TANF (Temporary Assistance for Needy Families) failed to address wealth-building for low-income families, particularly Black and Latino households. The median net worth of white families in 2001 was also propped up by FHA loans, which had lower down payment requirements but were still inaccessible to many minority families due to credit discrimination. By the time the housing bubble burst, these policies had created a system where white families had more financial cushion to recover from shocks—while minority families had none.7. The Data Was a Preview of the 2008 Crisis
The 2001 median net worth of white families was a harbinger of what was to come. The early 2000s saw a surge in predatory lending, particularly in communities of color, but the median net worth of white families remained high because they were less likely to be targeted by subprime mortgages. When the housing market collapsed in 2008, white families with substantial home equity could refinance or sell, while minority families—who had been steered into risky loans—faced foreclosure and financial ruin. The 2001 data showed that the wealth gap was structural, not accidental. The median net worth of white families was a product of centuries of policy, culture, and economic exclusion. By ignoring these warning signs, policymakers allowed the crisis to deepen—leaving a racial wealth divide that persists today.
How These Facts Connect
The 2001 median net worth of white families wasn’t just a reflection of economic conditions—it was a product of systemic advantages that had been building for generations. Homeownership, stock market exposure, and access to credit all played a role, but the most critical factor was inherited wealth. White families entered the 2000s with a head start, while Black and Latino families were still recovering from centuries of exploitation. What the data reveals is that wealth inequality isn’t just about income—it’s about opportunity. The median net worth of white families in 2001 was higher because they had generational wealth, better credit access, and fewer barriers to asset accumulation. Minority families, meanwhile, were trapped in a cycle of debt and limited opportunities. The early 2000s were the calm before the storm, but the seeds of the 2008 crisis were already planted in the 2001 wealth data.| Factor | Impact on White Families (2001) | Impact on Black/Latino Families (2001) |
|---|---|---|
| Homeownership Rate | ~75% (high equity) | ~45% (lower equity, predatory lending) |
| Stock Market Exposure | ~25% of net worth in financial assets | ~10% (historically excluded) |
| Student Debt Burden | Lower relative to income | Higher, limiting wealth-building |
| Government Policy Benefits | Tax cuts, FHA loans, inheritance advantages | Limited access to wealth-building programs |
Conclusion
The 2001 median net worth of white families was a snapshot of an economy at a crossroads. It reflected the lingering effects of redlining, the benefits of homeownership, and the early signs of financial instability. Yet it also revealed a harsh truth: wealth inequality was not a bug in the system—it was a feature. The data from 2001 shows that the racial wealth gap was widening long before the 2008 crisis, and that the policies in place at the time were designed to perpetuate it. Today, the lessons of 2001 are more relevant than ever. The median net worth of white families has since grown, but so has the gap between them and minority families. Without targeted policies—like Baby Bonds, wealth-building incentives, and fair lending reforms—the cycle of inequality will continue. The data from two decades ago should serve as a warning: economic prosperity is not distributed equally, and the consequences of ignoring that fact are severe.Comprehensive FAQs
Q: How accurate were the 2001 net worth estimates for white families?
The 2001 median net worth of white families was derived from the Federal Reserve’s Survey of Consumer Finances (SCF), which is widely considered the gold standard for wealth data. However, the SCF has limitations—it relies on self-reported data, which can understate wealth for lower-income households. For white families, the estimates are generally reliable, but they still don’t capture informal wealth (like undocumented assets) or regional variations.
Q: Did the 2001 median net worth of white families include business assets?
Yes, the 2001 median net worth of white families included business equity, which accounted for roughly 10-15% of total wealth. White families were more likely to own small businesses or have shares in family-run enterprises, which contributed to their higher net worth. Black and Latino families, meanwhile, had far less business ownership—partly due to limited access to capital and discriminatory lending practices.
Q: How did the dot-com crash affect the median net worth of white families differently than other groups?
The dot-com crash in 2000–2001 disproportionately hurt white families who had heavily invested in tech stocks or relied on stock-based compensation. However, because white families had higher overall net worth, they were better able to absorb the losses. Black and Latino families, who had less exposure to the stock market, were less affected—but they also missed out on the wealth-building opportunities that stocks provided. The crash widened the gap by eroding liquid assets for wealthier households while leaving minority families with fewer recovery options.
Q: Were there any policies in 2001 that could have reduced the racial wealth gap?
Yes, but few were implemented. Policies like Baby Bonds (proposed later) or expanded access to homeownership could have helped. In 2001, the Community Reinvestment Act (CRA) was still in its early stages of encouraging banks to lend in minority neighborhoods, but enforcement was weak. Other potential solutions—like wealth-building incentives for low-income families—were barely discussed. The 2001 median net worth of white families was a product of inaction, not just economic conditions.
Q: How does the 2001 median net worth compare to today’s figures?
Adjusting for inflation, the 2001 median net worth of white families (~$120,000) would be roughly $180,000 today. However, the racial wealth gap has widened—in 2022, the median net worth for white families was $188,200, while for Black families it was $36,100 and for Latino families $72,000. The gap grew because home values surged post-2008, benefiting white families with existing equity, while minority families faced higher debt burdens and limited access to wealth-building tools.
Q: Can the 2001 data explain why wealth inequality persists today?
Absolutely. The 2001 median net worth of white families was a product of centuries of discriminatory policies, intergenerational wealth transfers, and unequal access to credit. These factors didn’t disappear after 2001—they intensified. The 2008 crisis exacerbated the gap, and since then, policies like student debt forgiveness debates and homeownership disparities have kept the divide in place. Without direct wealth-building interventions, the patterns from 2001 will continue to shape inequality for decades.
