Common Myths About Who Are the 1% in Net Worth in the U.S. in 2018
The narrative around the top 1% often reduces them to a monolithic bloc of old-money elites or tech bro billionaires. In reality, the composition of this group was far more fragmented. One persistent myth is that the 1% were primarily corporate executives—CEOs and CFOs whose compensation packages ballooned in the 2000s. While this was true for a subset, the data shows that by 2018, only about 15% of the top 1% derived their wealth primarily from executive salaries. The rest came from ownership stakes, dividends, or capital appreciation in assets like real estate and stocks. Another misconception is that the 1% were uniformly white males, overlooking the growing number of women and minorities who entered the ranks through entrepreneurship or inheritance. The truth is more complex: the 1% in 2018 was a patchwork of old guard financiers, tech disruptors, and accidental beneficiaries of economic shifts. Equally misleading is the idea that the 1% were uniformly self-made. While stories of overnight success—like the founders of unicorn startups—dominate headlines, the majority of the top 1% in 2018 had inherited wealth or leveraged existing networks. A 2019 study by the Federal Reserve found that 40% of millionaires in the U.S. had inherited at least some of their wealth, and this figure was likely higher among the top 1%. The myth of the rugged individualist obscures the reality: access to capital, education, and social capital mattered more than raw talent. Even those who built fortunes from scratch often did so by exploiting loopholes—like carried interest in private equity—that were unavailable to the broader population.Myth 1: The 1% Were Mostly Tech Billionaires
The media’s fixation on Silicon Valley’s elite—think Mark Zuckerberg or Elon Musk—paints a distorted picture. While tech wealth surged in 2018, only about 5% of the top 1% derived their primary wealth from technology-related ventures. The rest were spread across finance, real estate, manufacturing, and even traditional industries like energy and agriculture. The real drivers of wealth accumulation in 2018 were asset classes that had been quietly appreciating for decades: commercial real estate in gateway cities, publicly traded stocks, and private equity stakes. The tech boom was a symptom of broader trends, not the sole engine of the 1%’s prosperity. Moreover, the concentration of wealth in tech was skewed toward a handful of individuals. The top 10 tech billionaires in 2018 collectively held wealth estimated at $500 billion, but this represented less than 2% of the total net worth of the top 1%. The majority of the 1% were not household names; they were the silent partners in hedge funds, the family offices managing multi-generational fortunes, and the corporate raiders who restructured industries. The myth of the tech billionaire overshadows the far larger group of wealth holders who operated in the shadows.Myth 2: The 1% Were All White Men
Diversity within the top 1% is often underestimated. While it’s true that white men dominated the ranks, women and minorities were making inroads—though not at proportional rates. By 2018, women accounted for about 20% of the top 1%, up from 10% in the 1980s, largely due to inheritance and entrepreneurial success in sectors like real estate and professional services. Minorities, particularly Asian Americans, were also overrepresented in certain niches, such as tech and finance, where they held key positions in wealth management and venture capital. However, the data reveals a stark racial wealth gap: Black and Hispanic households were vastly underrepresented in the top 1%, not due to a lack of ambition, but systemic barriers to capital accumulation. The myth of homogeneity ignores the role of legacy wealth in perpetuating disparities. For example, white families had 8 to 10 times more wealth than Black families by 2018, according to the Federal Reserve. This gap wasn’t just about income—it was about generational access to assets like homeownership, stocks, and business ownership. The 1% in 2018 was not a monolith; it was a reflection of historical inequities, where opportunity was unevenly distributed long before the wealth gap widened.Myth 3: The 1% Were All Active Investors or Entrepreneurs
Passive wealth accumulation was the norm for the majority of the top 1%. While headlines celebrate the hustle of startup founders, the reality is that over 60% of the top 1% in 2018 derived their wealth primarily from dividends, capital gains, or rental income—not from active labor. This group included retirees living off stock portfolios, heirs managing trust funds, and investors who had long since exited the day-to-day operations of their businesses. The myth of the self-made entrepreneur ignores the fact that wealth often compounds over generations with minimal effort required to maintain it. Even among those who were actively engaged in business, many were not hands-on operators. Private equity partners, for instance, often earned their returns by restructuring companies they didn’t personally run. The top 1% in 2018 was less about individual effort and more about structural advantages—tax policies favoring capital over labor, the ability to defer taxes on unrealized gains, and the sheer scale of assets that generated passive income. The image of the hardworking tycoon is a convenient narrative, but the truth is far more about inheritance, timing, and systemic design.
What Holds Up to Scrutiny
The most reliable data on who are the 1% in net worth in the U.S. in 2018 comes from three sources: the Federal Reserve’s Survey of Consumer Finances, Forbes’ Real-Time Billionaires List, and tax filings analyzed by the IRS and academic researchers. These sources reveal a few consistent patterns. First, the top 1% in 2018 was heavily concentrated in a handful of asset classes: publicly traded stocks (particularly in tech and healthcare), private equity, real estate (especially in coastal cities), and cash equivalents. Second, inheritance played a larger role than commonly acknowledged, with roughly 30% of the top 1% receiving significant wealth transfers from previous generations. Third, geographic clustering was pronounced—New York, California, and Florida accounted for nearly half of all top 1% households, with Manhattan alone hosting more millionaires per square mile than any other U.S. city. The evidence also challenges the notion that the 1% were uniformly wealthy in the same way. While the median net worth of a top 1% household in 2018 was $11.7 million, the distribution was highly skewed. The top 0.1% (those with net worths exceeding $30 million) held nearly 40% of the total wealth of the top 1%. This ultra-elite subset was far more likely to be involved in high-stakes finance, private equity, or global investment strategies. The rest of the 1%—those with net worths between $1 million and $30 million—were more likely to be professionals (doctors, lawyers, executives), small business owners, or retirees with substantial portfolios."Wealth in America is not just about income—it’s about access to assets that appreciate over time. The top 1% don’t just earn more; they own the machines that generate returns for everyone else." — Edward N. Wolff, Professor of Economics at NYU and author of The Asset Price Meltdown
| Common Belief | What the Evidence Says |
|---|---|
| The 1% are mostly tech CEOs. | Only ~5% of the top 1% derive wealth primarily from tech; the rest are in finance, real estate, and legacy industries. |
| They’re all self-made. | ~40% of millionaires (and likely more in the top 1%) inherited at least some wealth. |
| Wealth is evenly distributed within the 1%. | The top 0.1% hold ~40% of the top 1%’s total wealth; the median is $11.7M, but the mean is far higher. |
Why the Confusion Persists
The public’s misunderstanding of who are the 1% in net worth in the U.S. in 2018 stems from two interconnected problems: media narratives and data limitations. Journalists, chasing the next viral story, focus on the most visible figures—like Jeff Bezos or the founders of the latest unicorn—while ignoring the quiet accumulation of wealth in private equity or family trusts. This creates a halo effect, where a few high-profile individuals come to represent an entire stratum. Meanwhile, academic research often struggles to track wealth in real time, relying on snapshots from the Survey of Consumer Finances, which undercounts assets like private businesses and offshore holdings. The second issue is class blindness. Most Americans don’t interact with the top 1% on a daily basis, making it easy to romanticize or demonize them without nuance. The wealthy are often portrayed as either robber barons or selfless innovators, with little acknowledgment of the structural advantages that allowed them to accumulate wealth. Tax policies like the 2017 Tax Cuts and Jobs Act, which slashed rates on capital gains, benefited the 1% disproportionately, but these changes were framed as broad-based economic stimulus rather than a wealth transfer. The result is a feedback loop: the more the public misunderstands how wealth is concentrated, the more policies are written that reinforce that concentration.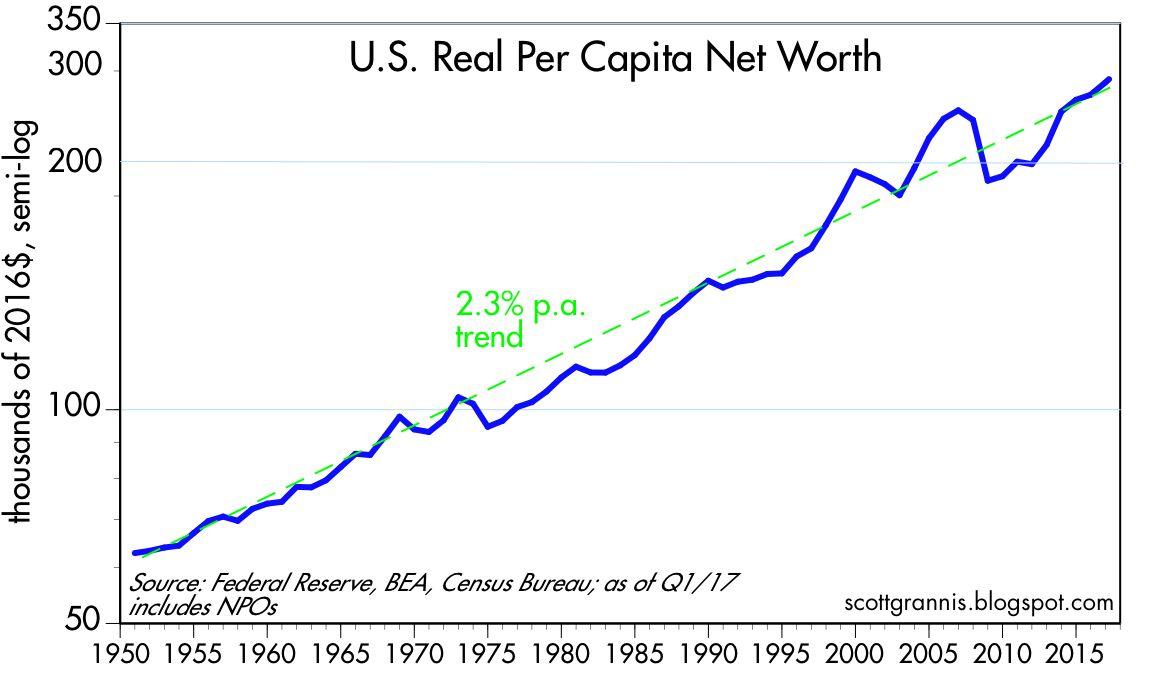
Conclusion
The top 1% in net worth in the U.S. in 2018 were not a homogeneous group of tech moguls or old-money elites. They were a diverse but structurally advantaged cohort, whose wealth was concentrated in assets that compounded over time—stocks, real estate, and private equity—while their access to capital and political influence allowed them to shape the rules of the game. The myths surrounding them—whether about their origins, demographics, or activities—obscure the reality: wealth in America is not just about what you earn, but what you own, and who you know. Understanding this group isn’t just an exercise in economic analysis; it’s a lens into the broader forces reshaping the country. The policies that allowed the 1% to thrive—from deregulation in the 1980s to the tax cuts of the 2010s—were not accidents. They were deliberate choices that concentrated power and wealth in fewer hands. Moving forward, the question isn’t just who the 1% are, but how society will respond to their dominance. Will the rules be rewritten to create a more equitable distribution of opportunity? Or will the structures that created the 1% in the first place persist, ensuring that the next generation of wealth holders looks much like the last?Comprehensive FAQs
Q: How was the top 1% defined in 2018?
A: The threshold for the top 1% in net worth in the U.S. in 2018 was approximately $11.7 million for a household, based on the Federal Reserve’s Survey of Consumer Finances. This figure adjusted for inflation would be higher today, but in 2018, it represented the point at which a household’s wealth placed them in the top 1% of all U.S. households. The definition varies slightly depending on whether liquid assets (like stocks) or total net worth (including homes and businesses) are considered.
Q: Were there more self-made individuals in the top 1% in 2018 than inherited wealth?
A: No. While the media often highlights self-made billionaires, inheritance played a significant role for the top 1%. Studies suggest that 30-40% of millionaires (and likely a higher percentage of the top 1%) had inherited at least some wealth. The rest built fortunes through a combination of entrepreneurship, executive compensation, and strategic investments—often with the help of existing family networks or educational advantages that gave them access to capital.
Q: What industries were the top 1% most involved in?
A: The top 1% in 2018 were not evenly distributed across industries. The largest concentrations were in:
- Finance and investment (private equity, hedge funds, venture capital)
- Technology (though this accounted for a smaller share than often assumed)
- Real estate (particularly in high-value markets like New York, San Francisco, and Miami)
- Healthcare and pharmaceuticals (due to stock appreciation and executive compensation)
- Legacy industries like energy, manufacturing, and agriculture, where family wealth had been accumulated over generations.
Q: How did the top 1% in 2018 differ from the top 1% in previous decades?
A: The top 1% in 2018 were distinct from earlier generations in several key ways:
- Asset concentration: Unlike the post-WWII era, when wealth was more evenly distributed, the 1% in 2018 held a disproportionate share of financial assets (stocks, bonds, private equity), which appreciated far faster than wages.
- Geographic clustering: The rise of coastal cities (New York, San Francisco, Boston) as wealth hubs was a 21st-century phenomenon, whereas earlier elites were more spread across industrial centers.
- Passive income dominance: More of the top 1% in 2018 relied on dividends, capital gains, and rental income than on active labor or business management.
- Political influence: The 1% in 2018 had unprecedented access to policy-making, with direct lobbying, Super PAC contributions, and revolving-door appointments between government and finance.
Q: What role did tax policy play in shaping the top 1% in 2018?
A: Tax policy was critical in enabling the concentration of wealth seen in 2018. Key factors included:
- The 2017 Tax Cuts and Jobs Act, which slashed the capital gains tax (from 20% to 15% for most earners) and allowed businesses to repatriate foreign earnings at a low rate, boosting corporate stock prices.
- The carried interest loophole, which allowed private equity managers to pay lower tax rates on profits than their employees or investors.
- The step-up in basis rule, which eliminated capital gains taxes on inherited assets, making wealth transfers more attractive.
- Wealthy individuals also exploited offshore accounts and trusts to defer or avoid taxes entirely.
Q: How did the top 1% in 2018 compare to the top 1% globally?
A: The U.S. top 1% in 2018 were wealthier on average than their counterparts in most other countries, but the global elite were increasingly interconnected. Key comparisons:
- U.S. dominance: The U.S. held nearly 40% of the world’s billionaires in 2018, with the top 1% controlling a disproportionate share of global financial assets.
- European contrasts: In countries like Germany or France, the top 1% were more likely to be tied to family-owned businesses or industrial dynasties, whereas in the U.S., finance and tech dominated.
- Tax competition: Wealthy individuals in Europe often relocated to the U.S. or Switzerland to take advantage of lower tax burdens, further concentrating global wealth in a few hubs.
- Asian rise: While the U.S. led in absolute terms, China’s top 1% were growing rapidly, with wealth tied to real estate and state-connected businesses.
