The Complete Overview of Thailand’s Financial Floor
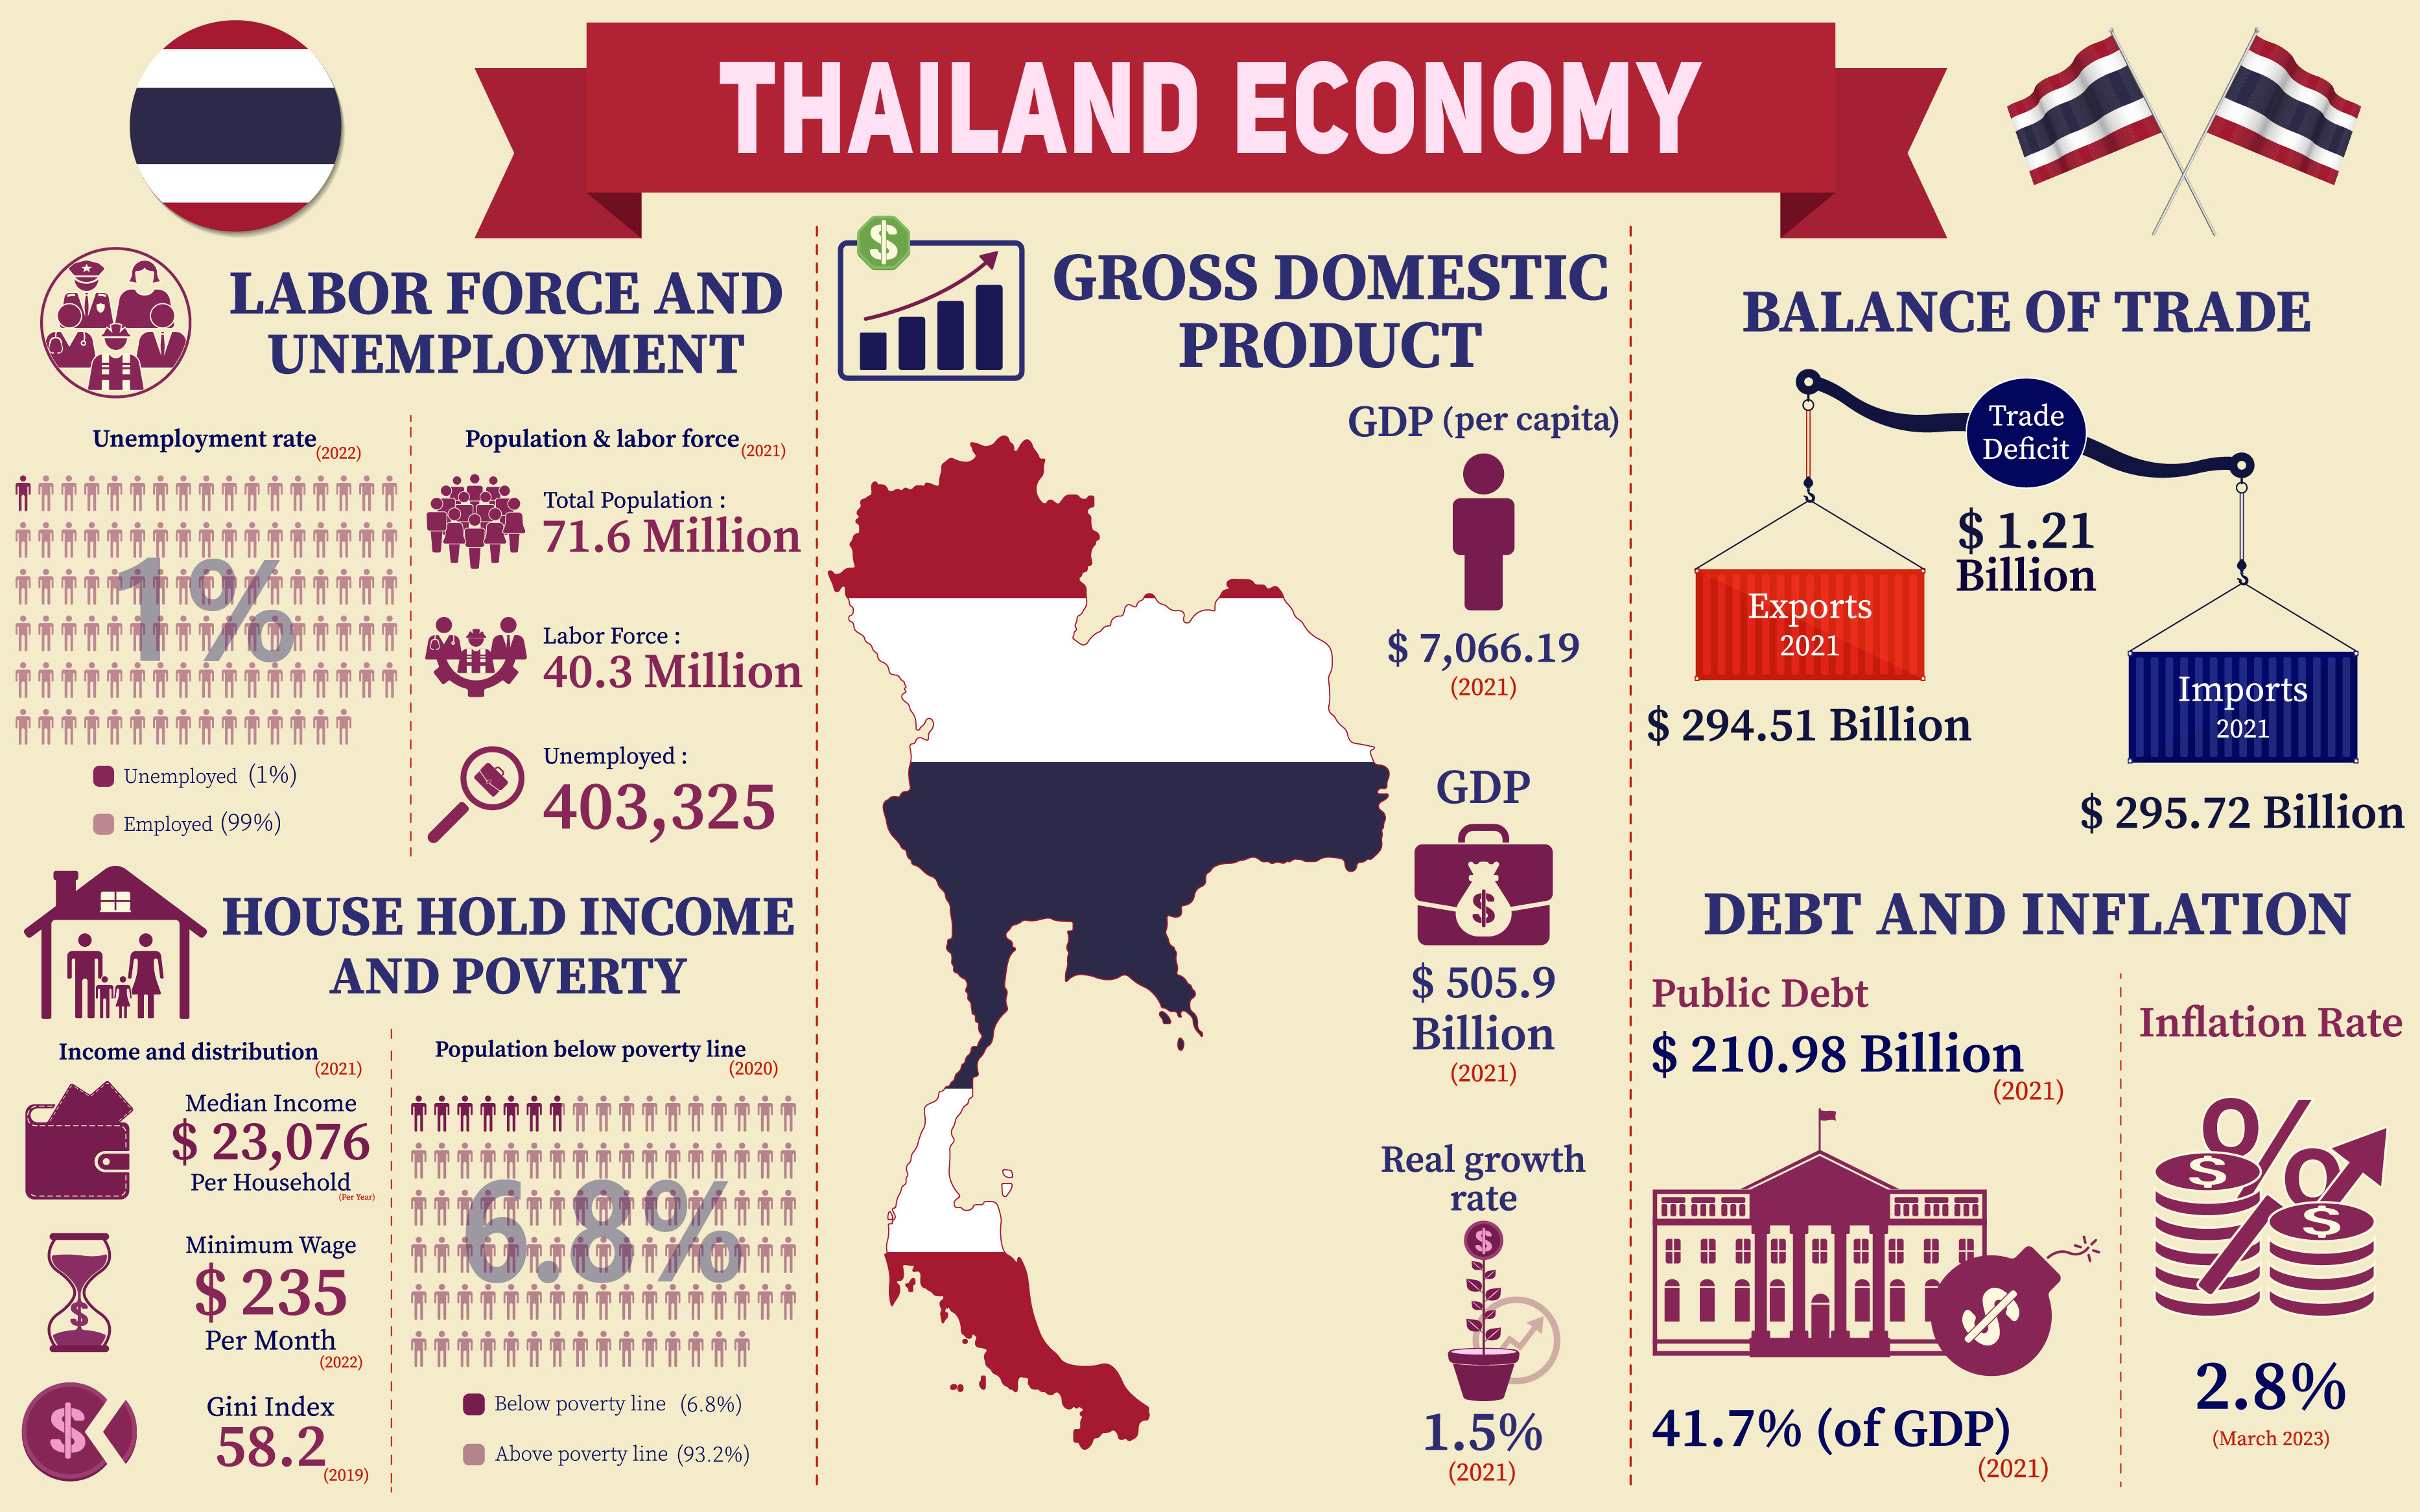
The "lowest net worth Thailand" phenomenon isn’t a uniform experience. It fractures along regional, ethnic, and generational lines. In Isaan, where 40% of households are considered poor by national standards, the average net worth hovers around negative territory—debts to moneylenders or sao thao (local credit cooperatives) often outweigh meager assets. A farmer in Udon Thani might own a 50,000-baht tractor but owe 80,000 baht in loans, leaving their "lowest net worth Thailand" classification untouched by GDP growth. Meanwhile, in Bangkok’s Klong Toey slums, informal waste pickers earn 200–400 baht/day but pay 1,200 baht/month for a 3x4-meter hut—leaving little for education or healthcare. The "lowest net worth Thailand" label also masks a hidden economy. Cash-in-hand jobs—from tuk-tuk drivers to massage parlor workers—account for half of Thailand’s labor force, yet these workers rarely appear in official wealth calculations. A 2023 World Bank report estimated that 60% of Thailand’s poor operate outside formal banking, relying on mobile money or gold pawnshops for liquidity. This exclusion isn’t just a financial blind spot; it’s a policy failure. When the Bank of Thailand raised interest rates in 2022–23, micro-lenders charged 20–30% monthly—turning a 10,000-baht loan into a 120,000-baht debt trap in a year. The "lowest net worth Thailand" trap isn’t just about income; it’s about asset poverty.Historical Background and Evolution
Thailand’s "lowest net worth Thailand" crisis has roots in the 1997 Asian Financial Crisis, which devastated rural economies and forced millions into debt peonage. The government’s response—debt moratoriums and rice subsidies—provided temporary relief, but structural issues persisted. Land reform programs stalled, and the 1999 Constitution failed to guarantee economic rights. By the 2010s, the rise of casual labor platforms (like Grab and Foodpanda) created a new class of "lowest net worth Thailand" workers: gig economy participants with no benefits, no job security, and no path to asset accumulation. The "lowest net worth Thailand" demographic also reflects Thailand’s demographic time bomb. With 20% of the population over 65, elderly households—many in rural areas—rely on pension payments of 500–1,000 baht/month. When combined with healthcare costs (a 300-baht visit can wipe out a week’s budget), their "lowest net worth Thailand" status becomes intergenerational. The 2020 COVID-19 lockdowns exposed this fragility: 1.5 million Thais lost their jobs, and 40% of micro-enterprises (like street food stalls) never reopened. The "lowest net worth Thailand" floor didn’t just dip; it cracked.Core Mechanisms: How It Works
The "lowest net worth Thailand" system operates through three interlocking cycles: debt, exclusion, and informality. Debt begins with agricultural loans—farmers in the north take out 50,000–100,000 baht for seeds or equipment, only to see yields collapse due to drought or pests. When repayment deadlines hit, they borrow from sao thao, which charge 5–10% monthly interest. Within a year, a 50,000-baht loan becomes 80,000 baht. Exclusion follows: without collateral, these households can’t access formal bank loans, so they’re locked into predatory lending. Informality then perpetuates the cycle—80% of "lowest net worth Thailand" workers lack contracts, meaning no unemployment insurance, no severance, and no savings. The "lowest net worth Thailand" trap also thrives on geographic isolation. In the deep south, Malay Muslim communities face discriminatory land policies—their ancestral plots are seized for tourism projects, leaving families with no assets to fall back on. Meanwhile, in Bangkok’s dynamic zones, migrant workers (from Cambodia, Laos, and Myanmar) live in overcrowded dormitories, paying 3,000–5,000 baht/month for a 4-person room. Their "lowest net worth Thailand" status is compounded by language barriers and legal exclusion—many lack work permits, making them targets for wage theft. The system isn’t accidental; it’s designed to keep labor cheap and compliant.Key Benefits and Crucial Impact
On the surface, Thailand’s "lowest net worth Thailand" crisis might seem like a humanitarian issue, but its economic ripple effects are profound. For multinational corporations, it ensures a steady supply of low-wage labor—factories in Rayong pay 10,000–12,000 baht/month (below the 15,000-baht living wage threshold), while tourism-dependent provinces like Phuket rely on underpaid domestic workers. The "lowest net worth Thailand" demographic also fuels consumption—despite their poverty, they spend on cheap credit, mobile data, and instant noodles, propping up conglomerates like CP All and Thai Beverage. Yet the costs are far higher. A 2022 UNDP report estimated that inequality costs Thailand 6–9% of GDP annually in lost productivity, healthcare expenses, and social unrest. The "lowest net worth Thailand" population’s limited purchasing power stifles domestic demand, forcing the economy to rely on export-led growth—a model vulnerable to global shocks. Even government stimulus programs (like the 2020 10,000-baht "Tha Sa-Ba-Tay" cash handout) failed to reach 30% of intended beneficiaries due to biometric verification gaps. The "lowest net worth Thailand" crisis isn’t just a moral failing; it’s an economic drag."You can build all the skyscrapers you want, but if the majority of your people can’t afford to eat three meals a day, your economy is a house of cards." — Kanokwan Manorom, economist and former deputy governor of the Bank of Thailand
Major Advantages
Despite the grim headlines, the "lowest net worth Thailand" demographic exhibits resilience and adaptability that even policymakers overlook:- Informal safety nets: Communities in Isaan practice rotating credit associations (ROSCAs), where members contribute 50–100 baht/week to a shared fund for emergencies—effectively a DIY microfinance system.
- Digital inclusion: Mobile banking (via TrueMoney, PromptPay) allows unbanked workers to send remittances or access 5,000-baht government transfers instantly, bypassing traditional banks.
- Skill diversification: In Chiang Rai, Hmong hill tribes supplement farming with handmade textiles and herbal medicine, creating multiple income streams that insulate them from single-crop failures.
- Barter economies: In rural villages, labor is often exchanged (e.g., 1 day of rice harvesting = 1 day of teaching), reducing cash dependency.
- Cultural capital: Strong family and religious networks provide childcare, funeral support, and mutual aid—services that would cost thousands in urban areas.
Comparative Analysis
| Metric | "Lowest Net Worth Thailand" vs. Global Peers |
|---|---|
| Average Household Net Worth (2023 est.) | Thailand: Negative to 50,000 baht (rural) / 100,000–300,000 baht (urban informal); Vietnam: 80,000–200,000 VND (similar rural poverty but higher urban wages); Indonesia: 5–10M IDR (higher due to microfinance growth). |
| Debt-to-Income Ratio | Thailand: 30–50% (agricultural loans); Philippines: 20–40% (consumer debt); Cambodia: 60–80% (microloan traps). Thailand’s ratio is moderate but persistent due to sao thao dominance. |
| Informal Labor Share | Thailand: ~50% of workforce; India: 80%+; Brazil: 40%. Thailand’s lower informality rate masks higher underemployment—many "formal" jobs pay minimum wage. |
| Government Aid Penetration | Thailand: 60–70% reach (due to ID gaps); Malaysia: 85%+ (biometric success); Laos: 40% (logistical challenges). Thailand’s system is better than neighbors but still flawed. |
Future Trends and Innovations
The "lowest net worth Thailand" landscape is evolving, but not in ways that benefit the poor. AI-driven gig platforms (like Thailand’s "JobThai") promise algorithm-matched jobs, but wage compression is likely—companies will automate low-skill roles (e.g., tea stall orders, factory sorting) while keeping pay flat. Meanwhile, carbon credit schemes in Isaan may offer new income streams for farmers, but land grabs could displace lowest net worth Thailand households before they benefit. The real innovation lies in community-led solutions. In Sukhothai, a blockchain-based microloan cooperative (backed by MIT researchers) allows zero-interest loans for 5,000–20,000 baht, cutting out sao thao middlemen. Similarly, Bangkok’s "Bank of the Poor"—a people’s bank—offers savings accounts with 3% interest and emergency microloans to unbanked workers. If scaled, these models could disrupt the "lowest net worth Thailand" cycle. Yet political will remains the biggest hurdle. Without land reform, wage indexing, and financial inclusion laws, even the best tech solutions will only scratch the surface.
Conclusion
The "lowest net worth Thailand" crisis isn’t a temporary blip; it’s a structural feature of an economy built on cheap labor and debt dependency. The numbers tell one story—10% of Thais in poverty, 50% in precarious work—but the human cost is far greater. A single medical emergency can erase a family’s savings. A drought season can push a farmer into generational debt. The "lowest net worth Thailand" label isn’t just about how little people have; it’s about how little agency they possess to change their fate. The good news? Thailand has the tools to fix this. Strong social protection floors (like universal healthcare and cash transfers) work in Brazil and South Korea. Progressive taxation on the ultra-rich (where the top 0.1% control 20% of wealth) could fund asset-building programs. And cooperative models (like Denmark’s worker-owned farms) could redistribute land and capital to those who need it. The question isn’t whether Thailand can afford these changes—it’s whether it can afford not to.Comprehensive FAQs
Q: What’s the single biggest factor keeping Thailand’s "lowest net worth" households trapped?
The debt-informality loop is the primary trap. Agricultural loans, sao thao interest rates (often 20–30% monthly), and informal employment create a cycle where savings are impossible, and assets are nonexistent. Even when wages rise, rent and healthcare costs absorb gains, leaving net worth stagnant.
Q: How does Thailand’s "lowest net worth" population compare to other ASEAN countries?
Thailand’s "lowest net worth" demographic is less extreme than Cambodia or Laos (where 70–80% of rural households have negative net worth) but more entrenched than Vietnam or Malaysia. The key difference is Thailand’s urban-rural divide—while Bangkok’s poor may earn 15,000–20,000 baht/month, Isaan farmers often live on 5,000–8,000 baht/month, creating regional wealth chasms within the same country.
Q: Are there any success stories of "lowest net worth" households breaking the cycle?
Yes, but they’re rare and localized. In Trang Province, a seaweed farming cooperative helped 500 households escape debt by pooling resources and selling directly to export markets. In Chiang Mai, digital nomad visas have indirectly boosted local service workers (e.g., cooks, drivers), but wage growth hasn’t trickled down to the true "lowest net worth" demographic. Most success stories require external support—whether NGO microgrants or family remittances.
Q: Why don’t more "lowest net worth" Thais access government aid?
Three barriers dominate: 1) ID verification gaps—20% of rural poor lack household registration (tabu); 2) bureaucratic hurdles—some provinces require multiple in-person visits to access 30-baht rice subsidies; 3) stigma—many fear being labeled "lazy" or "unworthy" if they apply for aid. Migrant workers face additional exclusion—even legal residents often lack bank accounts to receive digital transfers.
Q: Could Thailand’s gig economy (Grab, Foodpanda) help lift people out of "lowest net worth" status?
Unlikely in the short term. While gig work provides flexible income, wages are stagnant (average 150–250 baht/hour for delivery drivers) and costs (bike maintenance, fuel) eat profits. A 2023 study by Chulalongkorn University found that 70% of gig workers in Bangkok earn less than minimum wage after expenses. The real risk is wage suppression—companies use algorithm-driven bonuses to keep base pay low. For true upward mobility, gig workers would need unionization, profit-sharing, or asset-building (e.g., owning delivery bikes outright).
Q: What’s the most effective policy to address "lowest net worth Thailand" households?
Land reform + financial inclusion is the most impactful combo. Redistributing idle land (e.g., government-owned plots, corporate unused acreage) to debt-ridden farmers could instantly boost net worth. Pair this with community banks (like Bangkok’s "Bank of the Poor") to offer zero-interest loans and savings accounts. Wage indexing (tying minimum wage to inflation + productivity) and universal healthcare would reduce emergency debt. Without structural changes, band-aid solutions (like cash handouts) will only delay the crisis.
