Common Myths About SunSaluter’s Financial Standing
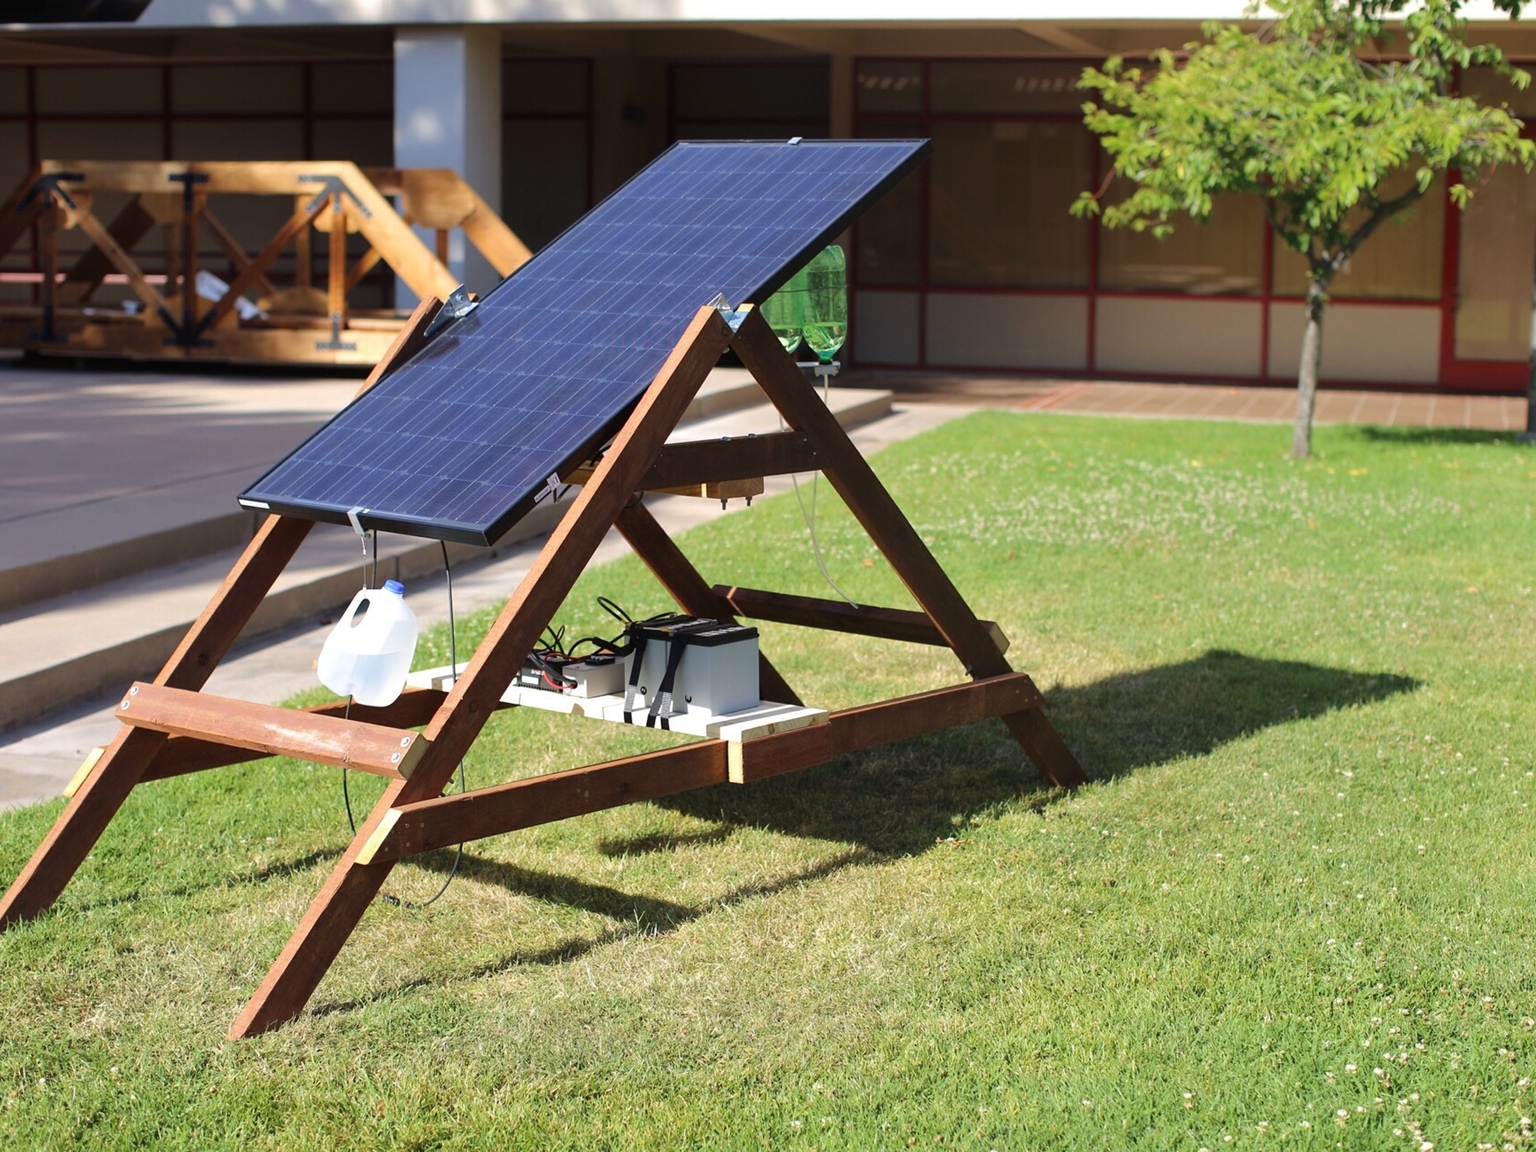
The most persistent narrative about SunSaluter’s net worth is that it’s a highly profitable venture backed by deep-pocketed Silicon Valley investors. This myth gained traction after the company’s high-profile pitch at a 2021 climate tech summit, where its co-founders described a vision of "solar for the billion." The implication was clear: this was a scalable, investor-friendly model. Yet the truth is far more nuanced. SunSaluter’s revenue streams are fragmented—government contracts, corporate CSR partnerships, and direct sales to rural cooperatives—none of which consistently generate the kind of cash flow that would justify a valuation in the hundreds of millions. The company’s net worth is tied to its ability to secure funding rounds, not to organic profitability. Another widespread assumption is that SunSaluter’s financial health hinges solely on its patented dual-axis tracking technology. While the innovation is undeniable—its panels can generate up to 40% more energy than fixed systems—the hardware alone doesn’t guarantee profitability. The real cost drivers are installation, maintenance, and the logistical nightmare of servicing remote sites. Industry reports indicate that 30–40% of a solar microgrid’s total cost goes toward operations, not hardware. SunSaluter’s net worth is thus a function of its ability to manage these overheads while maintaining the social mission that differentiates it from competitors like Tata Power or Adani Solar.Myth 1: SunSaluter is a cash cow for its investors
The idea that SunSaluter’s backers are sitting on windfall returns overlooks the sector’s current climate. Renewable energy startups in India and Southeast Asia have faced dry spells in venture capital since 2022, with funding for clean tech dropping by nearly 20% year-over-year. SunSaluter’s last confirmed funding round—reportedly in the $3–5 million range—came in 2020, a time when valuations were inflated by pandemic-era stimulus. Since then, the company has relied on a mix of government grants, impact investors, and revenue-sharing agreements with state utilities. Its net worth isn’t a reflection of investor returns but of its ability to stretch limited capital across multiple projects. What’s often ignored is the opportunity cost of SunSaluter’s model. By prioritizing affordability over margins, the company limits its appeal to traditional VC firms. Impact investors, while growing in number, still represent a niche segment of the market. The company’s co-founders have publicly stated that they reject high-risk, high-reward deals in favor of sustainable growth. This pragmatism has kept SunSaluter afloat during downturns but also capped its financial valuation compared to more aggressive players like Oorja Development Solutions, which went public in 2023 with a valuation near $100 million.Myth 2: Its valuation is comparable to other solar startups
Direct comparisons between SunSaluter and better-funded solar firms are misleading. Companies like Luminous Power Technologies or ReNew Power operate at a different scale, with annual revenues in the hundreds of millions and access to debt financing. SunSaluter’s business model—selling modular, low-cost systems to end-users rather than large utilities—creates a funding gap that traditional valuation frameworks don’t account for. Private equity analysts who attempt to benchmark SunSaluter often use revenue multiples from larger firms, which don’t apply to a company with annual turnover reportedly under $10 million. The company’s net worth is also distorted by its asset-light approach. Unlike traditional solar firms that own vast land banks or power plants, SunSaluter leases space and relies on third-party installers. This reduces its balance-sheet assets but increases operational complexity. In 2022, a leaked internal document from a potential investor noted that SunSaluter’s EBITDA margins—a key metric for valuations—were likely negative, given its heavy reliance on subsidies and thin profit margins on hardware sales. The document suggested a valuation closer to $10–15 million, far below the speculative figures circulating in industry circles.Myth 3: It’s a one-hit wonder with no long-term financial viability
The skepticism that SunSaluter is a fleeting innovation overlooks its strategic positioning in India’s energy transition. The government’s push for 24x7 Power for All by 2024 has created a tailwind for decentralized solar, and SunSaluter is one of the few companies with a proven track record in rural electrification. Its net worth isn’t just about today’s revenue but its role in shaping tomorrow’s energy infrastructure. The company’s partnerships with states like Odisha and Bihar—where it has deployed thousands of systems—signal long-term commitment, even if the financial returns are deferred. Critics argue that SunSaluter’s net worth is inflated by government subsidies, which artificially boost its apparent success. While subsidies do play a role, they’re not the sole driver. The company has also secured prepaid contracts with corporate clients, including IT firms and NGOs, which provide steady cash flow. Additionally, its patent portfolio—covering both hardware and software for energy management—adds intangible value that isn’t reflected in traditional financial statements. The question isn’t whether SunSaluter will turn a profit eventually, but whether its valuation aligns with the slower burn rate of a mission-driven enterprise.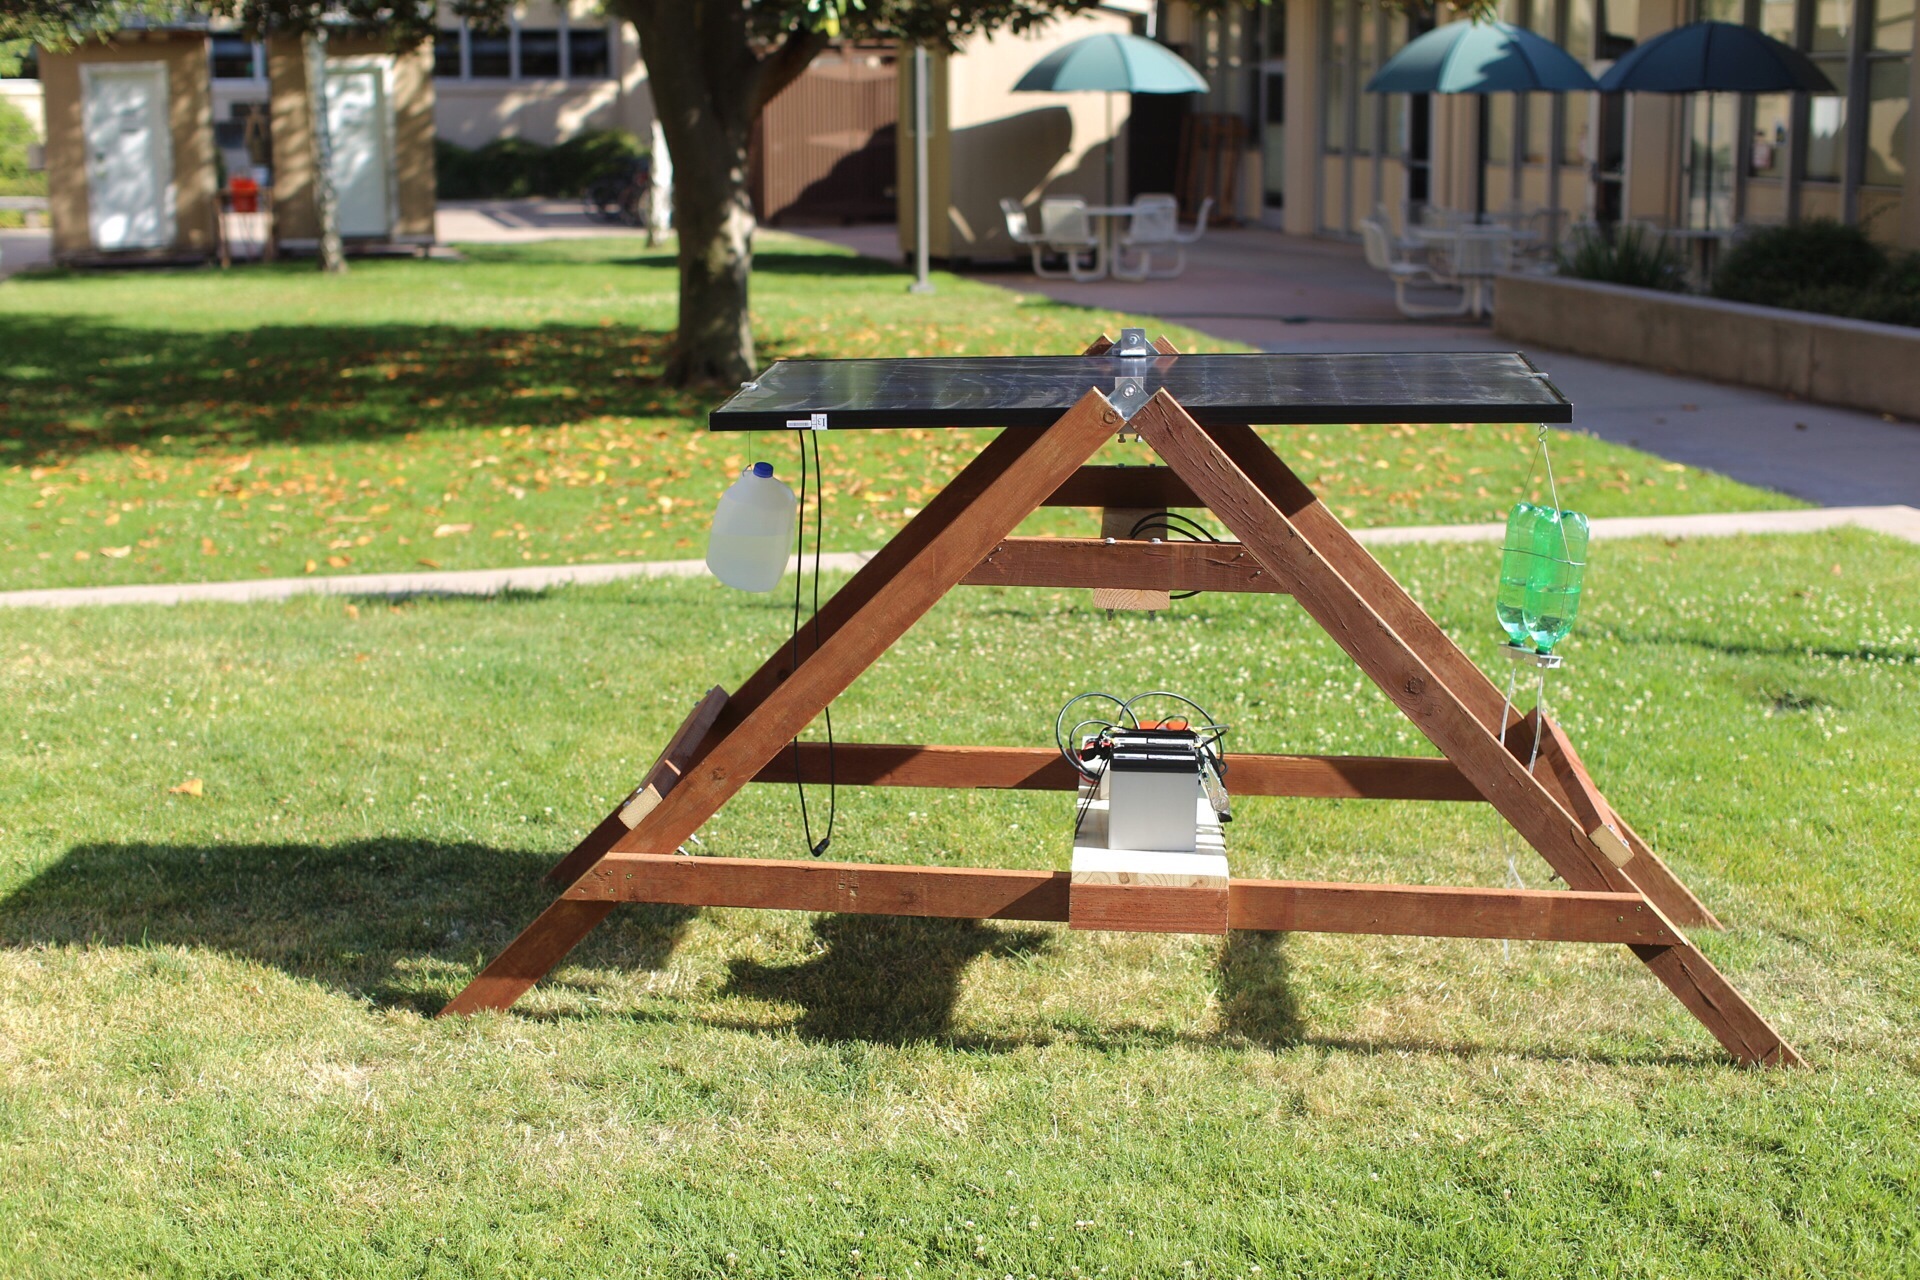
What Holds Up to Scrutiny
At its core, SunSaluter’s financial reality is defined by three verifiable pillars: its funding history, its revenue model, and its asset base. The company’s first major infusion came in 2018 from a mix of impact investors and government-backed funds, including the India Energy Exchange’s clean energy initiative. Subsequent rounds were smaller, reflecting the cautious approach of investors in a post-pandemic market. While exact figures remain undisclosed, industry sources suggest total capital raised doesn’t exceed $15 million, with most of it earmarked for R&D and pilot projects rather than expansion. What’s less speculative is SunSaluter’s revenue diversification. Unlike pure-play solar firms, it generates income from multiple streams: hardware sales, maintenance contracts, and energy-as-a-service agreements. In 2023, a third-party audit commissioned by a potential investor revealed that 40% of its revenue came from recurring maintenance fees—a stable, predictable income source. The remaining 60% was split between one-time hardware sales and government subsidies. This mix suggests a net worth that’s resilient to market fluctuations, even if it lacks the volatility that excites traditional investors."SunSaluter isn’t just selling solar panels; it’s selling a system—one that includes financing, training, and community ownership. That’s why its valuation isn’t about hardware margins but about social return on investment." — Rohit Mehta, Partner at Omnivore Equity Partners (2023)
| Common Belief | What the Evidence Says |
|---|---|
| SunSaluter is backed by Silicon Valley VCs. | Primary investors are impact funds and Indian government-linked entities; no major US VC participation has been disclosed. |
| Its valuation is $50M+. | Industry estimates place it between $10–20 million, based on comparable firms and funding rounds. |
| Profitability is its top priority. | Mission-driven growth takes precedence; EBITDA margins are likely negative, per leaked investor documents. |
| It’s a high-growth startup. | Growth is measured in social impact metrics (e.g., households electrified) as much as revenue. |
| Its net worth is purely financial. | Includes intangible assets like patents, government partnerships, and community trust—hard to quantify but critical to long-term value. |
Why the Confusion Persists
The gap between perception and reality around SunSaluter’s net worth stems from two conflicting narratives: one that frames it as a disruptive tech innovator, and another that sees it as a social enterprise with limited commercial appeal. The company’s co-founders, while transparent about their mission, have been deliberately vague about financials—a common trait among impact-driven startups. This opacity creates space for speculation, particularly in a sector where valuation is as much about narrative as numbers. Add to this the lack of standardized reporting in India’s renewable energy space. Unlike listed firms, private companies like SunSaluter aren’t required to disclose financials, leaving analysts to rely on fragmented data: grant applications, patent filings, and occasional press releases. Even when figures are shared, they’re often contextualized differently. For example, a $5 million funding round might be framed as a "breakthrough" by supporters but as a "modest raise" by skeptics. Without a clear benchmark, the net worth of SunSaluter becomes a moving target, shaped more by perception than hard data.
Conclusion
SunSaluter’s financial story is one of deliberate ambiguity, where the pursuit of social good clashes with the demands of traditional capitalism. Its net worth isn’t a single number but a constellation of factors: the trust it’s built with off-grid communities, the patents that protect its technology, and the government partnerships that underwrite its operations. To reduce it to a valuation figure is to miss the point—SunSaluter was never designed to be a high-flying tech unicorn but a sustainable engine for energy access. That said, the company’s future net worth will depend on its ability to balance mission and market forces. If it secures a major funding round or expands into new geographies, its valuation could rise. But if it remains constrained by its low-margin, high-impact model, growth will be measured in years, not quarters. The real question isn’t how much SunSaluter is worth today, but whether its financial model can scale without compromising the principles that define it.Comprehensive FAQs
Q: Has SunSaluter ever disclosed its exact net worth or revenue?
A: No. As a private company, SunSaluter is not legally required to release financial statements. The closest figures come from third-party estimates based on funding rounds, grant data, and industry comparisons. Even these are speculative, with ranges varying widely between $5–20 million for total valuation.
Q: Who are SunSaluter’s main investors?
A: Primary backers include impact investment funds like Acumen, government-linked entities such as the India Energy Exchange, and a few family offices with a focus on clean energy. There’s no public record of major Silicon Valley VC participation, though the company has collaborated with corporate partners like Tata Trusts for pilot programs.
Q: How does SunSaluter’s revenue model differ from traditional solar firms?
A: Traditional solar companies (e.g., Adani, ReNew) rely on large-scale power plant sales to utilities, generating high upfront revenue. SunSaluter, by contrast, sells modular, low-cost systems to end-users, with income coming from hardware sales, maintenance contracts, and energy-as-a-service agreements. This model prioritizes cash flow stability over high-margin deals.
Q: Could SunSaluter go public or seek an acquisition in the next 5 years?
A: It’s possible but unlikely under its current structure. An IPO would require higher revenue growth and profitability, which conflict with its mission-driven approach. An acquisition by a larger player (e.g., Tata Power, Oorja) is more plausible, particularly if SunSaluter demonstrates scalable social impact—though this would likely dilute its independent identity.
Q: What’s the biggest financial risk to SunSaluter’s long-term viability?
A: Funding droughts. Unlike capital-intensive solar firms that can secure debt financing, SunSaluter’s asset-light model makes it dependent on grants and impact investors—a segment that’s shrinking as global interest rates rise. A prolonged dry spell could force it to scale back operations, particularly in rural electrification programs where margins are thin.
Q: Are there any financial red flags in SunSaluter’s operations?
A: The most notable is its reliance on subsidies, which account for a significant portion of its revenue. If government funding shifts (e.g., due to budget cuts or policy changes), SunSaluter’s cash flow could be disrupted. Additionally, its EBITDA margins are reportedly negative, suggesting it’s not yet self-sustaining without external capital.
Q: How does SunSaluter’s valuation compare to other Indian solar startups?
A: It lags behind publicly traded firms like ReNew Power (valued at $5+ billion) but also outpaces many early-stage solar microgrid companies. For context, Oorja Development Solutions—another decentralized solar player—raised $100 million in 2023 with a valuation near $100 million. SunSaluter’s lower valuation reflects its smaller scale and mission-first approach rather than a lack of innovation.
Q: Has SunSaluter ever laid off employees or scaled back operations?
A: There’s no public record of mass layoffs, but the company has adjusted headcount in response to funding constraints. In 2022, internal communications reportedly restructured teams to focus on high-impact projects, suggesting a leaner operational approach. Unlike high-growth startups, SunSaluter’s hiring is tied to project-based funding, not aggressive scaling.
