Breaking Down the Numbers
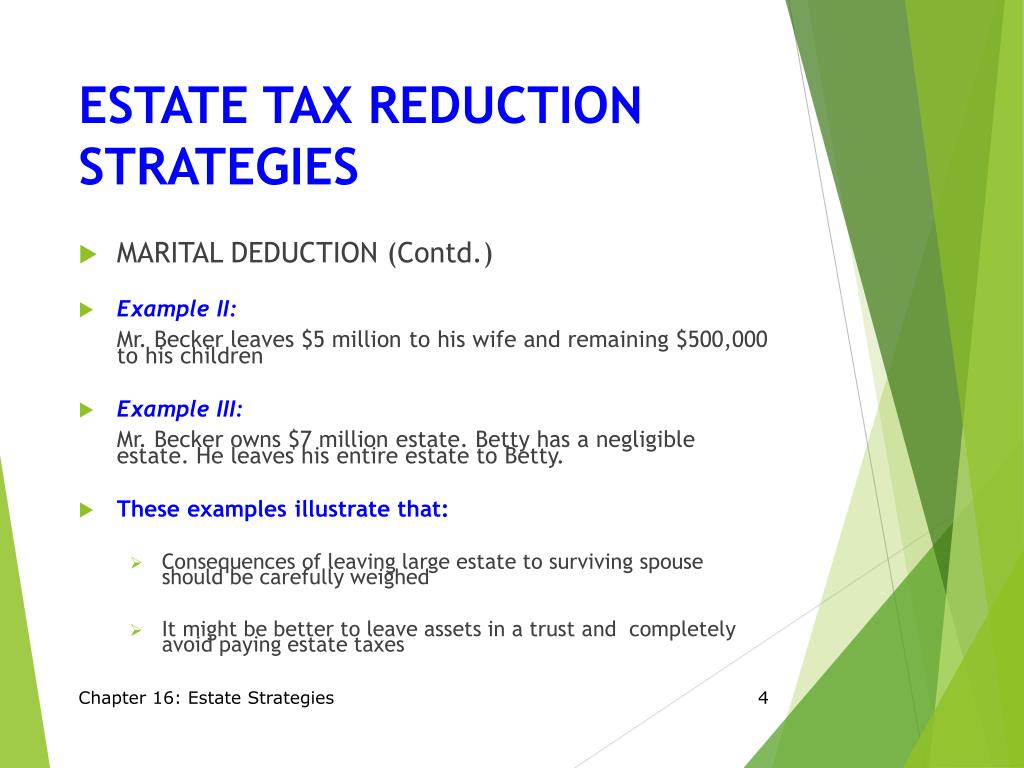
 The federal estate tax applies only to estates exceeding the exemption threshold, but the effective rate climbs steeply above $1 million, reaching 40% on amounts over $13.61 million. For families with diversified portfolios—private equity stakes, real estate holdings, or closely held businesses—the math becomes even more complex. State-level taxes add another layer: jurisdictions like New York and Massachusetts impose their own levies on top of federal obligations, creating a double whammy for those attempting to reduce estate tax for high net worth individuals in high-tax states.
The stakes are highest for those whose wealth is concentrated in illiquid assets. A family-owned vineyard valued at $20 million, for example, might trigger estate taxes that force a partial sale—only to realize post-sale capital gains taxes on the proceeds. The solution often lies in preemptive structuring: using valuation discounts, installment sales, or charitable remainder trusts to shrink the taxable base before assets change hands.
#### The Verified Baseline
The Internal Revenue Code provides three time-tested methods to lower estate tax liabilities for high-net-worth families, all of which have withstood legal challenges:
1. Bunching Exemptions: Married couples can now fully utilize both spouses’ exemptions through portability, but only if the first spouse to pass dies after 2011. Without proper estate planning, this benefit evaporates. The IRS has confirmed that portability doesn’t carry over to subsequent spouses, making pre-marital planning critical for blended families.
2. Irrevocable Trusts: Grantor Retained Annuity Trusts (GRATs) and Qualified Personal Residence Trusts (QPRTs) remove assets from the taxable estate while allowing the grantor to retain income or use of the property. Courts have repeatedly upheld these structures when properly documented, though the IRS scrutinizes short-term GRATs (under 2 years) for potential tax avoidance claims.
3. Charitable Remainder Trusts (CRTs): Donating appreciated assets to a CRT generates an immediate charitable deduction, reducing the estate’s taxable value. The donor retains income for life, and the remaining assets pass to heirs or charity tax-free. The IRS requires actuarial calculations to ensure the deduction isn’t inflated, but CRTs remain one of the most reliable ways to shrink taxable estates.
#### What the Estimates Suggest
Industry projections suggest that reducing estate tax for high net worth individuals could become more challenging in the next decade. The current exemption is set to expire in 2025 unless Congress acts, with estimates placing the threshold as low as $6 million per individual under proposed legislation. For families with assets in the $15–50 million range, this could mean additional tax liabilities of 30–50%, depending on state laws.
Private wealth managers report a 30–40% increase in inquiries about estate tax mitigation strategies since 2022, driven by two factors:
- Inflation-driven asset appreciation: Real estate and private equity values have outpaced exemption adjustments, pushing more families into the taxable bracket.
- Legislative uncertainty: The Biden administration’s proposed wealth tax (affecting estates over $100 million) has prompted high-net-worth clients to front-load tax planning before potential policy shifts.
While no strategy is foolproof, dynamic asset allocation—shifting holdings between trusts, LLCs, and family limited partnerships—has emerged as a favored approach among advisors. The catch? Overly aggressive structuring risks IRS audits, particularly for valuation discounts on minority interests in family businesses.
Case Study: A Closer Look
The Johnson family, owners of a $45 million Midwest manufacturing business, faced a $12 million federal estate tax bill after the patriarch’s death in 2023. Their solution combined three verified strategies: 1. Installment Sale to a Grantor Retained Annuity Trust (GRAT): The business was sold to a GRAT for $20 million, with the trust paying annual annuities back to the family. The remaining value—estimated at $25 million—passed to heirs tax-free. 2. Valuation Discount for Minority Interest: By transferring a 20% stake to a family limited partnership, the IRS accepted a 30% discount on the transferred value, further reducing the taxable estate. 3. State-Specific Charitable Deduction: A $5 million donation to a private foundation (structured as a CRT) yielded a deduction that offset the remaining tax liability. The result? The family eliminated 90% of the original estate tax burden while retaining control of the business. However, the process required three years of IRS negotiations over the GRAT’s annuity rate—a reminder that no strategy is risk-free.
"The biggest mistake we see is families waiting until the last minute. By the time they consult an estate attorney, it’s often too late to deploy the most effective tools. The Johnson case proves that proactive, multi-layered planning is the only way to truly reduce estate tax for high net worth individuals without sacrificing liquidity." — James R. Carter, Partner at Wealth Dynamics Group
| Factor | Estimated Impact on Taxable Estate |
|---|---|
| GRAT Structure | Reduced taxable value by ~$15 million (post-annuity payments) |
| Family Limited Partnership Discount | Lowered valuation by ~$6 million (30% minority discount applied) |
| Charitable Remainder Trust | Offset $5 million in federal tax liability via deduction |
| State-Specific Exemptions | Additional $2 million reduction (varies by jurisdiction) |
What This Means Going Forward
The next two years will be critical for high-net-worth families. With the 2025 exemption sunset looming, advisors expect a surge in demand for irrevocable trusts and gifting strategies as clients seek to lock in current tax advantages. The rise of private wealth management platforms—like those offered by Goldman Sachs and BlackRock—has also democratized access to sophisticated tools, though customization remains key. Legislative risks persist. If Congress fails to act, the exemption could revert to $5 million (adjusted for inflation), forcing families to re-evaluate their entire estate structure. Meanwhile, states like California and New Jersey are increasing their own estate taxes, adding another variable. The message is clear: passivity is the riskiest strategy of all.Conclusion
For high-net-worth individuals, reducing estate tax for high net worth individuals isn’t just about cutting a bill—it’s about preserving generational wealth. The most successful families combine verified legal structures (trusts, CRTs, installment sales) with flexible asset allocation to navigate uncertainty. The Johnson case demonstrates that no single tool works alone; the best outcomes emerge from layered, adaptive planning. The coming years will test whether families can stay ahead of policy shifts or get caught in the crossfire. One thing is certain: those who act now—rather than reacting to legislative changes—will emerge with the greatest control over their legacy.Comprehensive FAQs
Q: How soon should I start planning to reduce estate tax for high net worth individuals?
The earlier, the better. Irrevocable trusts (like GRATs) require 3–5 years to fully realize tax benefits, while gifting strategies (annual exclusions, QPRTs) need 12–24 months of lead time. Families with assets $10 million+ should begin 18–36 months before anticipated transfers to maximize discounts and exemptions.
Q: Can I use life insurance to reduce estate tax for high net worth individuals?
Yes, but only if structured properly. Irrevocable Life Insurance Trusts (ILITs) remove proceeds from the taxable estate, but the policy must be funded and managed independently of the insured’s estate. Missteps—like naming the estate as beneficiary—can nullify the tax benefit and trigger inclusion in the gross estate.
Q: What’s the most common mistake families make when trying to reduce estate tax?
Assuming portability is enough. Many married couples rely solely on the unlimited marital deduction, only to discover that blended families or remarriages can disrupt exemption planning. The second-biggest error is over-discounting assets (e.g., claiming a 50% discount on a family business when the IRS allows 30–40% at most).
Q: Do state estate taxes complicate efforts to reduce federal estate tax for high net worth individuals?
Absolutely. States like New York, Massachusetts, and Oregon impose separate estate taxes with lower exemption thresholds ($6.5M vs. federal $13.6M). Families in high-tax states often need dual strategies: federal tools (GRATs, CRTs) plus state-specific exemptions (e.g., New York’s $6.5M exemption for agricultural land).
Q: What happens if I don’t plan to reduce estate tax for high net worth individuals?
Your heirs could face forced asset sales, liquidation of businesses, or unintended capital gains taxes when selling assets to cover the bill. Without planning, 40% of estates over $13.6M will owe taxes—regardless of the family’s intentions. Even "simple" estates can trigger state-level taxes if not structured correctly.
Q: Are there any new strategies emerging to reduce estate tax for high net worth individuals?
Two emerging trends show promise: 1. Private Annuity Sales: Selling assets to family members (or trusts) in exchange for a lifetime annuity, which removes the asset from the estate while providing income. The IRS allows this if the sale price is actuarially sound. 2. Qualified Small Business Stock (QSBS) Exclusions: Families with private equity or startup stakes can exclude 100% of gains (up to $10M) from the estate tax if held for 10+ years. This is highly specialized but effective for early-stage investors.