Common Myths About Tax Planning for High Net-Worth Individuals
The first myth is that tax planning for high net-worth individuals is a one-time exercise. Many assume that once a structure is in place—whether through trusts, offshore entities, or domestic holding companies—the work is done. Reality dictates otherwise. Tax laws evolve, jurisdictions shift their policies, and personal circumstances change. A strategy effective five years ago may now trigger unexpected liabilities or fail to optimize for current goals. For instance, the rise of digital nomad visas and remote work has complicated residency-based tax obligations, making static planning obsolete. Another pervasive belief is that tax planning for HNWIs is synonymous with aggressive tax avoidance. This conflates legal optimization with illegal evasion, deterring many from exploring legitimate structures like tax-efficient investment vehicles or charitable giving frameworks. The IRS and global tax authorities have sharpened their focus on substance over form, but that doesn’t mean HNWIs should shy away from structuring their affairs. The key lies in transparency and compliance—areas where professional guidance becomes indispensable.Myth 1: "Offshore Accounts Are the Only Way to Reduce Taxes"
The assumption that tax planning for high net-worth individuals requires offshore structures persists, fueled by high-profile cases and sensationalized media coverage. While offshore accounts can play a role—particularly for diversification or asset protection—they are not a universal solution. Domestic strategies, such as qualified small business stock (QSBS) exemptions or municipal bond portfolios, often deliver comparable benefits without the compliance burdens of foreign jurisdictions. The Foreign Account Tax Compliance Act (FATCA) and Common Reporting Standard (CRS) have further narrowed the advantages of secrecy, shifting the focus to legal structuring rather than evasion. Moreover, the cost of maintaining offshore entities—legal fees, annual reporting, and potential double taxation risks—can outweigh the benefits. For HNWIs with U.S. ties, the Foreign Earned Income Exclusion (FEIE) or Foreign Tax Credit (FTC) may offer more straightforward paths to tax efficiency. The lesson? Offshore is a tool, not a default.Myth 2: "Trusts Are Only for the Ultra-Wealthy"
Trusts are often portrayed as the domain of billionaires, but tax planning for high net-worth individuals—even those with net worths in the $5 million to $50 million range—can benefit from their flexibility. Irrevocable life insurance trusts (ILITs) or grantor retained annuity trusts (GRATs) are commonly used to reduce estate taxes or transfer wealth efficiently. The misconception stems from the perception that trusts require excessive complexity or upfront costs. In reality, a revocable living trust can simplify estate administration and avoid probate for families with assets worth as little as $1 million, depending on the jurisdiction. The real barrier isn’t wealth but education. Many HNWIs delay exploring trusts due to confusion about control, costs, or perceived rigidity. Yet, modern trust structures—such as discretionary trusts or dynasty trusts—offer granular control over distributions, creditor protection, and even philanthropic goals. The key is tailoring the trust to specific objectives, not assuming it’s only for the ultra-wealthy.Myth 3: "Tax Planning Starts at a Certain Net Worth Threshold"
Some believe tax planning for high net-worth individuals is only relevant once assets exceed a certain benchmark—often tied to estate tax thresholds or investment income brackets. This mindset ignores the compounding effect of tax efficiency over time. For example, a family with $3 million in investable assets might benefit from tax-lot accounting strategies to defer capital gains, even if they’re not yet subject to the 3.8% net investment income tax (NIIT). Similarly, structuring business holdings into an S-corporation or limited liability company (LLC) can provide immediate pass-through tax advantages, regardless of total net worth. The earlier HNWIs integrate tax-aware strategies—such as tax-advantaged retirement accounts or donor-advised funds (DAFs)—the more they can leverage time and market fluctuations to their advantage. Procrastination isn’t a luxury; it’s a missed opportunity to optimize cash flow and preserve wealth.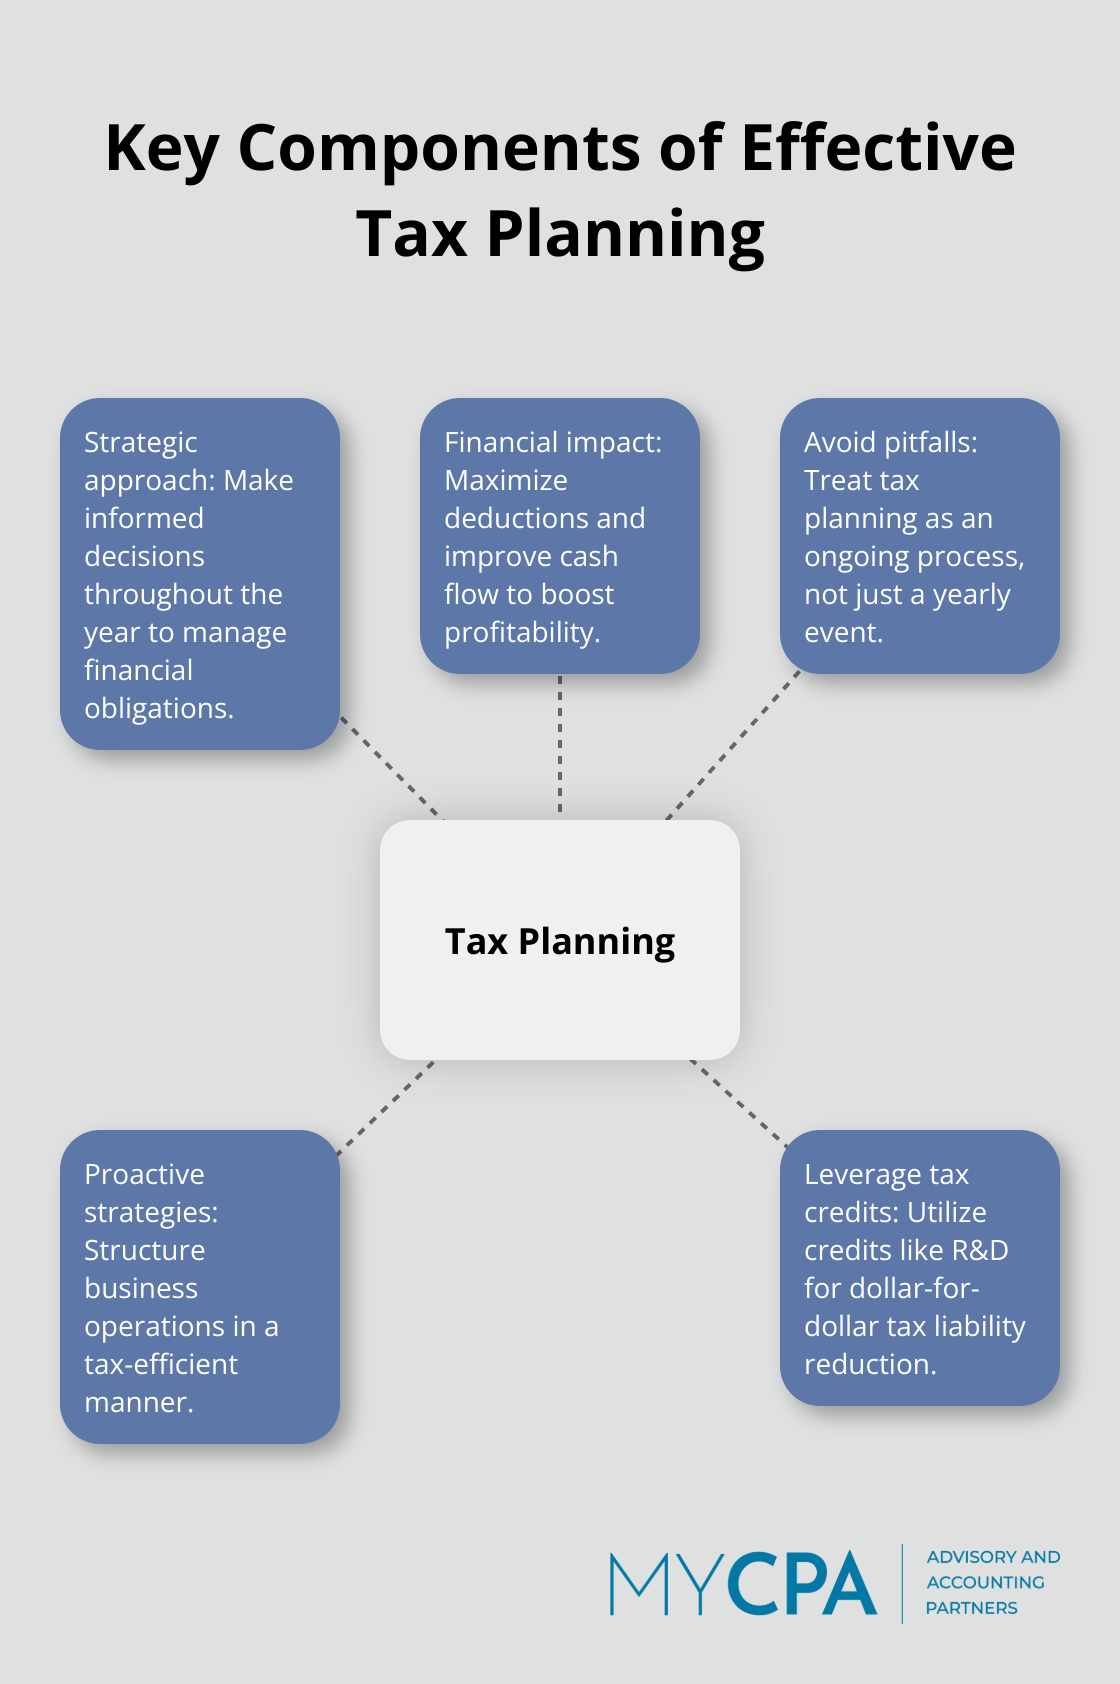
What Holds Up to Scrutiny
At the core of effective tax planning for high net-worth individuals lies a few verifiable principles. The first is diversification of taxable income sources. HNWIs with concentrated holdings—whether in private equity, real estate, or a single public stock—face disproportionate risk from market volatility and tax events. Structuring investments across long-term capital gains (LTCG) buckets, ordinary income, and tax-exempt municipal bonds can smooth out liability spikes. The second principle is jurisdictional arbitrage, where residency, citizenship, and entity structuring are aligned to minimize double taxation. For example, a U.S. citizen residing in Portugal’s Non-Habitual Resident (NHR) program can benefit from a 10-year tax holiday on foreign income, provided compliance requirements are met. What separates speculation from strategy is data-driven decision-making. HNWIs who collaborate with tax attorneys, wealth managers, and cross-border accountants can model scenarios—such as the impact of Section 965 transition tax on repatriated foreign earnings or the step-up in basis at death—to anticipate outcomes. The evidence shows that those who treat tax planning as an ongoing discipline, not a transactional exercise, achieve 20–30% higher after-tax returns over a decade, according to industry estimates."Tax planning for high net-worth individuals isn’t about beating the system; it’s about aligning your financial architecture with the system’s rules—then bending them to your advantage within the guardrails." — David Williams, Partner at Withers Worldwide
| Common Belief | What the Evidence Says |
|---|---|
| Offshore structures are the best way to hide wealth. | FATCA and CRS have made secrecy impractical; legal structuring (e.g., Puerto Rico Act 60) now offers clearer benefits. |
| Trusts are too expensive for most HNWIs. | Revocable trusts cost $1,500–$5,000 to set up; irrevocable trusts may provide $1M+ in estate tax savings over a lifetime. |
| Tax planning is only for end-of-year filings. | Proactive HNWIs adjust structures quarterly to capitalize on LTCG harvesting, charitable deductions, and foreign tax credits. |
| Higher income means higher tax rates are inevitable. | Strategic use of tax-deferred accounts (e.g., 401(k), HSAs) and entity structuring (e.g., LLCs) can cap rates at 20–28% for long-term gains. |
Why the Confusion Persists
The persistence of myths in tax planning for high net-worth individuals stems from two factors: information asymmetry and behavioral biases. HNWIs often rely on general financial advisors who lack deep tax expertise, or they defer to accountants who prioritize compliance over optimization. The result is a gap where opportunity costs—missed deductions, inefficient structures, or delayed estate planning—erode wealth over time. Behavioral biases, such as loss aversion (holding onto underperforming assets to avoid realizing losses) or overconfidence (assuming past strategies will suffice), further cloud judgment. The second factor is the fragmented nature of tax advice. No single professional—whether a CPA, estate attorney, or wealth manager—can master all facets of tax planning for HNWIs. Cross-border issues require international tax specialists, while business owners need corporate tax strategists. Without a coordinated approach, HNWIs risk silos of suboptimal advice, where one advisor’s recommendation contradicts another’s. The solution lies in assembling a tax-focused advisory team early, before structures become entrenched.
Conclusion
Tax planning for high net-worth individuals is not a static playbook but a dynamic process that demands adaptability, transparency, and foresight. The myths that persist—offshore as a panacea, trusts as a luxury, or timing as irrelevant—reflect a broader disconnect between perception and reality. The evidence is clear: HNWIs who treat tax efficiency as a core discipline, not an afterthought, preserve and grow their wealth more effectively. This requires moving beyond generic advice to jurisdiction-specific strategies, asset-class optimization, and family wealth transfer planning. The most successful HNWIs don’t chase tax loopholes; they design systems that work within the rules while maximizing flexibility. Whether through private placement life insurance (PPLI), qualified personal residence trusts (QPRTs), or dynamic asset location, the goal is the same: align financial structures with tax realities. The difference between a good plan and a great one often comes down to how well it anticipates change—and how aggressively it adapts.Comprehensive FAQs
Q: How often should HNWIs review their tax plan?
A: At least annually, with deeper reviews every 3–5 years or after major life events (e.g., marriage, relocation, business sales). Market shifts—such as changes to capital gains rates or estate tax exemptions—also warrant reassessment. Proactive HNWIs integrate quarterly check-ins to adjust for LTCG harvesting opportunities or foreign tax credit planning.
Q: Are there tax advantages to holding real estate in an LLC?
A: Yes, but it depends on the structure. A single-member LLC offers pass-through taxation, avoiding corporate-level taxes, while a multi-member LLC taxed as a partnership can provide loss harvesting benefits. For commercial real estate, an S-corporation may defer self-employment taxes. However, state-level taxes (e.g., California’s 1.5% LLC fee) and transfer taxes must be factored in. Consult a real estate tax specialist to model the optimal setup.
Q: Can HNWIs use charitable giving to reduce taxes?
A: Absolutely. Strategies include:
- Donor-advised funds (DAFs): Allow immediate deductions while deferring distributions.
- Charitable remainder trusts (CRTs): Provide income for life while transferring residual assets to charity.
- Bunching deductions: Accelerating donations in high-income years to exceed the standard deduction threshold.
Q: What’s the best way to handle foreign income for U.S. citizens?
A: U.S. citizens are taxed on worldwide income, but Foreign Earned Income Exclusion (FEIE) and Foreign Tax Credit (FTC) can mitigate double taxation. For passive income (e.g., dividends, rent), the Foreign Tax Credit is often more beneficial. Puerto Rico Act 60 offers a 4% flat tax on business income for qualifying residents. However, PFIC rules (for foreign mutual funds) and FBAR/FATCA filings add complexity. A cross-border tax attorney should design a structure that balances tax efficiency with compliance risks.
Q: How do estate taxes impact HNWIs differently now?
A: The estate tax exemption doubled to $12.92 million per individual (2023) under the TCJA, but this is set to sunset in 2026 (reverting to ~$6 million). HNWIs should:
- Use grantor retained annuity trusts (GRATs) to transfer wealth at low-interest rates.
- Explore irrevocable life insurance trusts (ILITs) to fund estates without triggering inclusion ratios.
- Monitor state-level estate taxes (e.g., Massachusetts, Oregon), which kick in at $1M–$2M.
