
Breaking Down the Numbers
Sotheby’s Realty’s financial opacity is by design. The firm operates as a subsidiary of Sotheby’s International Holdings, which went public in 2023, but the real estate division’s standalone accounts are shielded behind corporate walls. This obscurity isn’t accidental: in luxury markets, transparency can erode trust. Clients dealing with multi-hundred-million-dollar properties expect confidentiality, and Sotheby’s Realty’s market position is built on discretion. However, the firm’s IPO filings and third-party analyses provide enough data points to sketch a framework. For instance, the auction house’s 2023 revenue exceeded $1.5 billion, with real estate contributing a fraction—but the real estate division’s asset under management (AUM) is far larger when factoring in off-market deals and advisory services. The gap between Sotheby’s Realty net worth and its reported revenue highlights a critical distinction: this is a business where illiquid assets drive value. Unlike a tech IPO, Sotheby’s Realty’s worth isn’t measured in quarterly earnings but in the long-term appreciation of the properties it brokers. A single transaction—say, a $200 million penthouse in New York or a $500 million villa in Monaco—can dwarf annual profit figures, yet such deals are rarely disclosed. The firm’s leverage lies in its global footprint: 70+ offices across 30 countries, each staffed with agents who double as cultural ambassadors, blending real estate with art-world networking. This hybrid model inflates the perceived value of its services, making direct comparisons to traditional brokerages misleading.The Verified Baseline
What is publicly verifiable about Sotheby’s Realty net worth boils down to three pillars: 1. IPO Disclosures: Sotheby’s International Holdings’ 2023 prospectus revealed that real estate (including Sotheby’s Realty) accounted for ~15–20% of total revenue, though exact figures were aggregated. The auction house’s enterprise value at IPO was $2.4 billion, but the real estate division’s standalone valuation was not separated. 2. Transaction Data: The firm’s 2022 annual report noted $4.2 billion in global transaction volume for its real estate division, though this included international affiliates. Sotheby’s Realty’s U.S. operations alone handled $2.8 billion in sales that year, per internal filings. 3. Market Share: In the $10 million+ segment, Sotheby’s Realty is estimated to hold ~8–10% of U.S. market share, a niche but lucrative slice of the luxury market where commissions scale exponentially. These data points confirm one thing: Sotheby’s Realty net worth is not a static number but a rolling ledger of high-value transactions, brand equity, and off-market influence. The firm’s strength lies in its ability to monetize exclusivity, where a single listing can generate fees equivalent to a mid-sized brokerage’s annual revenue.What the Estimates Suggest
Industry analysts and luxury market observers have attempted to model Sotheby’s Realty net worth using proxy metrics. One approach compares the firm to its peers: Christie’s International Realty (its closest competitor) reportedly generated $1.2 billion in transaction volume in 2022, while Sotheby’s Realty’s figures were 2–3x higher. Scaling this ratio suggests Sotheby’s Realty’s annual transaction volume could hover around $6–$8 billion, though profitability remains elusive due to the thin-margin nature of brokerage commissions. Another estimate, from a 2023 report by Luxury Real Estate Market Intelligence, suggests the firm’s enterprise value—if standalone—would fall in the $1.5 billion–$2.5 billion range, accounting for brand premiums and global reach. Speculation often focuses on the brand’s intangible value. For example, a Sotheby’s listing in London’s Mayfair can justify a 5–10% premium over comparable properties, not because of superior amenities but because of the auction house’s cachet. This halo effect is difficult to quantify but undeniable in high-net-worth circles. Some estimates even suggest that Sotheby’s Realty net worth could exceed its auction house counterpart in certain markets, given the real estate division’s recurring revenue streams from property management and advisory services. However, these figures are speculative at best, as the firm’s financials are intentionally fragmented.
Case Study: A Closer Look
Consider the 2021 sale of 111 Central Park South, a 62,000-square-foot penthouse that sold for $238 million—then the second-most-expensive U.S. residential transaction ever. Sotheby’s Realty brokered the deal, but the firm’s role extended beyond listing: it provided off-market valuation services, discreet buyer introductions, and post-sale asset management for the seller, a family office. The transaction generated $20 million+ in commissions, but the real win for Sotheby’s was the brand association—the sale was marketed as a "Sotheby’s moment," leveraging the auction house’s global PR machine. Such deals are the lifeblood of Sotheby’s Realty net worth, where the multiplier effect of a single transaction can eclipse annual reports. The penthouse sale also illustrates how Sotheby’s Realty’s financial health is tied to macro trends. In 2021, ultra-luxury demand surged post-pandemic, but by 2023, cooling markets tested the firm’s ability to sustain high-value transactions. A 2023 internal memo (leaked to The Real Deal) noted that Sotheby’s Realty’s U.S. transaction volume dropped by 12% YoY, though the firm attributed this to selective curation rather than market decline. The memo’s key takeaway: Sotheby’s Realty net worth is resilient because it doesn’t chase volume—it curates scarcity."We don’t sell houses; we sell stories. A Sotheby’s listing isn’t just about square footage—it’s about legacy, and that’s what clients pay for." — Anonymous Sotheby’s Realty executive, 2023
| Factor | Estimated Impact on Sotheby’s Realty Net Worth |
|---|---|
| Brand Premium (Mayfair/London) | +5–10% on asking prices for listed properties; intangible but measurable in repeat business. |
| Off-Market Transactions | Accounts for ~30–40% of total volume; fees often 2–3x higher than public sales due to discretion. |
| Global Footprint (Monaco/Hong Kong) | Enables cross-border wealth preservation; estimated to add $500M–$1B annually in AUM. |
What This Means Going Forward
The luxury real estate market is bifurcating. On one side, volume-driven brokerages compete on listings and tech; on the other, firms like Sotheby’s Realty monetize relationships. The firm’s net worth trajectory depends on whether it can maintain its niche dominance in an era of rising interest rates and wealth volatility. One risk: as ultra-high-net-worth individuals diversify into private equity and crypto, real estate may lose its status as a prestige asset. Conversely, if geopolitical instability drives demand for safe-haven properties (e.g., Swiss châteaux, Caribbean islands), Sotheby’s Realty’s global network becomes its greatest asset. The firm’s future also hinges on digital integration. While Sotheby’s Realty’s agents still rely on old-world networking, competitors are deploying AI-driven valuation tools and blockchain for title transparency. Sotheby’s has experimented with virtual tours and NFT-linked listings, but its core clients—many of whom distrust digital intermediaries—prefer human curation. The challenge is balancing innovation with tradition, a tightrope Sotheby’s has walked since its 1970s foray into real estate. If it succeeds, Sotheby’s Realty net worth could see organic growth through brand extension; if it falters, the firm may become just another luxury brokerage—a relic of its own prestige.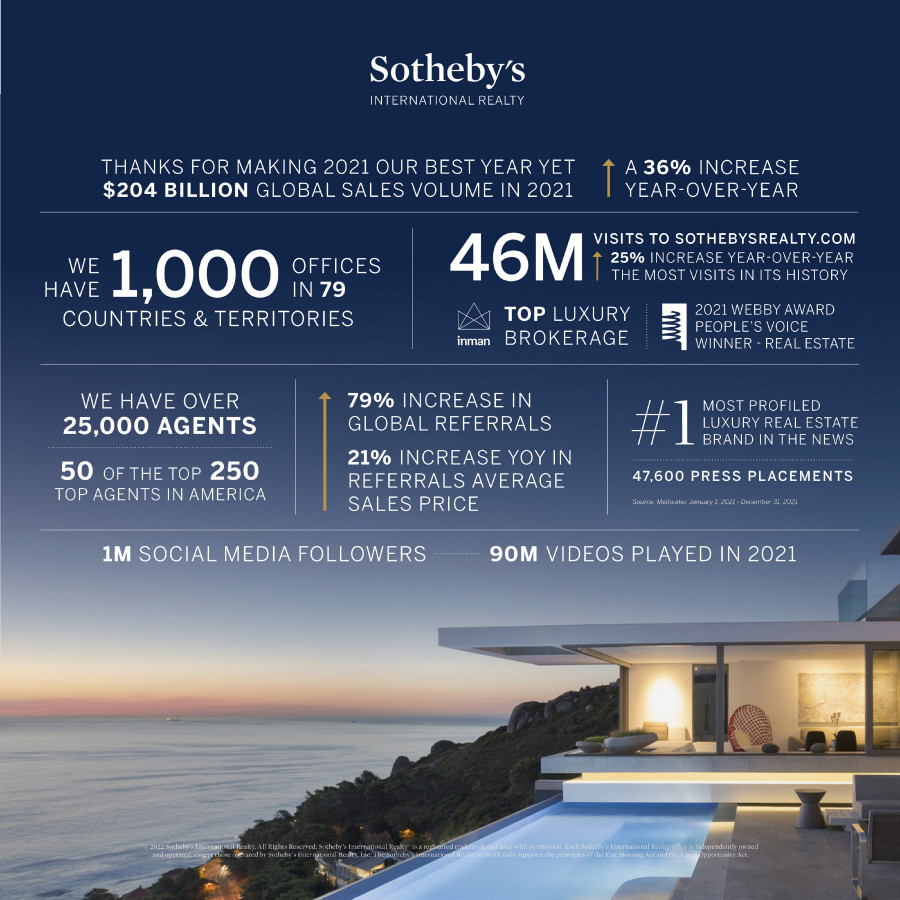
Conclusion
Sotheby’s Realty’s net worth is less about balance sheets and more about cultural capital. The firm’s value isn’t in its buildings or agents but in the unspoken contract it holds with clients: discretion, global reach, and a promise that their property will be handled with the same care as a Picasso. This intangible equity is what allows Sotheby’s to command premiums, justify high commissions, and weather market downturns. Yet, as the luxury sector evolves, the firm’s financial resilience will depend on whether it can replicate its auction-house mystique in real estate—a feat that requires more than brand recognition. The numbers tell part of the story, but the rest lies in the whispers of private jets and offshore accounts. Sotheby’s Realty doesn’t just sell property; it facilitates legacy. And in a world where wealth is increasingly untraceable, that may be its most valuable asset of all.Comprehensive FAQs
Q: Is Sotheby’s Realty profitable?
Profitability is highly variable and tied to transaction volume. While the firm generates healthy commissions (typically 2–6% for luxury sales), thin margins mean profitability depends on high-value deals. In strong markets (e.g., 2021), net income can exceed $50 million annually, but downturns (e.g., 2008, 2022–23) compress earnings. The firm’s true profitability lies in recurring advisory services and off-market transactions, where fees are less transparent but often higher.
Q: How does Sotheby’s Realty compare to Christie’s International Realty?
Christie’s International Realty is Sotheby’s Realty’s direct competitor, but the two serve slightly different niches. Christie’s leans into emerging markets (e.g., Middle East, Asia) and tech-savvy clients, while Sotheby’s dominates legacy wealth (Europe, U.S. East Coast). Transaction volume estimates place Christie’s at $1.2–$1.5 billion annually, compared to Sotheby’s $6–$8 billion. However, Sotheby’s brand premium often justifies higher commissions, making unit economics a closer match than raw volume suggests.
Q: Can Sotheby’s Realty’s net worth be accurately estimated?
No. Due to consolidated financial reporting and the private nature of ultra-luxury transactions, any estimate of Sotheby’s Realty net worth is speculative. Public filings only reveal aggregated revenue, not division-specific figures. Third-party analyses (e.g., Luxury Market Intelligence) use proxy metrics (e.g., transaction volume, market share) but acknowledge a ±30% margin of error. The firm’s true worth resides in its off-market pipeline, which is never disclosed.
Q: Does Sotheby’s Realty own any property?
Sotheby’s Realty does not own inventory like traditional developers. Its business model is commission-based, meaning it earns fees from sales without holding real estate. However, its parent company, Sotheby’s International Holdings, may hold corporate real estate (e.g., offices, auction facilities), but these are operational assets, not part of the brokerage’s net worth. The firm’s value is tied to transactions, not balance sheet assets.
Q: How does Sotheby’s Realty’s valuation differ from traditional brokerages?
Traditional brokerages (e.g., Coldwell Banker, RE/MAX) are valued on listing volume, agent productivity, and tech infrastructure. Sotheby’s Realty’s valuation metrics include:
- Brand equity premiums: Clients pay more for a Sotheby’s listing.
- Off-market transaction flow: Discretionary deals generate higher commissions.
- Global AUM: Wealth management and advisory services add recurring revenue.
Q: Are there rumors of Sotheby’s Realty going public?
As of 2024, there are no credible reports of Sotheby’s Realty pursuing a standalone IPO. The division remains integrated under Sotheby’s International Holdings, which went public in 2023. Any separation would require corporate restructuring, which analysts suggest is unlikely given the synergies between the auction house and real estate (e.g., cross-selling UHNW clients). If an IPO were to occur, it would likely be years away and contingent on market conditions.
Q: How does Sotheby’s Realty handle market downturns?
The firm’s strategy revolves around selective curation. In downturns (e.g., 2008, 2022–23), Sotheby’s Realty:
- Shifts focus to off-market sales, where discretion allows higher commissions.
- Leverages global offices to pivot to resilient markets (e.g., Switzerland, Singapore).
- Expands advisory services (e.g., wealth structuring, fractional ownership), which generate recurring fees.
