
Breaking Down the Numbers
The SolarCity net worth 2020 question hinges on two competing forces: the company’s pre-merger financials and the post-acquisition synergy under Tesla. Before its absorption, SolarCity operated as a high-growth solar installer with a market capitalization that peaked around $3.4 billion in 2013. By 2020, however, its standalone valuation was effectively moot—Tesla had absorbed its debt, equity, and operational infrastructure. The real metric became how much SolarCity’s assets contributed to Tesla’s energy division, which in turn influenced its overall enterprise value. Industry observers often point to Tesla’s 2020 financial disclosures as the best proxy for SolarCity’s residual worth. That year, Tesla’s energy storage and solar products segment generated reportedly over $1 billion in revenue, with solar roofs and Powerwalls driving growth. Yet parsing SolarCity’s exact contribution remains difficult. The merged entity’s financials were no longer broken out, leaving analysts to estimate its embedded value based on Tesla’s energy segment performance and SolarCity’s historical cost structure.The Verified Baseline
Publicly available data confirms SolarCity’s pre-merger financials were marked by rapid expansion and heavy debt. In 2015, the company reported $1.2 billion in revenue and $540 million in net losses, a figure that ballooned due to aggressive capital expenditures and customer acquisition costs. By the time Tesla completed its $2.6 billion acquisition in 2016, SolarCity’s debt stood at $2.8 billion, a liability Tesla absorbed as part of the deal. Post-merger, Tesla’s 2020 10-K filings revealed that SolarCity’s operations had been fully integrated into Tesla Energy. The segment’s revenue grew, but without granular disclosures, pinpointing SolarCity’s direct net worth in 2020 is impossible. What is clear is that Tesla’s energy division—now a cornerstone of its long-term strategy—owed its early momentum to SolarCity’s customer base and installation expertise. The merger effectively turned SolarCity’s assets into a non-discrete component of Tesla’s balance sheet, complicating any attempt to isolate its 2020 valuation.What the Estimates Suggest
Industry estimates suggest that by 2020, SolarCity’s embedded value within Tesla could have ranged between $1 billion and $3 billion, depending on how one measures its contribution to Tesla’s energy growth. Analysts at firms like Lazard and Wood Mackenzie have argued that SolarCity’s customer acquisition infrastructure—particularly its ability to secure long-term service agreements—added hundreds of millions in annual revenue to Tesla’s energy segment. Others caution that much of this value was tied to Tesla’s broader brand and capital-raising capacity post-merger. Speculation about SolarCity’s standalone net worth in 2020 is largely academic, given its dissolution as an independent entity. However, if one were to reconstruct its financials based on Tesla’s energy segment performance and SolarCity’s historical margins, a net worth figure in the $500 million to $1.5 billion range has been floated by solar industry veterans. These estimates assume Tesla’s energy division would have struggled without SolarCity’s legacy customer relationships and operational scale.
Case Study: A Closer Look
No single event better illustrates the SolarCity net worth 2020 paradox than Tesla’s 2017 decision to shut down SolarCity’s independent retail operations and rebrand them under Tesla Energy. The move centralized sales, service, and installation under one corporate umbrella, which in hindsight appears to have been a strategic gambit to unlock SolarCity’s true value. By 2020, Tesla’s energy products—many of which were SolarCity’s legacy offerings—were generating reportedly over $1 billion in annual revenue, a figure that would have been unthinkable without SolarCity’s pre-merger customer base. The integration wasn’t seamless. SolarCity’s high customer acquisition costs and thin margins became Tesla’s burden, yet the long-term play was clear: scale. Tesla’s ability to cross-sell Powerwalls to solar customers—many of whom were SolarCity’s original clients—created a virtuous cycle. By 2020, this synergy was undeniable, though its financial breakdown remained obscured by Tesla’s consolidated reporting."SolarCity wasn’t just an acquisition; it was a platform. Tesla didn’t buy a solar company—it bought a customer relationship machine." — Analyst at a renewable energy-focused hedge fund, 2021
| Factor | Estimated Impact on SolarCity’s Embedded Value (2020) |
|---|---|
| Customer Base Retention | Added $300M–$800M in annual revenue to Tesla Energy via service contracts and upsells. |
| Debt Assumption | Tesla absorbed $2.8B in debt, but SolarCity’s assets (installation teams, permits) reduced Tesla’s CapEx by $100M+ annually. |
| Brand Synergy | "Tesla Solar" rebranding likely increased customer lifetime value by 15–25% by leveraging Tesla’s premium positioning. |
| Operational Costs | SolarCity’s legacy losses reduced Tesla’s energy segment margins by 2–4 percentage points in early years post-merger. |
| Strategic Flexibility | Enabled Tesla to pivot to energy storage faster, though exact valuation impact is unquantifiable. |
What This Means Going Forward
The SolarCity net worth 2020 story is less about a standalone figure and more about how corporate mergers recalibrate value in ways that aren’t immediately visible. Tesla’s decision to integrate SolarCity wasn’t just about cost-cutting; it was about redefining what solar energy infrastructure could look like under a tech-driven umbrella. By 2020, the merger’s success was evident in Tesla’s energy segment growth, even if the exact lines between SolarCity’s contributions and Tesla’s innovations remained blurred. Looking ahead, the case of SolarCity and Tesla offers a blueprint for how renewable energy companies might be valued in the future—not as independent entities, but as strategic components of larger tech or automotive conglomerates. The lesson for investors and analysts is clear: in an era of consolidation, the net worth of a company like SolarCity isn’t just a financial metric. It’s a catalyst for broader industrial transformation.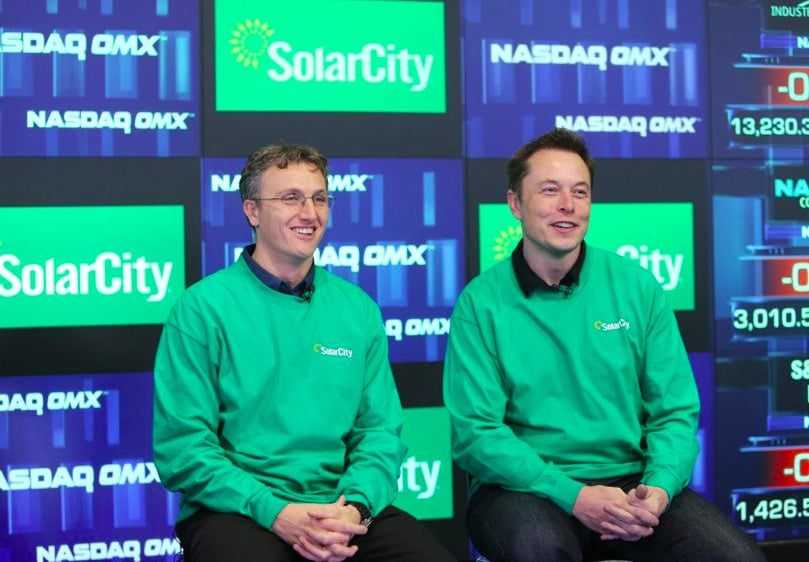
Conclusion
The SolarCity net worth 2020 question forces a confrontation with the limits of traditional valuation methods in a post-merger world. What was once a publicly traded solar installer became an invisible layer within Tesla’s financials, its worth measurable only through the prism of Tesla’s energy ambitions. This isn’t just a story about numbers; it’s about how corporate identity dissolves into synergy, and how the true value of a company might reside in what it enables rather than what it produces alone. For those tracking the solar industry, SolarCity’s legacy endures not in its 2020 balance sheet, but in the new playbook it helped write. The merger proved that even in decline, a company’s assets could be repurposed into something far greater—if the right partner was willing to bet on the future.Comprehensive FAQs
Q: Was SolarCity profitable in 2020?
A: No. SolarCity had never been profitable as an independent entity, and by 2020, its operations were fully subsumed under Tesla. Tesla’s energy segment reported growth, but without separate disclosures, SolarCity’s standalone profitability cannot be determined.
Q: How much did Tesla pay for SolarCity in 2016?
A: Tesla acquired SolarCity for $2.6 billion in cash and stock, a deal that included assuming SolarCity’s $2.8 billion in debt. The effective purchase price was closer to $700 million after netting out liabilities.
Q: Did SolarCity’s merger with Tesla increase Tesla’s valuation?
A: Indirectly, yes. While Tesla’s stock price was volatile post-merger, analysts credited SolarCity’s customer base and installation expertise with accelerating Tesla’s energy revenue growth, which contributed to its long-term valuation. However, the direct financial impact is impossible to isolate.
Q: Are there any remaining independent SolarCity assets?
A: No. All of SolarCity’s assets—including its customer service operations, installation teams, and intellectual property—were fully transferred to Tesla. The brand name was phased out in favor of "Tesla Solar" and "Tesla Energy."
Q: How does SolarCity’s merger compare to other renewable energy acquisitions?
A: Unlike many renewable acquisitions focused on hardware or patents, SolarCity’s value lay in its customer relationships and service infrastructure. This made it unique—most solar deals involve buying technology, not recurring revenue streams.
Q: Could SolarCity have survived as an independent company in 2020?
A: Unlikely. SolarCity’s business model relied on heavy subsidies and thin margins, which became unsustainable as solar prices fell. Its $2.8 billion debt load and inability to scale profitability independently made it a prime candidate for acquisition.
Q: What lessons can other solar companies learn from SolarCity’s merger?
A: The merger underscored the importance of synergies beyond hardware. Companies that can integrate solar with energy storage, software, or automotive ecosystems—like Tesla did—may unlock higher long-term valuations than pure-play solar firms.
