
5 Things Worth Knowing About Skechers Revenue 2024
The brand’s financial trajectory in 2024 hinges on five critical dynamics: its wholesale vs. DTC split, the performance of its athletic line, supply chain resilience, international expansion, and shareholder expectations. These elements don’t operate in isolation—they’re interconnected in ways that could either stabilize Skechers’ revenue streams or expose new vulnerabilities.1. The Wholesale-DTC Divide and Its Revenue Impact
Skechers’ 2024 revenue strategy is increasingly bifurcated between wholesale partnerships and its own digital platforms. While wholesale still dominates—accounting for roughly 60% of total revenue—DTC has become the fastest-growing segment, driven by the brand’s aggressive e-commerce push. The challenge lies in balancing these channels without overinvesting in one at the expense of the other. For instance, Skechers’ decision to reduce reliance on third-party sellers like Amazon in favor of its own website has improved margins but also required significant upfront costs in logistics and customer service. Analysts suggest that by mid-2024, DTC could represent nearly 35% of Skechers revenue, up from around 30% in 2023, but only if consumer adoption of its subscription model (Skechers Performance Club) accelerates. The wholesale side, however, isn’t static. Retailers are demanding more flexibility on terms as they grapple with their own inventory overhangs. Skechers has responded by offering promotional allowances and extended payment terms, which could pressure gross margins if not managed carefully. The brand’s ability to optimize this revenue split will be a key determinant of whether Skechers revenue 2024 meets or exceeds the $5.5 billion range analysts have floated.2. Athletic Performance as the Revenue Accelerator
The athletic segment is Skechers’ most high-stakes bet. Products like the Go Run collection and Arch Fit technology shoes are designed to compete with Nike’s running lines and Adidas’ lifestyle athletic wear. Early 2024 data shows these categories contributing around 20% of total revenue, a sharp increase from 15% in 2022. The catch? Athletic shoes require heavier marketing spend to drive awareness, and Skechers’ R&D costs per unit are higher than its casual footwear. If the performance line doesn’t gain sufficient traction, it could drag down overall Skechers revenue 2024 by diverting resources from proven categories. There’s also the risk of cannibalization. Skechers’ core customer—often price-sensitive millennials and Gen Z—may not be willing to trade down from premium athletic brands to Skechers’ mid-tier offerings. The brand’s solution has been to position its athletic line as accessible performance, but this messaging must resonate in a market where consumers increasingly equate performance with premium pricing.3. Supply Chain Resilience After 2023’s Turbulence
Skechers’ supply chain was a major weak point in 2023, with delays in Asia and port congestion in the U.S. contributing to missed revenue targets. For 2024, the brand has reportedly nearshored production for some lines, moving manufacturing closer to North America and Europe to reduce lead times. This shift comes with higher costs, but the trade-off is greater agility in responding to demand fluctuations. The question is whether Skechers can translate these operational improvements into revenue gains without sacrificing quality or pricing. Industry estimates suggest that supply chain efficiencies could add 2-3% to Skechers revenue 2024, assuming no major disruptions like labor strikes or geopolitical escalations. However, the brand’s reliance on Vietnam and China for the bulk of its production means it’s still exposed to regional risks. A prolonged U.S.-China trade conflict, for example, could force Skechers to reallocate production at short notice, potentially squeezing margins.4. International Markets as the Wildcard
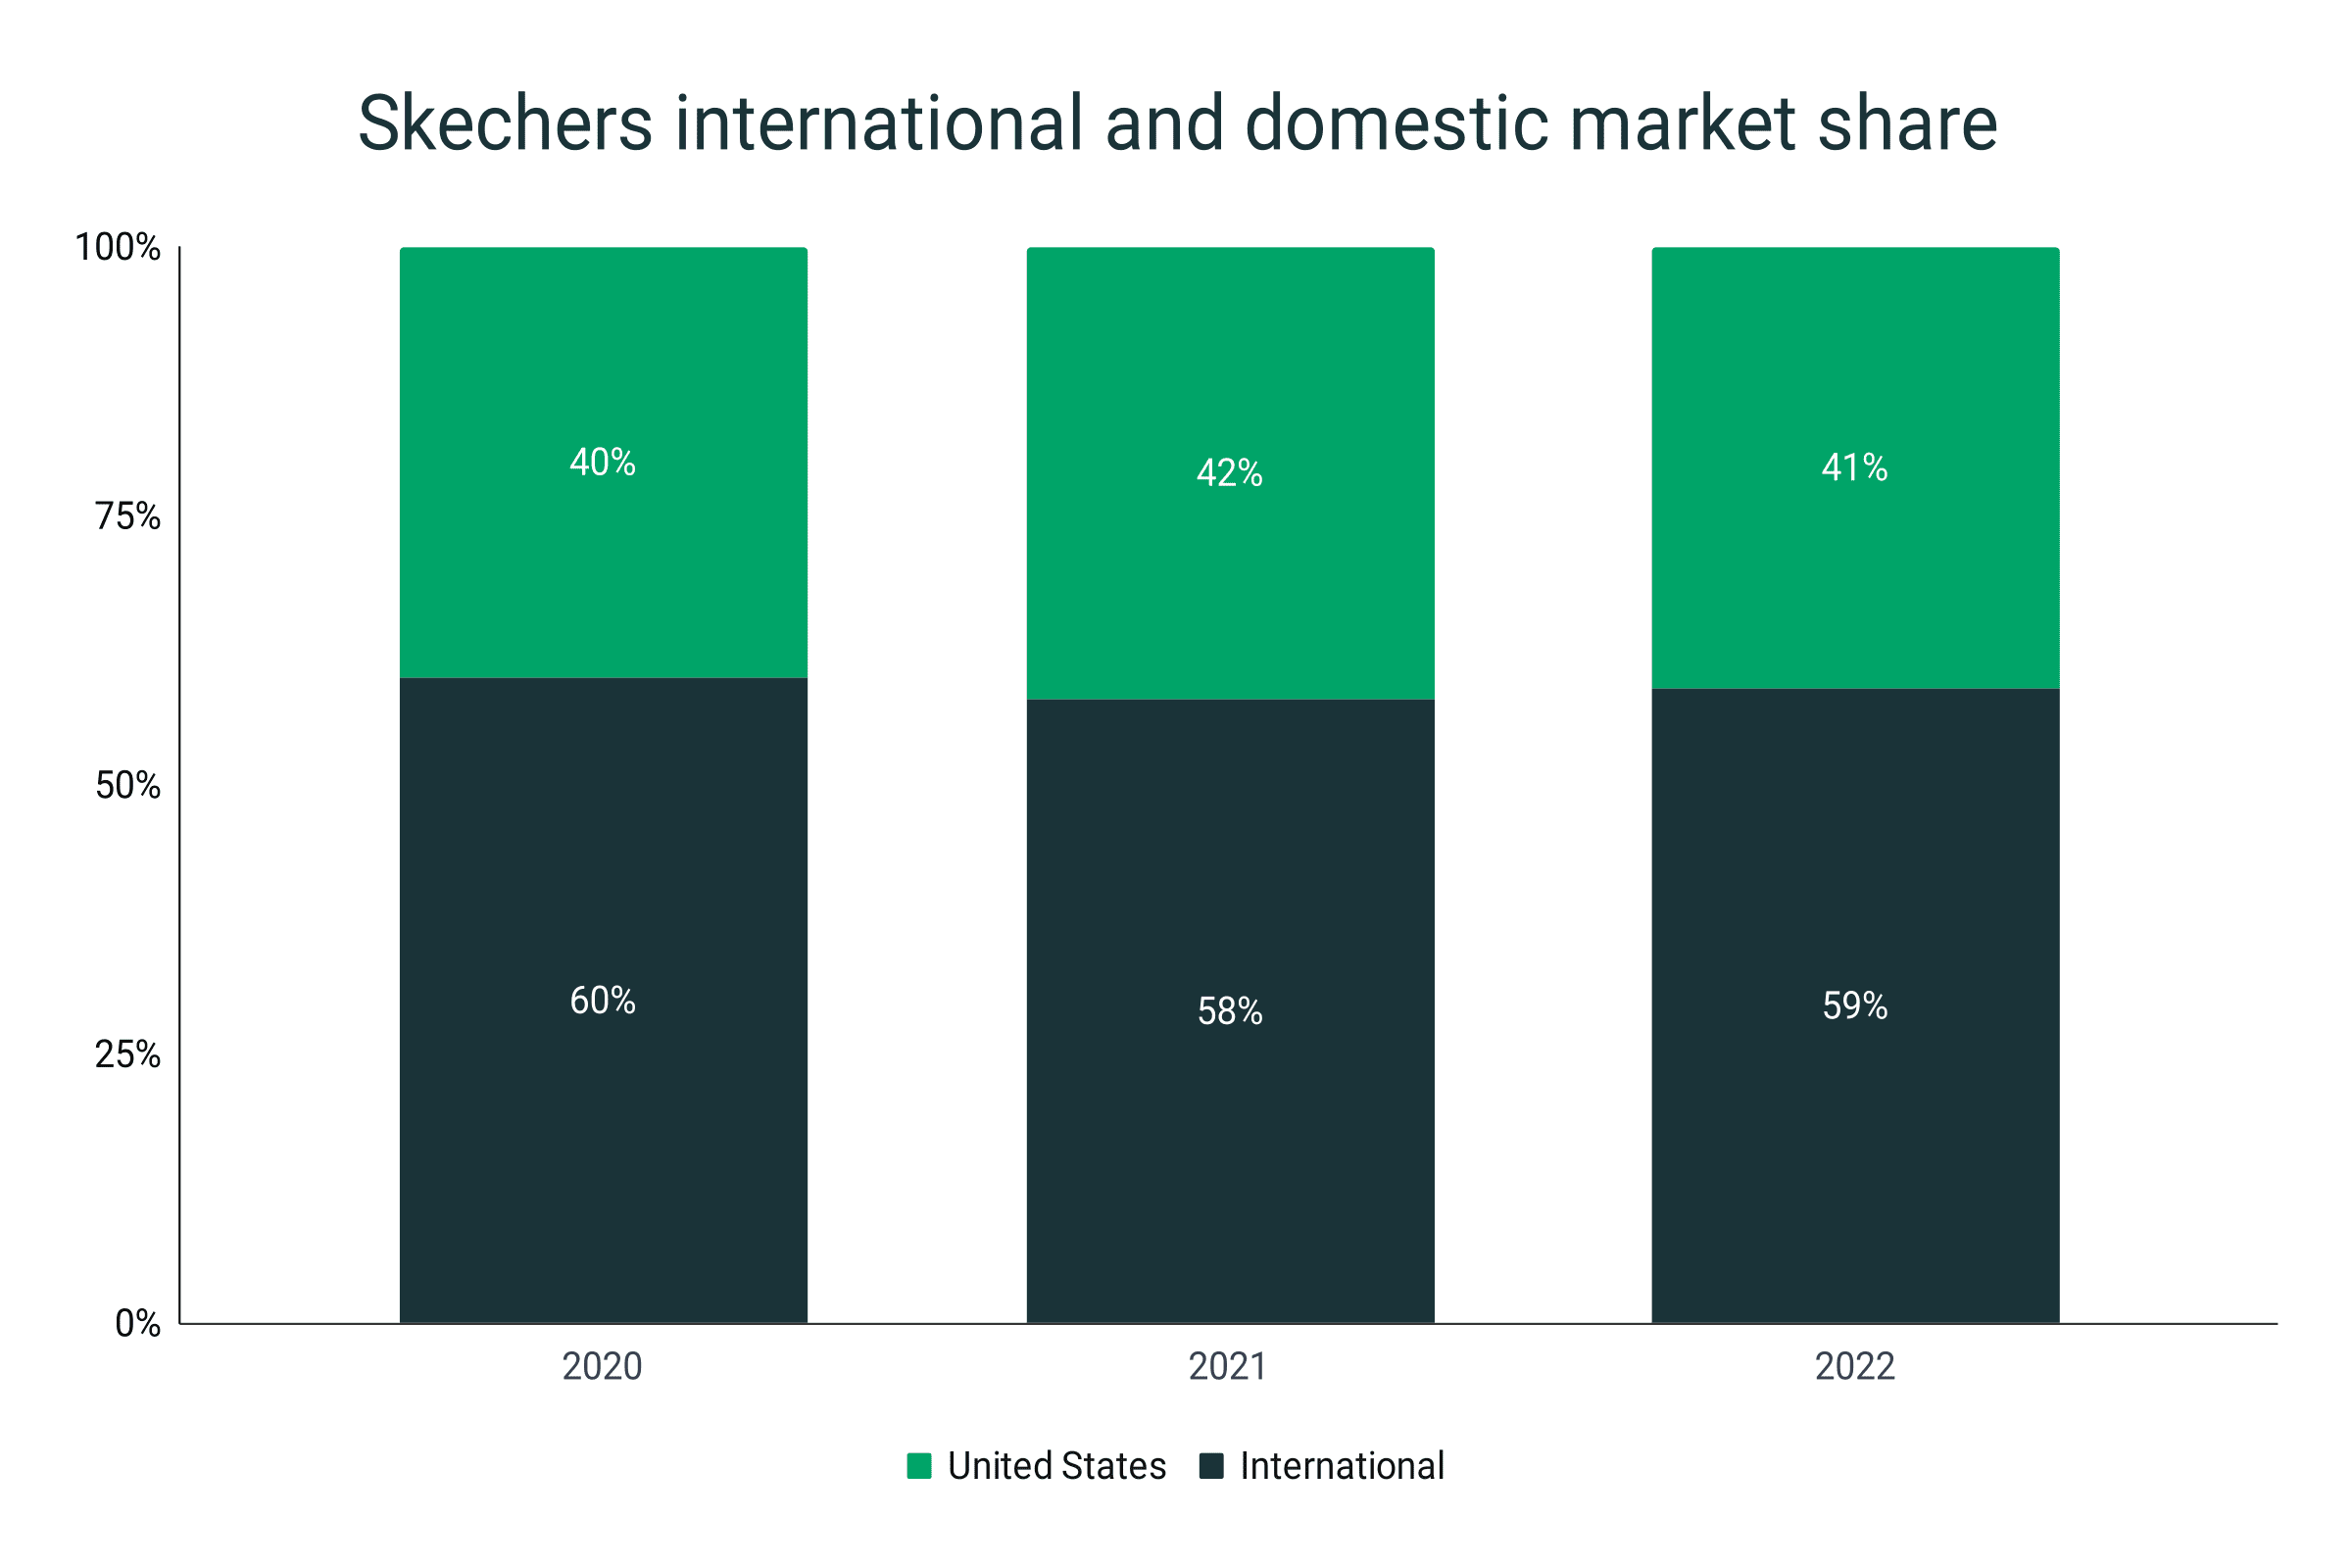
While the U.S. remains Skechers’ largest market (accounting for over 50% of revenue), international growth is a critical lever for Skechers revenue 2024. The brand has made inroads in Europe through partnerships with local retailers and its own flagships in cities like London and Paris. Asia, however, presents a mixed picture: strong demand in Japan and South Korea contrasts with slower growth in China, where Skechers has struggled to compete with domestic brands like Li-Ning and Anta. A deeper dive into Skechers’ international strategy reveals a focus on emerging markets like India and Southeast Asia, where e-commerce penetration is rising. The brand’s decision to launch a localized DTC platform in India in early 2024 is seen as a calculated move to bypass traditional wholesale channels and capture revenue directly. Yet, success here depends on Skechers’ ability to navigate localized consumer preferences—for instance, sizing variations and cultural trends that differ sharply from Western markets.5. Shareholder Pressure and the Valuation Gap
Skechers’ stock performance has lagged behind peers like Under Armour and Deckers (which owns Hoka), partly due to revenue growth that hasn’t translated into consistent earnings. Investors are increasingly asking whether Skechers’ expansion is sustainable or speculative. The brand’s response has been to emphasize margin improvement over top-line growth, a shift that’s reflected in its 2024 capital allocation plans.“Skechers isn’t just chasing revenue anymore—it’s chasing unit economics,” said a retail analyst with William Blair. “The market is rewarding brands that can grow revenue while also tightening the cost structure. Skechers’ ability to do that in 2024 will define whether it’s a turnaround story or just another cyclical player.”This focus on profitability is evident in Skechers’ decision to reduce wholesale discounts and invest in automation for its fulfillment centers. The trade-off? Slower revenue growth in the short term if retailers push back on pricing. The brand’s 2024 revenue guidance (reportedly targeting $5.4–$5.6 billion) reflects this balancing act, but it also leaves little room for error in execution.
How These Facts Connect
Skechers’ 2024 revenue outlook isn’t a story of one dominant factor but of interdependent risks and opportunities. The wholesale-DTC divide, for example, isn’t just about sales channels—it’s about customer loyalty. Skechers’ DTC growth depends on its ability to replicate the in-store experience online, while its wholesale partners rely on Skechers to provide consistent, high-margin products. The athletic performance push, meanwhile, isn’t just a product strategy; it’s a brand repositioning that could either elevate Skechers into the premium tier or dilute its value proposition for budget-conscious shoppers. Supply chain resilience ties these threads together. A smooth production flow ensures that Skechers can meet demand in both DTC and wholesale channels, while international expansion requires localized supply chain agility. The pressure from shareholders adds another layer: if Skechers prioritizes revenue growth over margin discipline, it risks overproducing inventory—a mistake that would hurt both top and bottom lines. Conversely, if it tightens margins too aggressively, it might stifle the very growth it needs to justify its valuation. The table below compares the three most critical revenue drivers and their potential impact on Skechers’ 2024 financials:| Revenue Driver | Projected Contribution to 2024 Revenue | Key Risk |
|---|---|---|
| Direct-to-Consumer (DTC) | ~35% of total revenue (up from 30% in 2023) | Customer acquisition costs outpacing retention |
| Athletic Performance Line | ~20% of total revenue (up from 15% in 2022) | Cannibalization of casual footwear sales |
| International Markets | ~25% of total revenue (growth in India/Southeast Asia) | Regulatory hurdles in China and Europe |
Conclusion
Skechers’ 2024 revenue trajectory will be determined by how well it executes on three fronts: operational efficiency, product innovation, and customer segmentation. The brand’s wholesale partners, once its lifeline, are now a double-edged sword—offering stability but also requiring careful management to avoid margin erosion. Meanwhile, its athletic line represents a high-risk, high-reward gamble that could redefine Skechers’ market position or become a costly distraction. The most optimistic scenario for Skechers revenue 2024 sees the brand hitting the upper end of its guidance, with DTC growth offsetting any slowdown in wholesale. The base case, however, assumes modest growth—enough to keep investors engaged but not enough to close the valuation gap with peers. The worst-case scenario involves supply chain disruptions or underperformance in athletic shoes, forcing Skechers to revise its outlook downward. What’s clear is that Skechers can no longer afford to treat revenue growth and profitability as separate goals. The two must move in lockstep if the brand is to emerge from its turnaround phase as a true industry contender.Comprehensive FAQs
Q: How does Skechers’ 2024 revenue compare to 2023?
Skechers reported revenue of approximately $5.3 billion in 2023, down slightly from $5.4 billion in 2022. For 2024, analysts expect a modest rebound to around $5.4–$5.6 billion, assuming no major disruptions. The growth will be driven by DTC expansion and the athletic performance segment, though wholesale revenue may stagnate due to retailer pushback on pricing.
Q: What percentage of Skechers’ revenue comes from athletic shoes in 2024?
Industry estimates place Skechers’ athletic shoe revenue at roughly 20% of total revenue in 2024, up from about 15% in 2022. This segment is a priority for the brand, but it remains a smaller portion of its business compared to competitors like Nike (where athletic shoes account for over 60%). Skechers is betting on volume growth rather than premium pricing to scale this category.
Q: How is Skechers’ supply chain strategy affecting its 2024 revenue?
Skechers has nearshored production for some lines to reduce lead times, which could add 2–3% to revenue by improving on-time deliveries. However, the shift has increased costs, and any supply chain bottlenecks—such as labor shortages or port delays—could offset these gains. The brand is also diversifying suppliers to mitigate risks, but this adds complexity to its procurement process.
Q: Is Skechers’ direct-to-consumer model profitable yet?
Skechers’ DTC margins are improving but still lag behind wholesale. The brand reports that its Skechers Performance Club subscription model is driving repeat purchases, but customer acquisition costs remain high. By mid-2024, DTC is expected to account for 35% of revenue, but profitability depends on Skechers’ ability to reduce fulfillment costs and increase average order values through bundling and upselling.
Q: What role does international revenue play in Skechers’ 2024 outlook?
International markets contribute around 25% of Skechers’ total revenue, with growth concentrated in India, Southeast Asia, and Europe. The brand is prioritizing localized DTC platforms in these regions to bypass traditional wholesale channels. However, China—once a bright spot—has seen slower growth due to competition from domestic brands, which could temper Skechers’ global revenue targets.
Q: How are Skechers’ stock performance and revenue growth connected?
Skechers’ stock has struggled to gain traction because revenue growth hasn’t translated into consistent earnings. Investors are now focusing on margin expansion rather than top-line growth. If Skechers can improve its gross margin by 1–2 percentage points in 2024, analysts believe its stock could see a revaluation. Until then, the brand remains a speculative play for growth investors rather than a blue-chip holding.
Q: What are the biggest risks to Skechers’ 2024 revenue?
The top risks include:
- Athletic performance underperformance: If Skechers’ Go Run and Arch Fit lines fail to gain traction, they could cannibalize casual shoe sales without adding sufficient revenue.
- Supply chain disruptions: Any prolonged delays in Asia or North America could delay product launches and erode retailer confidence.
- Wholesale retailer pushback: If Skechers raises prices too aggressively, retailers may reduce orders, hurting revenue.
- Macroeconomic slowdown: A recession could reduce discretionary spending on footwear, particularly in the U.S. and Europe.
