6 Things Worth Knowing About Student Loans and Net Worth
The tension between student debt and net worth calculations reveals deeper truths about modern finance. Here’s what you need to understand before deciding whether to include—or exclude—your loans from that critical number.1. Net Worth Was Never Designed for Student Loans
The concept of net worth originated in the 19th century as a tool for businesses and wealthy individuals to assess solvency. It was a binary measure: if your assets exceeded your liabilities, you were considered financially sound. But student loans, as we know them today, didn’t exist in that era. The first federal student loan program wasn’t established until 1965, and the modern system—with its mix of subsidized, unsubsidized, and private loans—emerged in the 1990s. The net worth framework assumes debt is either productive (like a mortgage) or consumptive (like credit card balances). Student loans defy that binary. They’re neither purely an investment nor a luxury expense; they’re a hybrid that funds an asset (education) while also creating a liability. The problem deepens when you consider that net worth calculations don’t account for the time value of student debt. A $30,000 loan taken out in 2005 might have ballooned to $60,000 by 2023 due to interest, but the degree it financed could have increased your earning potential by 50% or more over that period. Traditional net worth math treats the debt as a pure drag on wealth, ignoring the lagged benefit of the education itself. This is why some financial advisors argue that student loans in net worth calculations should be adjusted for their long-term ROI—something standard net worth statements don’t do.2. The Psychological Weight of Student Debt
Numbers on a page don’t capture the emotional burden of student loans. When you include them in your net worth, you’re not just tracking a balance—you’re confronting a daily reality. Studies show that borrowers with high student debt report higher levels of stress, anxiety, and even physical health issues compared to those without debt. This isn’t just correlation; it’s causation. The question of whether to count student loans in net worth becomes a mirror for how you perceive your financial identity. Excluding them might offer psychological relief, but it also risks creating a disconnect between your actual financial picture and your self-assessment. Consider the case of a 30-year-old professional with a $70,000 net worth but $40,000 in student loans. If they exclude the debt, their net worth looks strong—enough to buy a home or invest. But if they include it, their net worth plummets to $30,000, which might feel demoralizing. The choice isn’t just mathematical; it’s about how you want to feel about your progress. Some borrowers use exclusion as a motivator, a way to "trick" themselves into seeing progress. Others insist on inclusion as a form of accountability. There’s no right answer, only what works for your mental framework.3. How Lenders and Algorithms Treat Student Debt
The financial industry doesn’t treat student loans like other debts—and that matters when it comes to net worth. Credit scoring models, for example, penalize student loans less severely than credit card debt, even though the balances can be just as large. This is because lenders assume student debt is "good debt," tied to future earning potential. When you apply for a mortgage or a personal loan, your student debt will almost certainly be factored into your debt-to-income ratio. But when you’re calculating net worth for personal use, you have more flexibility. This disconnect highlights why the decision to include student loans in net worth can vary wildly depending on your goals. For instance, if you’re aiming to qualify for a mortgage, lenders will see your student loans as they are: a liability. But if you’re tracking progress toward financial independence, you might argue that the degree those loans funded is an asset worth offsetting the debt. The inconsistency suggests that net worth, as a personal metric, isn’t always aligned with how the broader financial system evaluates debt. This misalignment is why some advisors recommend maintaining two versions of net worth: one for external purposes (where loans are included) and one for personal motivation (where they might be excluded or adjusted).4. The Degree as an Intangible Asset
Here’s where the debate gets thorny: should student loans be counted in net worth if the degree they financed is an asset? Traditional net worth calculations don’t account for intangible assets like education, skills, or even health. But if you believe a degree increases your earning potential, shouldn’t that be factored in? The problem is that intangible assets are nearly impossible to value. How much is a marketing degree worth? It depends on the job market, your network, and even your personality. Some economists estimate that a bachelor’s degree adds $1 million or more in lifetime earnings, but that’s a rough average—your individual ROI could be higher or lower. This is why some financial planners suggest a hybrid approach: include the student loans in net worth, but also create a separate "human capital" ledger to track the value of your education over time. For example, if you earn $10,000 more per year because of your degree, you could argue that your net worth is higher than the raw numbers suggest. However, this method is subjective and requires constant updating. The alternative—excluding student loans entirely—ignores the debt’s real impact on your cash flow and liquidity. The tension between these approaches underscores why the question of counting student loans in net worth has no one-size-fits-all answer."Student loans are the only debt where the asset you’re buying is yourself—and yet, we treat them like any other liability in our financial statements. That’s a category error, and it’s why so many borrowers feel stuck." — Andrew Yang, entrepreneur and former presidential candidate, in a 2021 interview on financial literacy
5. Tax and Forgiveness Programs Complicate the Picture
Student loans don’t behave like other debts because they’re subject to unique tax and forgiveness rules. For example, under the Public Service Loan Forgiveness (PSLF) program, federal loans can be forgiven after 10 years of payments for borrowers in qualifying jobs. This means that, in some cases, student debt isn’t a lifetime burden—it’s a temporary obligation with a defined endpoint. If you’re on track for PSLF, including your full loan balance in net worth might be misleading, since a portion (or all) of it could disappear in a decade. Similarly, income-driven repayment plans cap monthly payments at a percentage of your discretionary income, which can make student debt feel more manageable over time. These programs introduce variability that standard net worth calculations don’t account for. If you’re in a high-paying field with PSLF eligibility, your net worth might look worse now but improve dramatically later. Conversely, if you’re in a low-paying field or your loans are private (non-forgivable), the debt could drag on your finances for decades. This unpredictability is why some advisors recommend adjusting student loans in net worth calculations based on your repayment plan. For example, you might count only the present value of your remaining debt, factoring in the likelihood of forgiveness or reduced payments later.6. The Net Worth Trap: What You’re Really Measuring
Here’s the unspoken truth: net worth is a tool, not a truth. It’s a snapshot, a way to gauge progress, but it’s not a measure of well-being, security, or happiness. When you exclude student loans, you’re not lying—you’re choosing a different lens. You might be focusing on liquid assets, investment growth, or cash flow instead of raw balance sheets. This is why some ultra-high-net-worth individuals with student debt still exclude it: they’re more interested in their ability to generate wealth than in the technical definition of net worth. For them, counting student loans in net worth would obscure the bigger picture—their earning power, their asset growth, and their long-term strategy. Conversely, for someone early in their career, including student loans might be a necessary wake-up call. It forces them to confront the reality of their debt-to-income ratio and adjust their spending or savings habits accordingly. The key is recognizing that net worth is what you make it. If excluding student loans helps you stay motivated, that’s valid. If including them keeps you disciplined, that’s also valid. The mistake is treating net worth as an absolute measure rather than a flexible tool.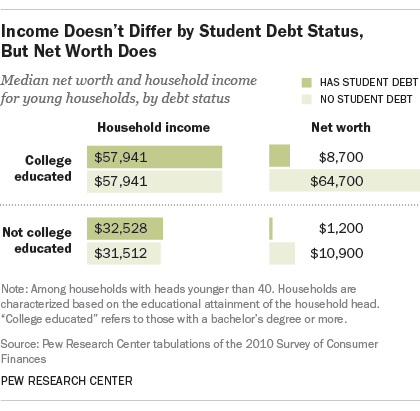
How These Facts Connect
The debate over whether student loans should be included in net worth isn’t just about accounting—it’s about how we define financial health in an era where education is both a necessity and a luxury. The six points above reveal a system that was never designed to handle student debt. Net worth calculations assume debt is either productive or consumptive, but student loans occupy a gray area. They’re neither purely an investment nor a frivolous expense; they’re a hybrid that forces borrowers to navigate conflicting priorities. At its core, the question exposes a larger tension: should personal finance be about numbers, or should it be about outcomes? If your goal is to maximize your balance sheet, including student loans makes sense. But if your goal is to build wealth, increase earning potential, or achieve financial independence, you might argue for a more nuanced approach—one that accounts for the intangible value of education while still acknowledging the real burden of debt. The table below compares the key considerations:| Factor | Include Student Loans in Net Worth | Exclude Student Loans in Net Worth |
|---|---|---|
| Accuracy | Reflects true financial position, including liabilities. | May overstate financial health, ignoring real debt obligations. |
| Psychological Impact | Can feel demotivating; highlights debt burden. | May provide false sense of progress; ignores real constraints. |
| External Use (Lenders, etc.) | Aligned with how lenders and algorithms evaluate debt. | May misrepresent financial capacity for loans/mortgages. |
| Long-Term Strategy | Useful for disciplined repayment planning. | May encourage focus on liquid assets over debt reduction. |
| Flexibility | Less room for adjustment (e.g., forgiveness programs). | Allows for creative accounting (e.g., offsetting with degree value). |
Conclusion
The question of whether to count student loans in net worth has no single correct answer because the question itself is flawed. Net worth is a blunt instrument, designed for a financial world where debt was either leveraged for assets or spent on consumption. Student loans don’t fit neatly into either category. They’re a product of a modern economy where higher education is both a pathway to opportunity and a financial albatross. The real insight isn’t whether to include or exclude them—it’s recognizing that the debate forces us to confront how we measure success. For some, including student loans is an act of honesty, a refusal to ignore the real constraints on their finances. For others, excluding them is a strategic move, a way to focus on what they can control: their savings, investments, and earning potential. The most sophisticated approach might be to use both methods—one for external purposes (where loans are included) and one for personal motivation (where they’re adjusted or excluded). What matters most isn’t the number itself, but what it tells you about your financial story.Comprehensive FAQs
Q: If I exclude student loans from my net worth, am I lying to myself?
A: Not necessarily. Excluding student loans is a form of financial storytelling—it’s about what you want to track. If your goal is to focus on liquid assets or investment growth, exclusion can be a useful tool. However, if your primary objective is to understand your true financial position, including the loans is more accurate. The key is transparency: if you exclude them, be clear about why and how it aligns with your broader financial strategy.
Q: Does including student loans in net worth affect my credit score?
A: No, your net worth calculation is a personal metric and doesn’t impact your credit score. However, your student loan balances do appear on your credit report, and high balances relative to your income can affect your debt-to-income ratio, which lenders consider when evaluating mortgage or loan applications. The two concepts are related but distinct.
Q: Should I adjust my net worth calculation if I’m on an income-driven repayment plan?
A: Yes, if you’re on an income-driven plan (IDR), you might consider adjusting your net worth to reflect the present value of your remaining debt, factoring in the likelihood of forgiveness or lower payments over time. For example, if your loans are on track for forgiveness in 10 years, counting only the present value (after discounting for time and potential forgiveness) could give a more realistic picture of your long-term financial position.
Q: What’s the difference between net worth and cash flow when it comes to student loans?
A: Net worth is a snapshot of your assets minus liabilities at a single point in time, while cash flow measures the money moving in and out of your accounts over a period (e.g., monthly or yearly). Student loans affect both: they reduce your net worth by increasing liabilities, but they also impact your cash flow through monthly payments. Some borrowers focus more on cash flow—ensuring their student loan payments don’t crowd out other financial priorities—while others prioritize net worth, aiming to grow their asset base despite the debt.
Q: Can I use two different net worth calculations—one with loans included and one excluded?
A: Absolutely. Many financial planners recommend maintaining two versions of net worth: one for external purposes (where loans are included) and one for personal motivation (where they might be excluded or adjusted). This dual approach allows you to stay disciplined about your debt while also tracking progress toward other financial goals, like saving for a home or retirement.
Q: Does the type of student loan (federal vs. private) change how I should count it in net worth?
A: Yes. Federal loans often come with protections like income-driven repayment, forgiveness programs, and lower interest rates, which can reduce their long-term impact on your net worth. Private loans, on the other hand, typically lack these safeguards and may carry higher interest rates, making them a more significant drag on your financial position. If you have private loans, you might argue for including them fully in your net worth, while federal loans could be adjusted based on your repayment plan.
