Where It All Began
The modern concept of net worth as a financial metric emerged in the late 19th century, not from personal finance blogs but from balance sheets of industrialists. John D. Rockefeller’s wealth wasn’t just about gold coins in a vault—it was about what he owned versus what he owed. The framework was simple: assets (land, factories, cash) minus liabilities (debts, mortgages) equaled net worth. For Rockefeller, this was a tool for expansion; for the average worker, it became a way to track progress. The 401(k) didn’t exist in Rockefeller’s era. It arrived in 1978 as a tax-deferred savings vehicle, initially a fringe benefit for executives. When Congress expanded it in the 1980s, making it accessible to rank-and-file employees, the question of whether retirement accounts should factor into net worth became inevitable. Early financial literature treated them as "illiquid assets," often excluded from snapshots of wealth. But by the 1990s, as 401(k)s ballooned into the primary retirement savings tool for millions, the omission struck many as artificial.The Early Signs
The first major shift came in the late 1990s, when personal finance experts like Suze Orman and David Bach began advocating for including 401(k)s in net worth calculations. Their argument was pragmatic: if you’re tracking your financial health, why ignore an asset that could fund your future? Critics countered that net worth was meant to reflect current liquidity, not hypothetical future spending power. The debate wasn’t just theoretical—it had real consequences. Someone with a $500,000 home and a $200,000 401(k) might feel wealthier (or more indebted) depending on whether they counted the latter. The turn of the millennium brought another complication: the dot-com crash and the Great Recession. Suddenly, 401(k) balances weren’t just numbers on a statement—they were volatile, market-dependent assets. For those who’d included them in their net worth during the boom, the crash forced a reckoning. Did excluding them protect against emotional whiplash? Or did including them provide a more honest picture of long-term stability?The Turning Point
The tipping point arrived in 2008, when the financial crisis exposed a critical flaw in how many people viewed their 401(k)s. For the first time, large swaths of the middle class saw their retirement accounts plummet by 30% or more overnight. Those who’d excluded their 401(k) from net worth calculations often felt a strange relief—until they realized they’d also missed the psychological boost of seeing their assets recover. The crisis proved that whether you include your 401(k) in net worth isn’t just a technical question—it’s a behavioral one. By 2010, the conversation had shifted from "should you?" to "how?" Financial planners began emphasizing that the decision hinged on why you were tracking net worth. If it was for debt management or budgeting, excluding the 401(k) might make sense. If it was for long-term planning or stress reduction, including it could be more beneficial. The line between theory and practice had blurred."Net worth isn’t a static number—it’s a story about your financial identity. If your 401(k) is part of that story, it belongs in the calculation. If it’s just noise, leave it out. But don’t pretend it doesn’t exist." — Jane Bryant Quinn, personal finance columnist (2012)
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1980s–1990s | 401(k)s became mainstream; early advisors excluded them from net worth due to illiquidity concerns. The focus was on "current spendable wealth." |
| 2000–2007 | Rising markets and financial literacy movements led to broader inclusion. Tools like Mint and Personal Capital automated net worth tracking, often defaulting to "include all assets." |
| 2008–2012 | The recession forced a reckoning. Many realized excluding 401(k)s masked volatility. Behavioral finance studies showed people who included them recovered faster from market downturns. |
| 2013–Present | Robo-advisors and fintech platforms standardized inclusion. The debate shifted to how to value 401(k)s (e.g., current balance vs. projected future value) rather than whether to include them. |
Lessons From the Journey
- Net worth is a tool, not a truth. Including your 401(k) doesn’t make it more real—it just makes your tracking more comprehensive. The key is consistency.
- Taxes distort the picture. A 401(k) is worth less to you today than its balance suggests because withdrawals are taxed. Adjusting for future taxes (if possible) can refine the calculation.
- Behavior matters more than balance sheets. People who include their 401(k) tend to save more aggressively, even when markets dip—a psychological edge over those who exclude it.
- The "right" answer depends on your goal. If you’re applying for a mortgage, lenders may ignore retirement accounts. If you’re planning for early retirement, they’re critical.
Where Things Stand Today
Today, the consensus leans toward inclusion—but with caveats. Most financial planners agree that your 401(k) should be part of your net worth, provided you account for its illiquidity and tax implications. The shift reflects a broader evolution in how we view wealth: it’s no longer just about what you can spend tomorrow, but what you can sustain over decades. Tools like YNAB (You Need A Budget) and Betterment now default to including retirement accounts, while purists still argue for exclusion. The debate hasn’t disappeared, though. High-net-worth individuals often face a different dilemma: whether to count their 401(k) alongside other investments like real estate or private equity. The answer often depends on their exit strategy. Someone planning to sell a business might treat their 401(k) as a secondary asset; someone relying on it for passive income will weigh it more heavily. The lines between "included" and "excluded" have become more fluid.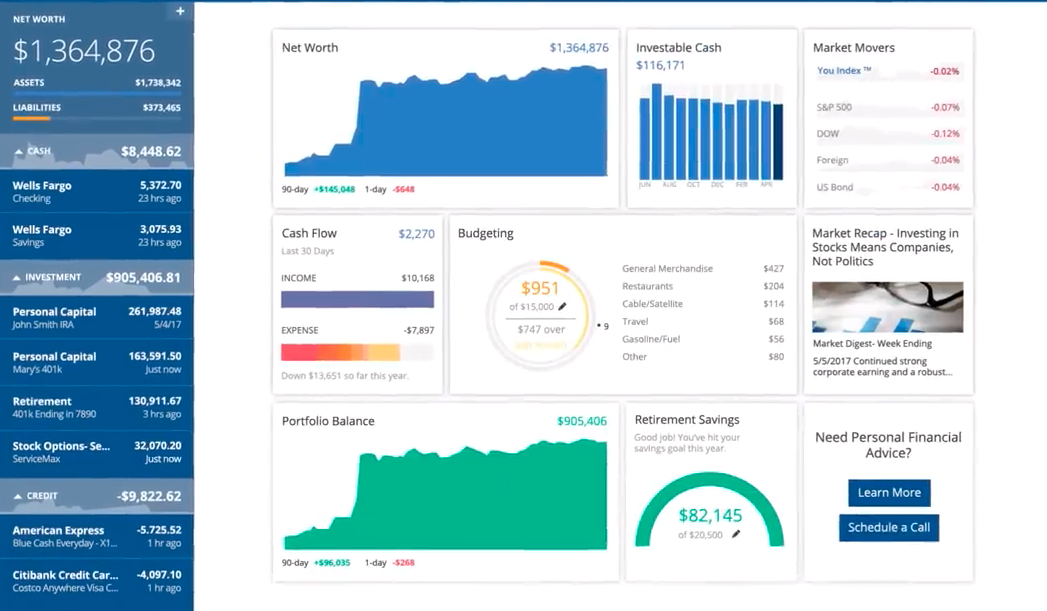
Conclusion
The question do I include 401(k) in my net worth isn’t about right or wrong—it’s about what you’re trying to measure. If your goal is to understand your total financial picture, the answer is yes. If you’re focused on immediate liquidity, the answer might be no. But the real insight lies in the process: tracking your net worth forces you to confront what you value, what you fear, and what you’re willing to sacrifice for long-term security. For most people, the 401(k) is the largest single asset they’ll ever own—yet it’s also the most constrained. Ignoring it in your net worth is like leaving a vault door open in your financial story. Including it, with full awareness of its rules and risks, is how you take control.Comprehensive FAQs
Q: Does including my 401(k) in net worth affect my credit score?
No. Net worth calculations are private and don’t impact credit reports. Your credit score is based on debt repayment history, not asset values—even if you include retirement accounts in personal tracking.
Q: Should I include my 401(k) if I’m considering an early retirement?
Absolutely. Early retirement planning hinges on sustainable withdrawal rates, and your 401(k) is likely the cornerstone of that strategy. Excluding it would give you a misleadingly optimistic view of your runway.
Q: What if my 401(k) has loans against it? Does that change anything?
Yes. A 401(k) loan is a liability, so you’d subtract it from the account’s balance before including the net value in your net worth. For example, a $200,000 account with a $50,000 loan contributes $150,000 to your net worth.
Q: Can I include the future value of my 401(k) instead of its current balance?
Some advisors suggest this for long-term planning, but it’s speculative. Future value depends on market returns, which you can’t predict. Stick to current balances unless you’re using professional projections.
Q: Does my employer match count toward net worth?
Only if it’s already been deposited into your account. Employer matches are free money, but they don’t belong in your net worth until they’re vested and in your control.
Q: What about Roth 401(k)s? Should I treat them differently?
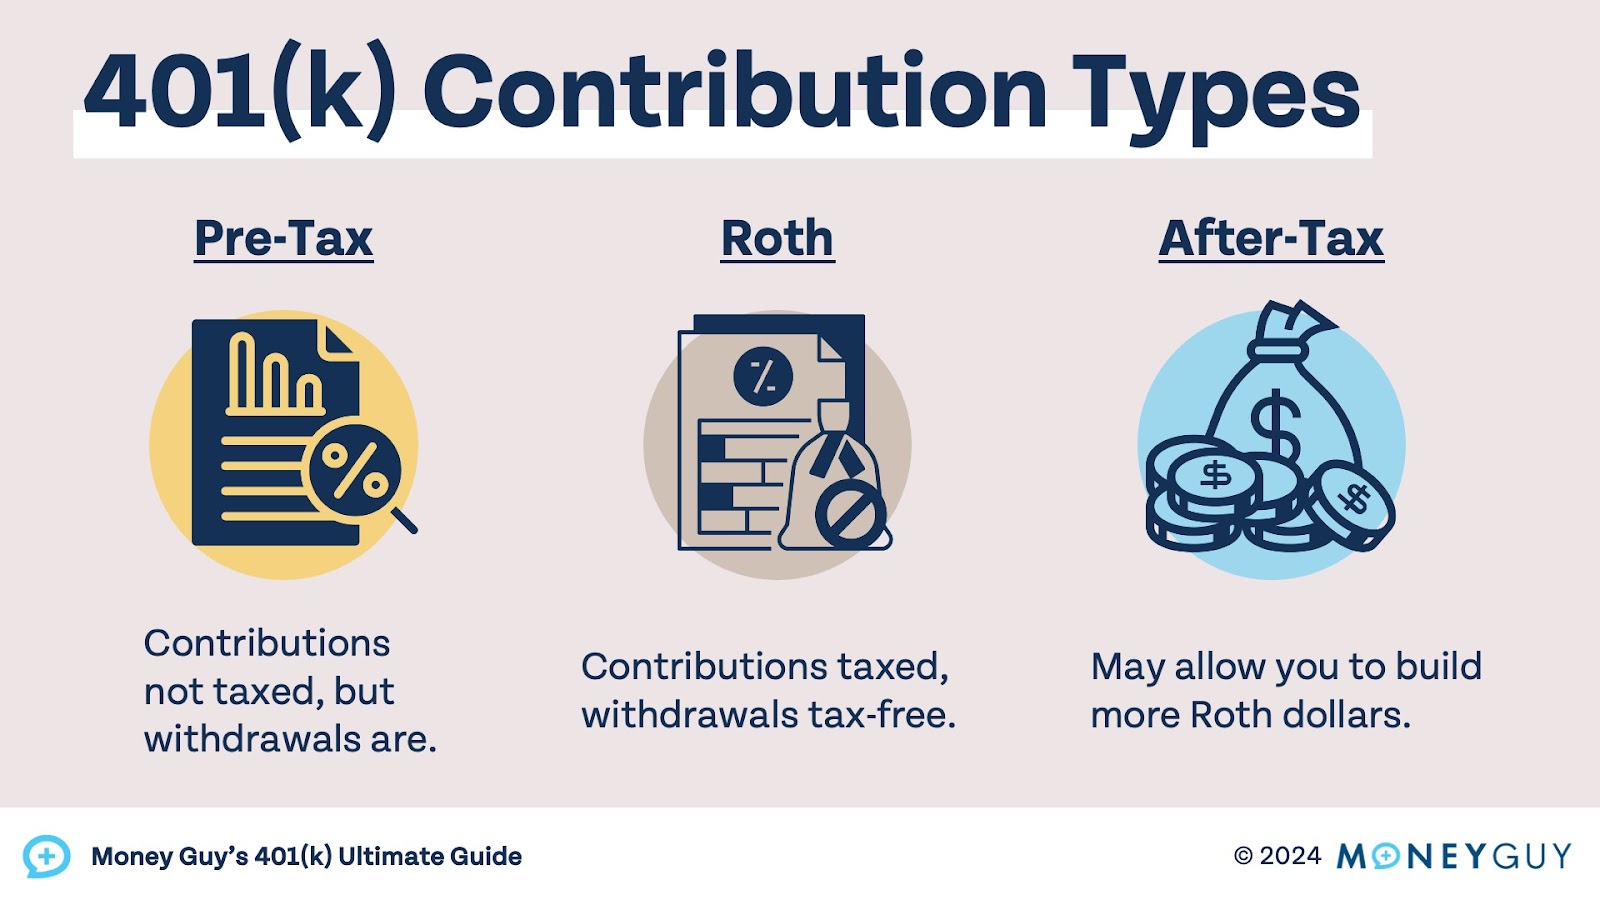
No—include them like traditional 401(k)s, but note that Roth contributions are post-tax, so their value isn’t reduced by future withdrawals. This can slightly inflate your net worth compared to pre-tax accounts.
Q: If I’m self-employed, does my Solo 401(k) count the same way?
Yes, the same rules apply. Solo 401(k)s are retirement accounts, not business assets, so they should be included in personal net worth calculations—just like employer-sponsored plans.
Q: What if my 401(k) is with a brokerage that offers loans? Does that make it more "liquid"?
Not in the traditional sense. A 401(k) loan is still a loan—it’s not spendable income, and it must be repaid with interest. Treat it as a liability, not liquidity, in your net worth.
